If you've tried budgeting before and quietly stopped, the problem probably wasn't you. Here's a budgeting setup with three rules, most of it automated, and one number to check before you spend.
Most people who call themselves bad with money aren't careless. They're tired. They've tried a budget that had 30 categories, felt bad every time a bar turned red, and stopped opening the app around week three. Then a $140 car insurance payment came out two days before payday, the account went negative, and the story about being bad with money got a little stronger. The best budgeting app for people bad with money isn't the one with the most features. It's the one that asks the least of you and still keeps the bills paid.
This guide is about building a system that works on your worst week, not your best one. That means very few rules, automating the boring parts so they happen without willpower, and replacing a detailed budget with one question: how much can I safely spend between now and payday? We'll cover what to look for in an app if you've quit a few before, where other tools fit, and what Sumyfi does and doesn't do for this.
You're probably not bad with money. Your system is too fragile.
Look at what actually goes wrong for most people. It's rarely one big irresponsible purchase. It's a string of small timing problems and forgotten costs: an annual Costco or Amazon renewal you didn't plan for, a phone bill that lands the day before your paycheque, a takeout habit that crept from twice a month to twice a week while you were busy. None of those are moral failures. They're things a system should catch and a tired person won't.
Avoidance makes it worse. When checking your balance feels bad, you stop checking. When you stop checking, the surprises get bigger, and checking feels even worse next time. Breaking that loop matters more than any budgeting method. If an app makes you feel judged, you'll avoid it the same way you avoid your banking app, so the tone of the tool is a real feature, not a nice extra.
So the goal here isn't discipline. It's making the right thing happen by default and making it easy to look at your money without flinching.
Overdraft or NSF fees more than once a year usually point to timing, not overspending
Not opening your banking app for a week or more is a sign the system feels punishing
Getting surprised by the same annual charge twice means it needs to be on a list
Feeling broke with a decent income often means small recurring costs have piled up
Three rules instead of thirty categories
Detailed budgets work well for people who enjoy them. If you're reading this, you probably don't, and that's fine. You can run your money on three rules and ignore almost everything else.
Notice that none of these ask you to track coffee or log every purchase. Groceries, gas, takeout and clothes all come out of one pot of spending money. If the pot runs low, you spend less until payday. That's the whole budget.
Once those three rules have held for two or three months, you can add more detail if you want it. Most people find they don't need much. One or two categories that tend to run away from them, often dining out or online shopping, are usually worth watching on their own. The rest can stay lumped together.
- Bills pay themselves: Rent, phone, insurance, utilities and card minimums go out on autopay so a forgotten due date can't cost you a late fee
- Savings leaves first: A fixed amount, even $25, moves to savings on payday before you see it
- One spending number: Whatever's left after bills and savings is what you can spend until the next paycheque
Automate the parts you keep forgetting
Every decision you don't have to make is one you can't get wrong. Spend one evening setting these up and they'll keep working long after your motivation fades.
Start with bill due dates. Many phone, internet and credit card providers will move a due date if you ask. If you're paid on the 15th and the last day of the month, get as many bills as possible due on the 2nd or 17th, a couple of days after money lands. That one phone call per bill fixes more overdrafts than any budget.
Next, set every credit card to at least the minimum payment on autopay. Paying the full statement balance is better, but autopaying the minimum protects you from late fees and credit score damage in a month where you forget. You can always pay more by hand.
Then set up an automatic transfer to savings for payday or the day after. Put the savings in an account at a different bank from your chequing, like an EQ Bank or Tangerine account in Canada or an Ally or Capital One 360 account in the US. When the money isn't sitting in the same app as your spending, you're much less likely to pull it back out for something that isn't an emergency.
The only number you need to check: what's safe to spend
Your bank balance lies to you. If it says $1,340, that doesn't mean you have $1,340 to spend, because some of it is already promised to bills that haven't come out yet. Spending against the raw balance is how people end up overdrawn with a budget that looked fine on paper.
The fix is a simple calculation. Take your current balance, subtract every bill due before your next paycheque, and subtract your savings transfer if it hasn't gone out yet. What's left is safe to spend.
Here's what that looks like with real numbers. Your chequing balance is $1,340 and payday is 12 days away. Before then you have a $65 phone bill, a $148 car insurance payment, $72 for internet and a $50 credit card minimum, which adds up to $335. Your $50 savings transfer goes out on payday, so leave that alone. That leaves $1,005, or roughly $83 a day for groceries, gas and everything else until the next paycheque.
That daily figure is far more useful than a category breakdown. If you spend $140 on a Saturday, you know the next couple of days need to be lighter. If you get to payday with money left over, move it to savings or the card balance and start the next pay period fresh. You don't need an app to do this math, a sticky note works, but an app that shows your upcoming bills in one place makes the subtraction much faster.
What to look for in a budgeting app if you've quit before
If you've abandoned two or three budgeting apps, look at why. It's usually one of the same few reasons: too much setup, too much manual entry, or a design that made you feel like you were failing. Pick for those, not for the longest feature list.
It's also worth being honest about the alternatives. YNAB is excellent for people who want a hands-on method where every dollar gets a job, but it asks for regular attention and some learning up front, which is exactly what tends to fall apart if you're already stretched. Your bank's own app probably shows spending by category for free, and that may be enough if all your accounts are at one bank. A simple spreadsheet works if you'll actually open it. There's no prize for using the most sophisticated tool.
Automatic transaction import
If you have to type in purchases, you'll stop. Bank sync or at least file import is the minimum.
Upcoming bills on one screen
Seeing what's due in the next week or two is what prevents overdrafts.
A calm design
Overspending should show up as information, not a wall of red warnings.
Few categories by default
You should be able to start with a handful and add more later.
A free plan or a real trial
You need at least one full pay cycle to know whether it fits.
What Sumyfi does for this, and where it falls short
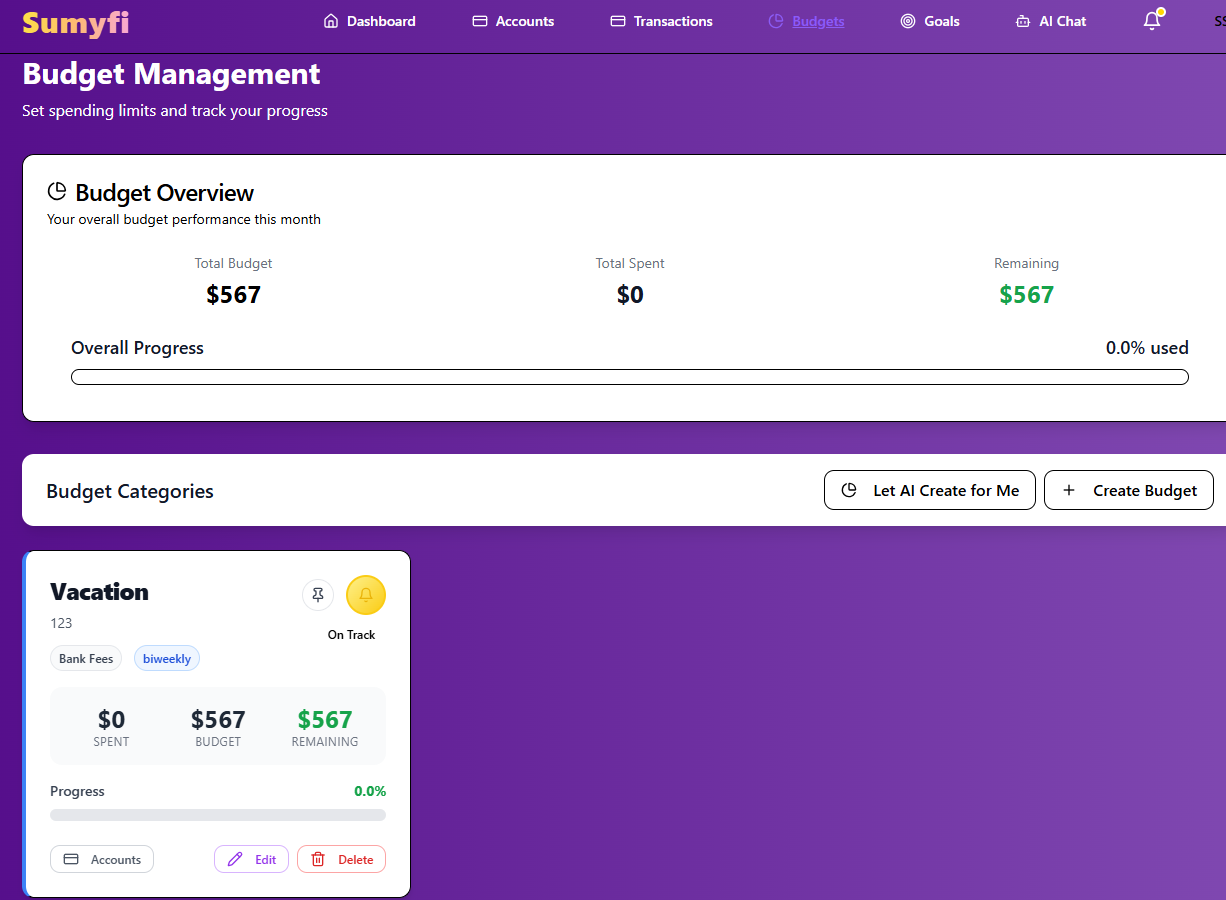
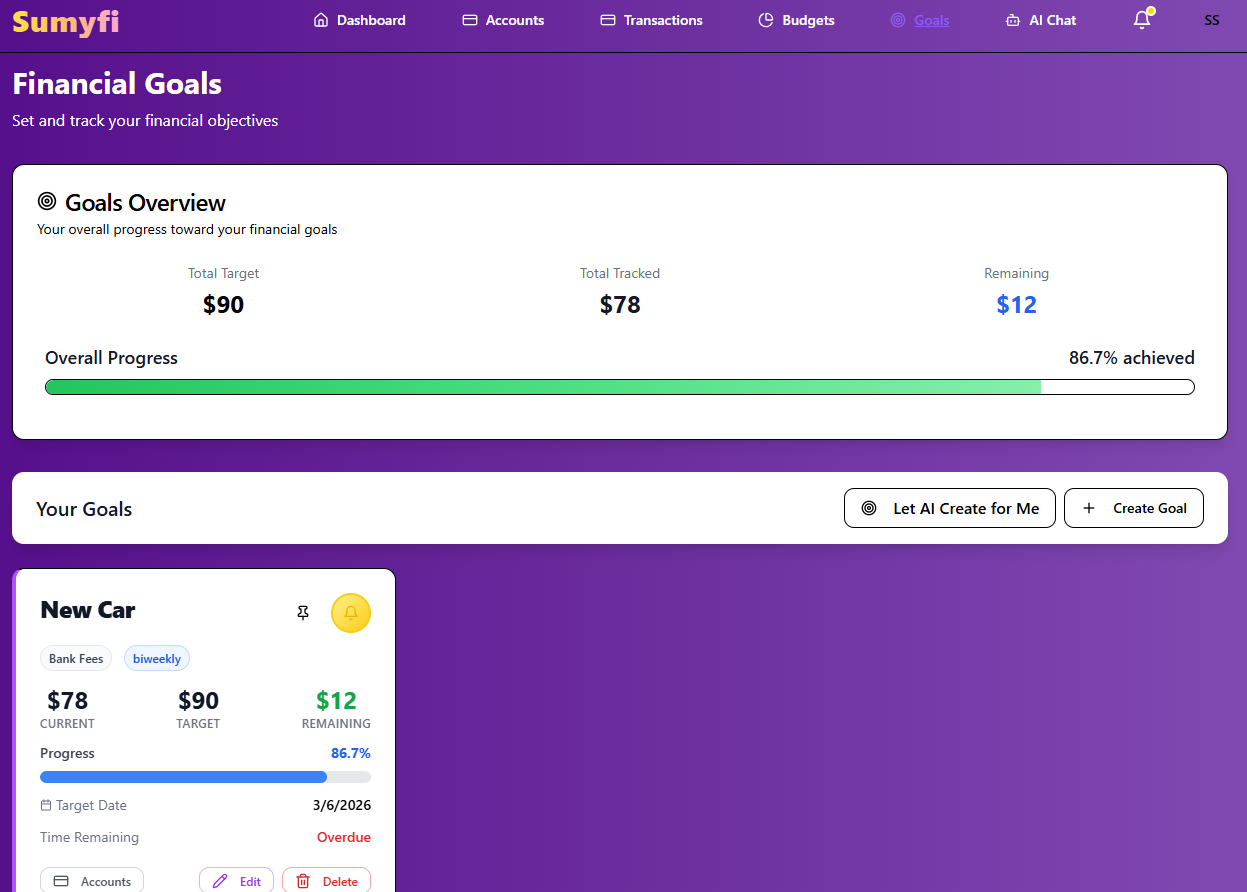
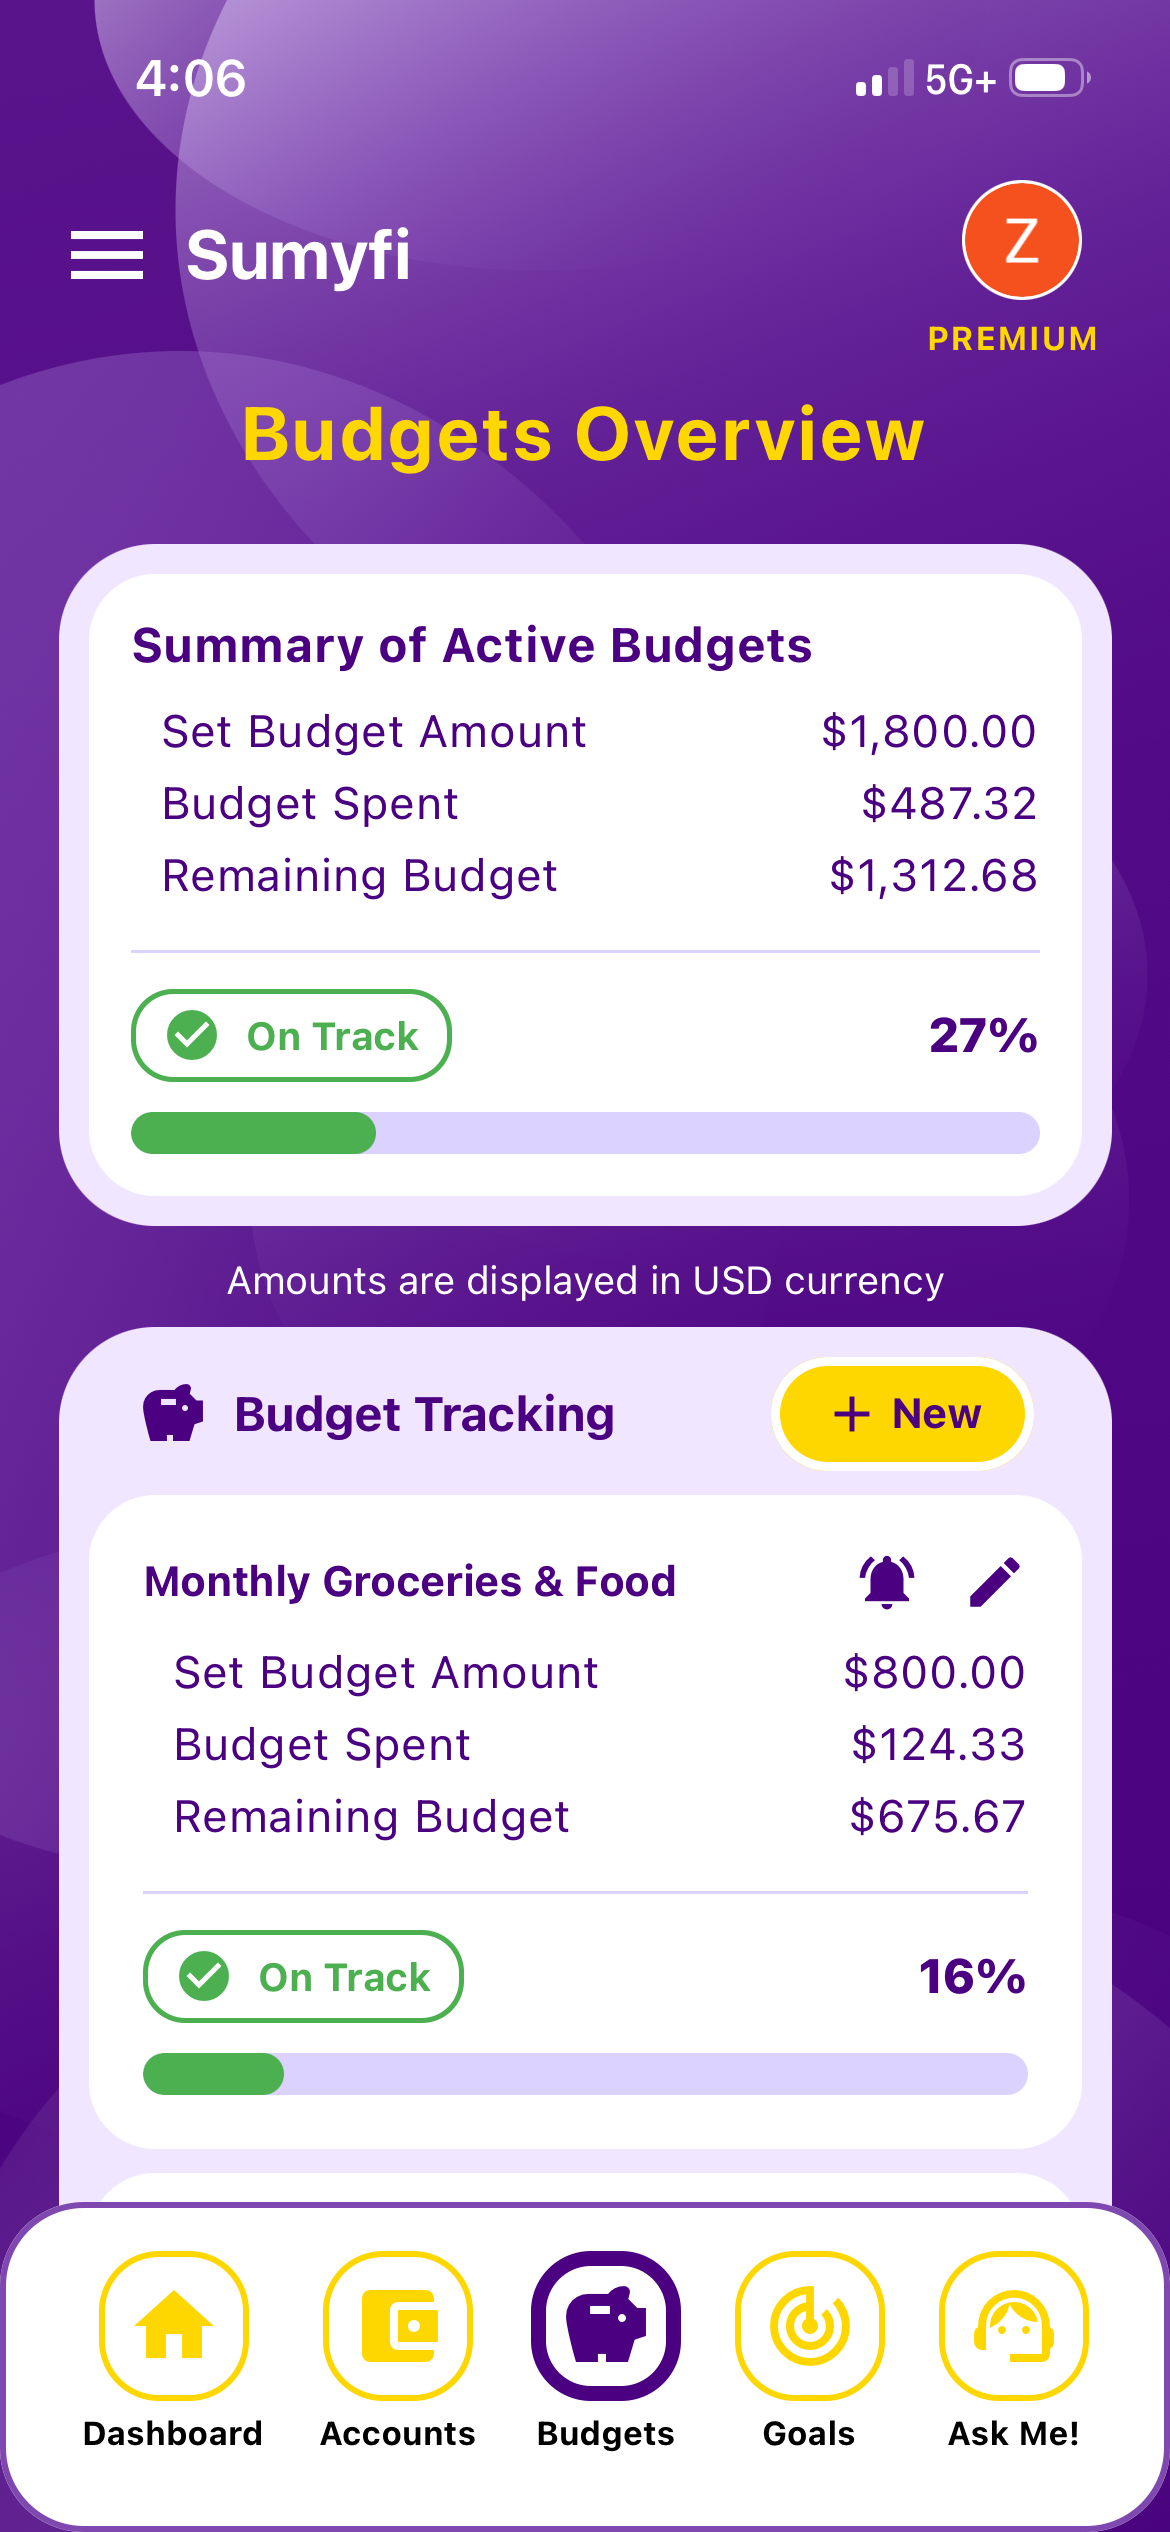
Sumyfi was built for people who want their money in one place without a lot of upkeep. The dashboard keeps budgets, accounts, goals, net worth and recurring charges together, so you're not opening four screens to answer one question. The subscriptions view pulls out recurring charges, shows what's due in the next 10 days, and lets you add bills it didn't catch. That 10-day list is most of what you need for the safe-to-spend math above.
The free plan covers budgets, goals and transaction categorization with accounts you add manually, plus CSV or Excel import if you'd rather download statements from your bank than type anything. Premium, which has a 7-day free trial, adds automatic bank sync through Plaid in read-only mode, custom spending alerts, and an AI assistant you can just type to. Instead of hunting through settings, you can say something like 'lower my dining budget to $250' and it makes the change.
To be straight about the limits: Sumyfi doesn't show a single safe-to-spend number on its own, so you'll still do that subtraction yourself, though the upcoming charges are right there. It won't move money, pay bills for you or cancel subscriptions. Autopay and savings transfers still get set up at your bank. And automatic sync is a paid feature, so on the free plan you're updating balances yourself.
Pros
- Budgets, bills, goals and balances on one dashboard
- Upcoming recurring charges for the next 10 days
- Plain-language changes through the AI assistant on Premium
Cons
- No built-in safe-to-spend figure
- Automatic bank sync requires Premium
A setup you can finish in one evening
Don't plan a weekend overhaul. You'll put it off. Here's a version that fits in about two hours, and you never have to do most of it again.
- Write down every bill you know about with its amount and due date. Then scroll through the last two months of your chequing and credit card statements and add anything you forgot.
- Turn on autopay for every bill that allows it, and at least the minimum for every credit card.
- Call or log in to move any bill that lands before payday to a date just after it.
- Open a savings account at a different bank and schedule a transfer for the day after payday. Pick an amount that feels almost too small, like $25. You can raise it later.
- Set up whatever app or note you'll use to see upcoming bills, and do the safe-to-spend math once.
- Pick one day a week, Sunday morning works for a lot of people, to spend five minutes redoing that math. That's the only ongoing task.
If a week goes sideways, don't try to reconstruct what happened. Check today's balance, subtract what's due before payday, and carry on from there. The system only has to be good enough that most weeks run on autopilot.