How to Build Net Worth in Your 20s Without Overcomplicating the Plan
Build a money routine for people in their 20s that keeps net worth visible without turning every review into manual maintenance.
Readers searching how to build net worth in your 20s are usually not asking for the definition of net worth again. They want to know how savings habits, debt decisions, income growth, and spending control work together early in adult financial life.
That is why this page should stay distinct from the formula page. The value here is the 20s-specific habit and system question, not the basic math of assets minus liabilities.
If you already understand the definition and want the 20s-specific playbook, this is the page to use.
At a glance
- Habits before optimization
- Debt, savings, and progress together
Start organizing your personal finances for $0 with bank-grade 256-bit encryption and no upfront commitment.
At a glance
Built for people in their 20s
Lead with the money pressures that shape this audience before the product comparison begins.
Budgeting for real life
Keep net worth visible without building a custom spreadsheet before the routine even starts.
Shifting cash-flow awareness
Use one dashboard that works on desktop and mobile so weekly reviews stay realistic when pay or expenses move around.
Consistency without burnout
Keep goals tied to the same balances, recurring costs, and spending patterns that affect progress.
Life-stage intent
People in their 20s usually need a sequence for building wealth before they need another dashboard
This guide usually comes from someone trying to build momentum early: reducing expensive debt, creating the first emergency cushion, starting investing habits, and understanding whether cash flow is supporting that direction. The page should therefore read like a practical roadmap rather than a generic app roundup.
A dashboard can help later, but the first value here comes from order. People in their 20s want to know what to prioritize first, which habits compound fastest, and how to avoid making money management feel like a second job.
Cluster separation
Overview
The net worth cluster gets weaker when a life-stage guide starts sounding like a tracker page. This guide is strongest when it stays focused on early wealth-building decisions, including debt control, savings rate improvement, and keeping the money picture understandable during a low-margin stage of life.
That gives the page a clear role: teach the 20s playbook here, keep tracker comparisons on tracker pages, and leave fast math to the calculator and formula pages.
Habit workflow
A habit-building workflow
The goal is to give people in their 20s a routine that survives uneven weeks, not just a good first impression.
Start with the live dashboard
Open balances, spending patterns, and recurring obligations for how to build net worth in your 20s from one place instead of piecing the month together mentally.
Adjust the pressure points
Use categories, goals, and reminders to spot the spending or bill pattern that deserves attention first for how to build net worth in your 20s.
Keep the routine light
Come back from desktop or mobile for short check-ins so the habit survives busy weeks.
Product screenshots
See the product behind the copy
Screenshots shown: Dashboard, Accounts, Goals.
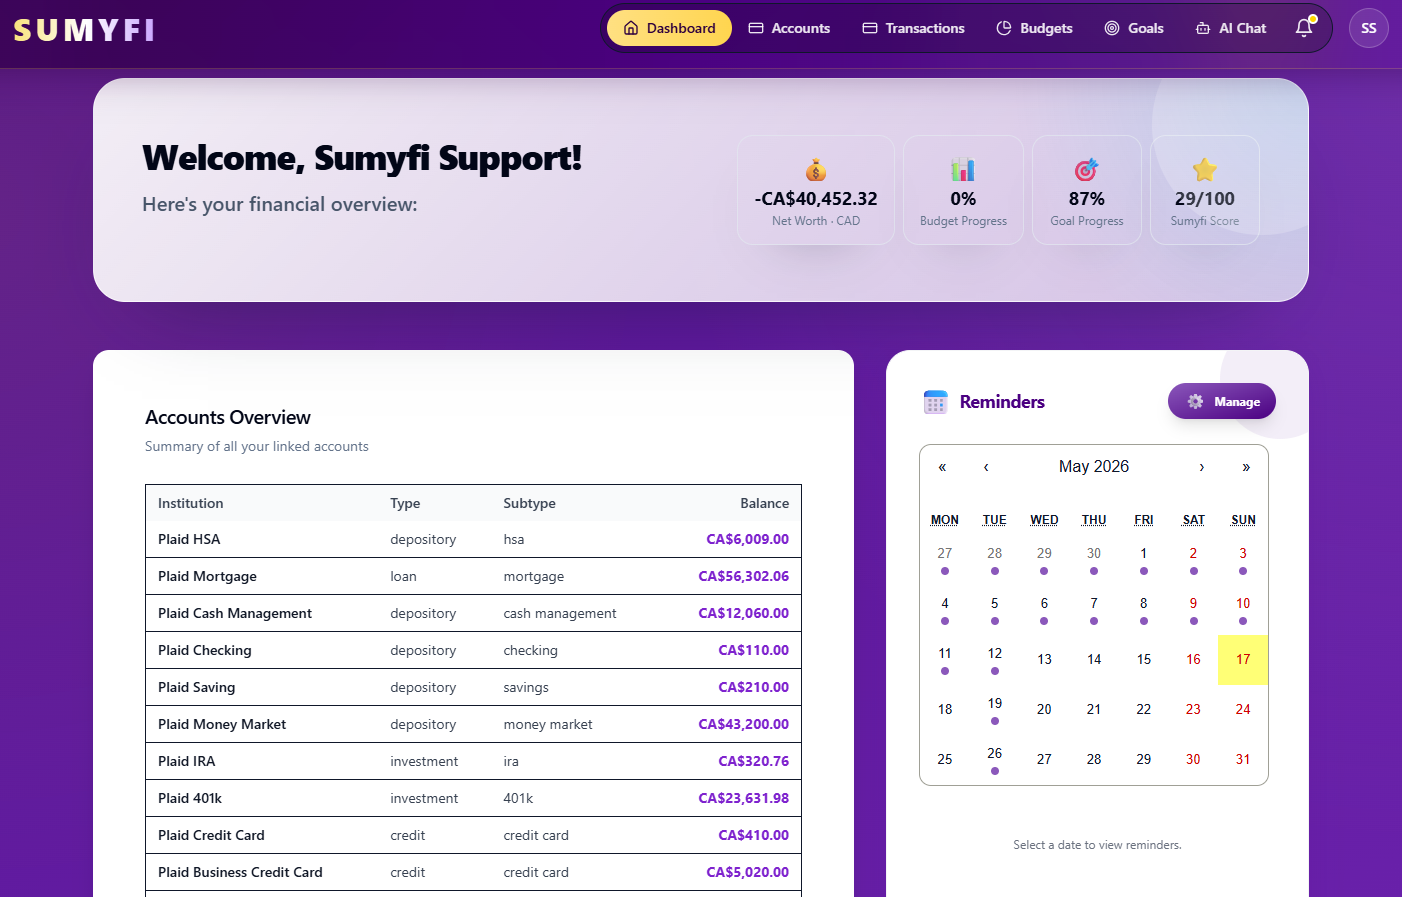
Dashboard shows balances, assets, and debts in one overview.
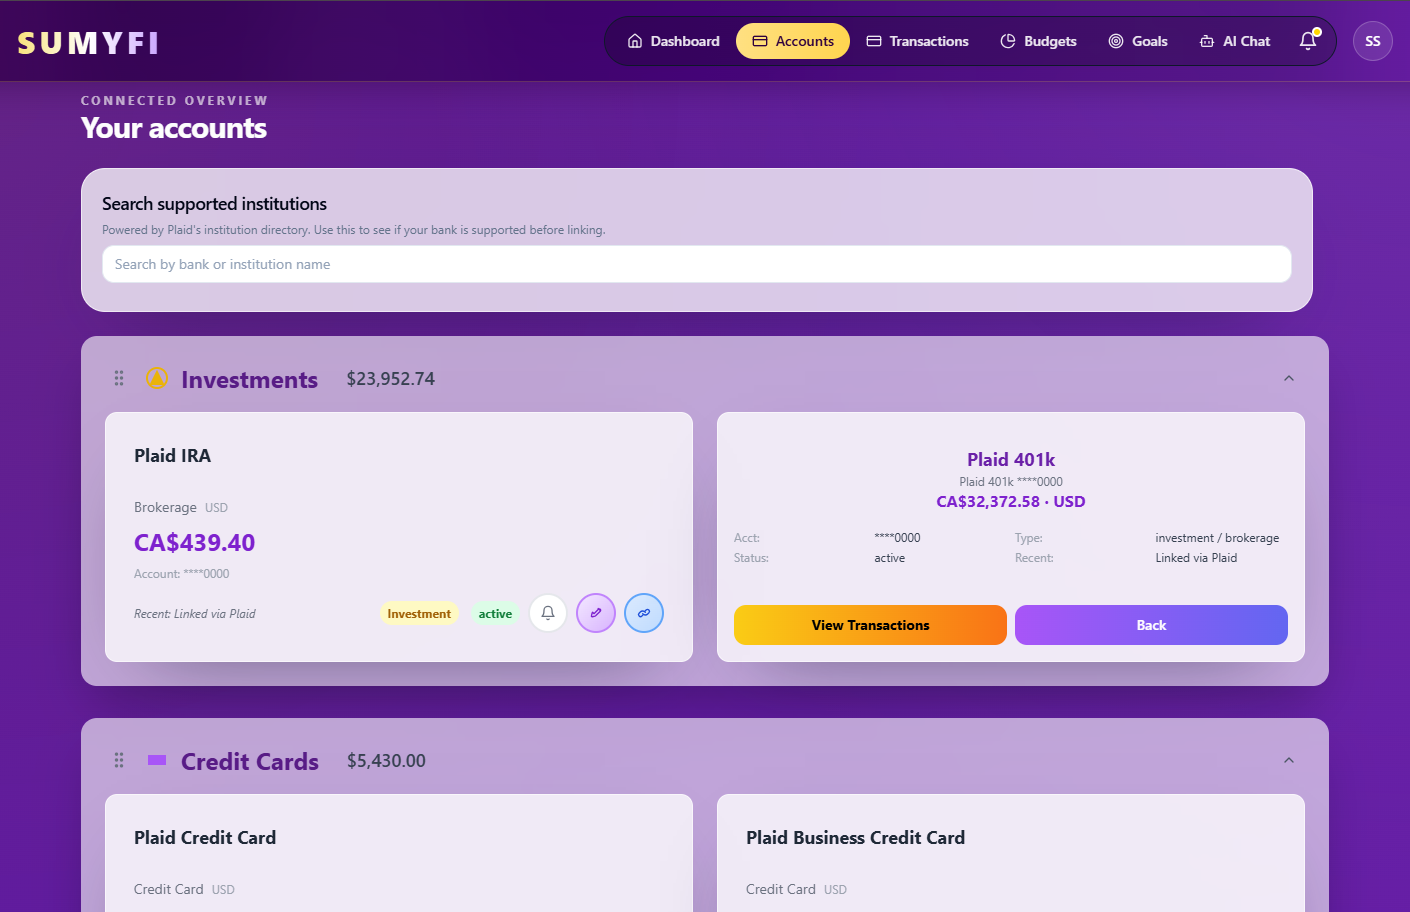
Accounts shows assets, debts, and balances in one account view.
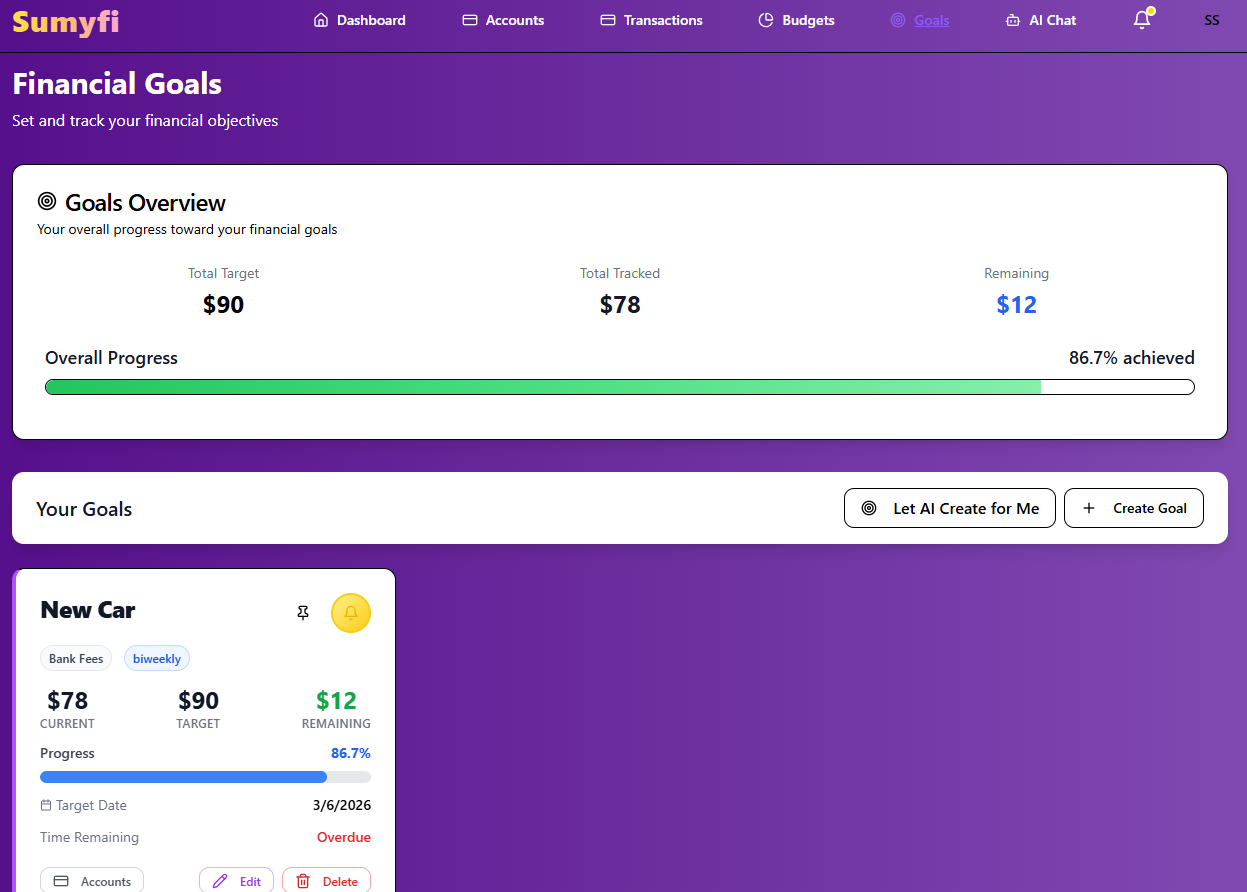
Goals shows progress targets alongside the broader balance picture.
Comparison table
Sumyfi vs spreadsheets and rigid legacy apps for people in their 20s
Compare how each option handles changing income, shared costs, and the short weekly reviews that people in their 20s actually need.
| Decision area | Sumyfi | Spreadsheets | Rigid legacy apps |
|---|---|---|---|
| Handling changing income | Balances and categories update in one dashboard | Manual updates every time pay changes | Often assumes a steadier monthly pattern |
| Shared-cost visibility | Bills, categories, and goals stay close together | Easy to split into separate tabs or versions | Often less flexible for informal shared routines |
| Weekly habit fit | Built for short desktop or mobile check-ins | Useful if you enjoy maintenance work | Can feel heavier once life gets busy |
| Progress tracking | Goals and cash flow stay in the same review loop | Progress depends on manual upkeep | Progress can feel more rigid than motivating |
Recommended next reads
Read 5 related articles next
Related reading for the next question.
FAQs
Frequently asked questions about how to build net worth in your 20s
Is Sumyfi a good fit for people in their 20s?
Yes. people in their 20s usually benefit when balances, bills, and categories stay in one place rather than scattered across separate tools.
Do I need prior budgeting experience?
No. people in their 20s do not need advanced budgeting knowledge to start with short review sessions and visible pressure points.
How does the product help with changing income or category drift?
Short reviews help catch category drift early, which matters when pay timing, shared costs, or daily spending patterns are not perfectly predictable.
Can I start for free before choosing a paid plan?
Yes. The goal is to prove the routine works in real life before pricing becomes part of the decision.