Automatic expense tracking gets you most of the way. The rest is Costco runs, Amazon orders, PayPal charges and refunds that land in the wrong category. Here's how auto-categorization works, how to correct it, and a 10-minute weekly review that keeps it accurate.
If you've ever tried to track every purchase in a notes app or spreadsheet, you know how it ends. It works for nine days, then you miss a weekend, then you're three weeks behind and you quit. That's usually when people go looking for a way to track my expenses automatically: let your bank and card data do the recording, and spend your time on decisions instead of data entry.
Automatic tracking really does remove most of the work. But it isn't magic, and it's worth knowing how it categorizes your spending, which purchases it reliably gets wrong, and how little effort it takes to keep it honest. That's what This guide covers, along with the short weekly routine that makes the whole thing worth having.
What happens between tapping your card and seeing a category
When you buy a coffee, your card statement doesn't say 'Coffee, $5.75.' It says something like 'SQ *BLUE BOTTLE 0423 OAKLAND CA' or 'TST* JOES PIZZA'. Those prefixes come from the payment processor (Square and Toast in these cases), and the rest is whatever the merchant typed into their account setup years ago.
Automatic tracking cleans that up in a few steps. The transaction comes over from your bank through a data connection, usually a day or two after it posts. The descriptor gets matched to a merchant name. Then a category is assigned, based on what kind of business the merchant is and, in some apps, what you've done with that merchant before.
For most single-purpose merchants this works very well. A Shell station is fuel. Netflix is entertainment. Your dentist is health. In a typical month, the large majority of transactions land in a sensible category without you doing anything.
The purchases auto-categorization usually gets wrong
The errors aren't random. They cluster around a few kinds of transactions, so once you know them, you know where to look.
Big-box stores
A $186 Costco, Walmart or Target run might be groceries, a phone charger and a birthday gift. It all lands in one category.
Amazon
'AMZN Mktp' tells the app nothing about whether you bought dog food or a monitor.
Payment middlemen
PayPal, Venmo and Apple charges hide the real merchant behind the payment company's name.
Gas stations
A $14 convenience-store snack run looks exactly like a fill-up.
Refunds
A $60 return can show up as income instead of reducing last month's shopping.
Transfers
Paying your credit card or moving money to savings can be counted as spending if the app doesn't recognize both sides.
Pending charges
A $1 hotel or gas hold that later becomes $52.40, or a restaurant bill that grows when the tip posts.
Rules, corrections and when to leave it alone
Many apps let you create rules, such as 'anything from Costco goes to Groceries' or 'anything containing NETFLIX goes to Subscriptions'. Where they're available, rules are worth setting up for your five or six most frequent merchants. You fix it once and never think about it again.
For everything else, you're correcting transactions one at a time, and the key is not correcting too much. A useful rule of thumb: fix anything over $50, anything in a category you're actively trying to cut back on, and anything that's a transfer counted as spending. Leave the $4 parking charge in 'Shopping' if that's where it landed. It won't change a single decision you make.
For big-box runs, decide on a convention instead of splitting every receipt. One option is to call Costco 'Groceries' by default and only recategorize when a single trip includes something big, like a $400 TV. Another is to make a combined 'Groceries and household' category so the question disappears.
Pick categories automation can actually handle
People often create categories based on intent, like 'Treats', 'Self-care' or 'Things for the kids'. Automation can't read intent. It only knows merchants. If your categories don't line up with how merchants are classified, you'll be correcting everything forever.
Fewer, broader categories work better. Something like 12 to 15 is plenty for most households: housing, utilities, groceries, dining out, transportation, insurance, health, subscriptions, shopping, kids, travel, gifts and personal care, plus transfers and income. You can always look at the merchant list inside a category if you want detail.
A 10-minute weekly review to keep it accurate
Automatic tracking still needs a human once a week. Not for long. Pick a regular time, like Sunday morning with coffee, and do this:
- Look at the transactions since last week, about 2 minutes. Scan for anything you don't recognize. That's your fraud check too.
- Fix the miscategorized ones, about 3 minutes. Use the list above: big-box stores, Amazon, PayPal, refunds and transfers.
- Check two or three categories against budget, about 2 minutes. If groceries are at $480 of $650 with 12 days left, you know where you stand.
- Look at what's due this week, about 2 minutes. Rent, card payments, a renewal coming up.
- Make one decision, about 1 minute. Move $40 from dining out to groceries, cancel a subscription, or do nothing because things are fine.
That's it. If it regularly takes longer than 15 minutes, you have too many categories or you're fixing too many small transactions.
What automatic tracking can't see
A few kinds of spending never get categorized properly because the data simply isn't there.
Cash is the obvious one. The app sees a $200 ATM withdrawal and nothing after it. Either treat cash withdrawals as their own category, or jot down the big cash purchases by hand.
Payments to people are the other. Zelle in the US or an Interac e-Transfer in Canada shows a name and an amount, not what it was for. Rent, a babysitter and your share of a cottage weekend all look the same. Label recurring ones once, and add a quick note to anything over $100.
Shared costs and reimbursements are trickier. If you pay $240 for a group dinner and three friends send you $60 each, the app sees $240 spent and $180 of income. Recategorize the incoming money as a reduction of dining out, or your dining number will look terrible and your income will look inflated. The same goes for work expenses your employer pays back.
Tracking expenses automatically with Sumyfi
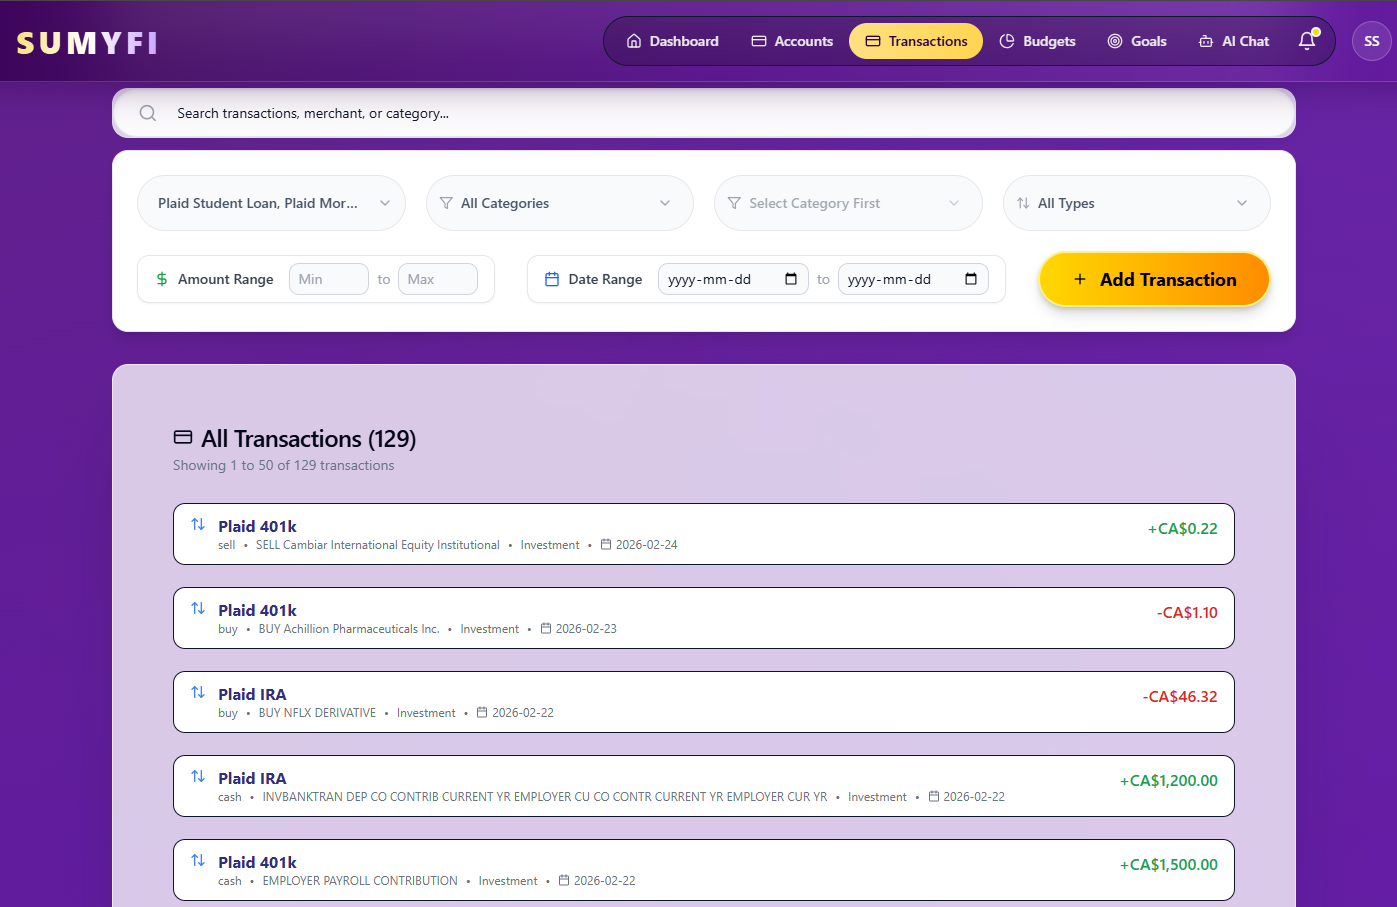
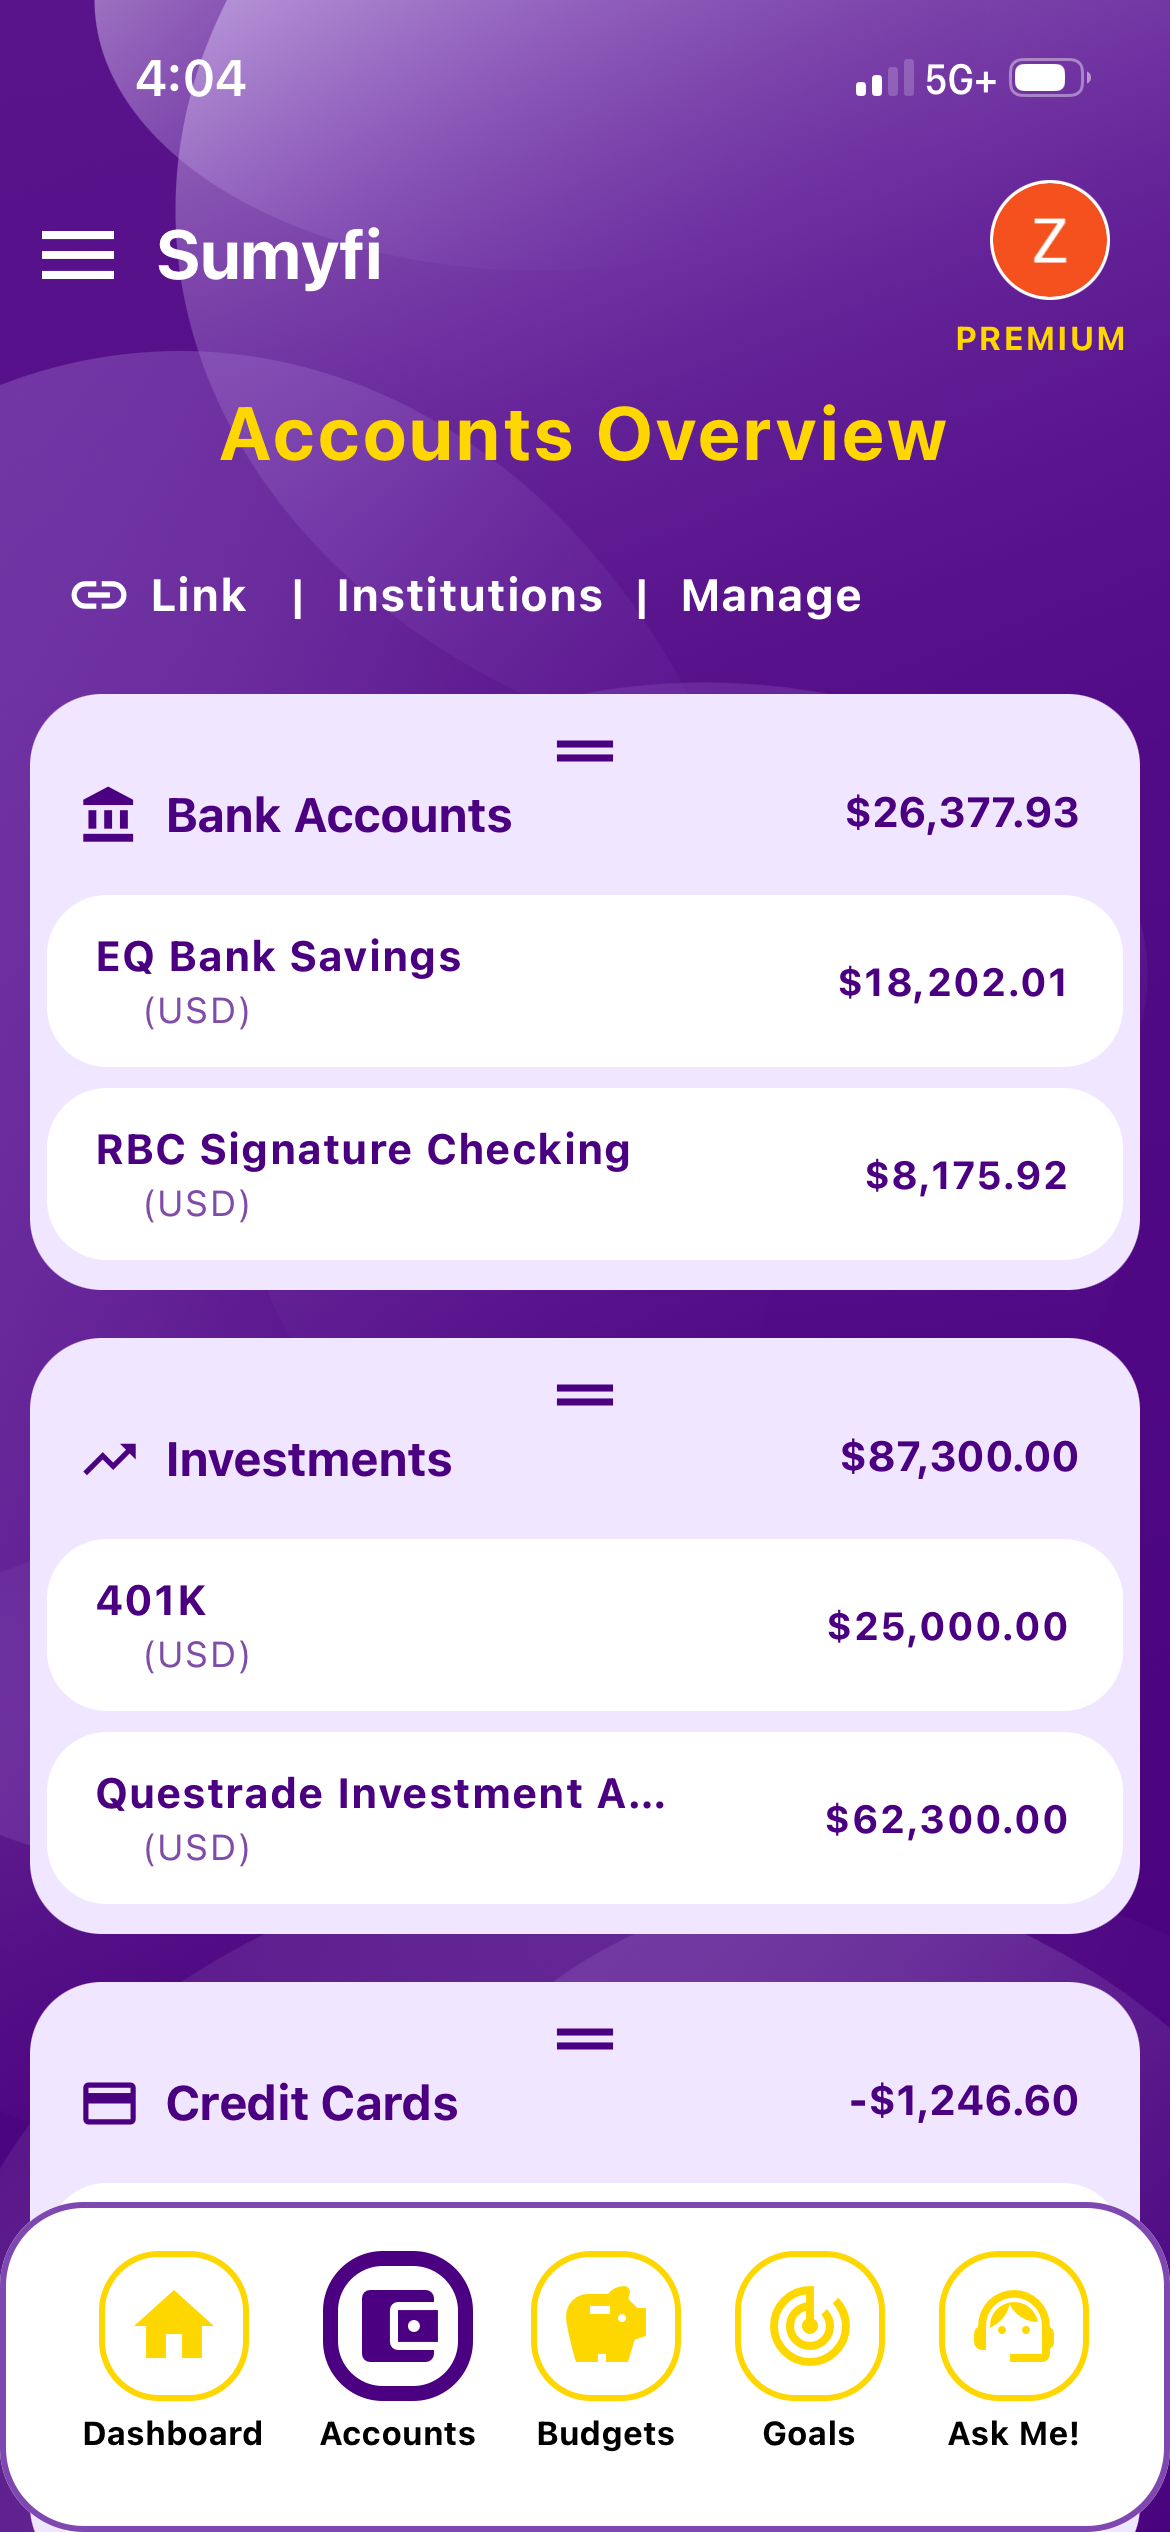
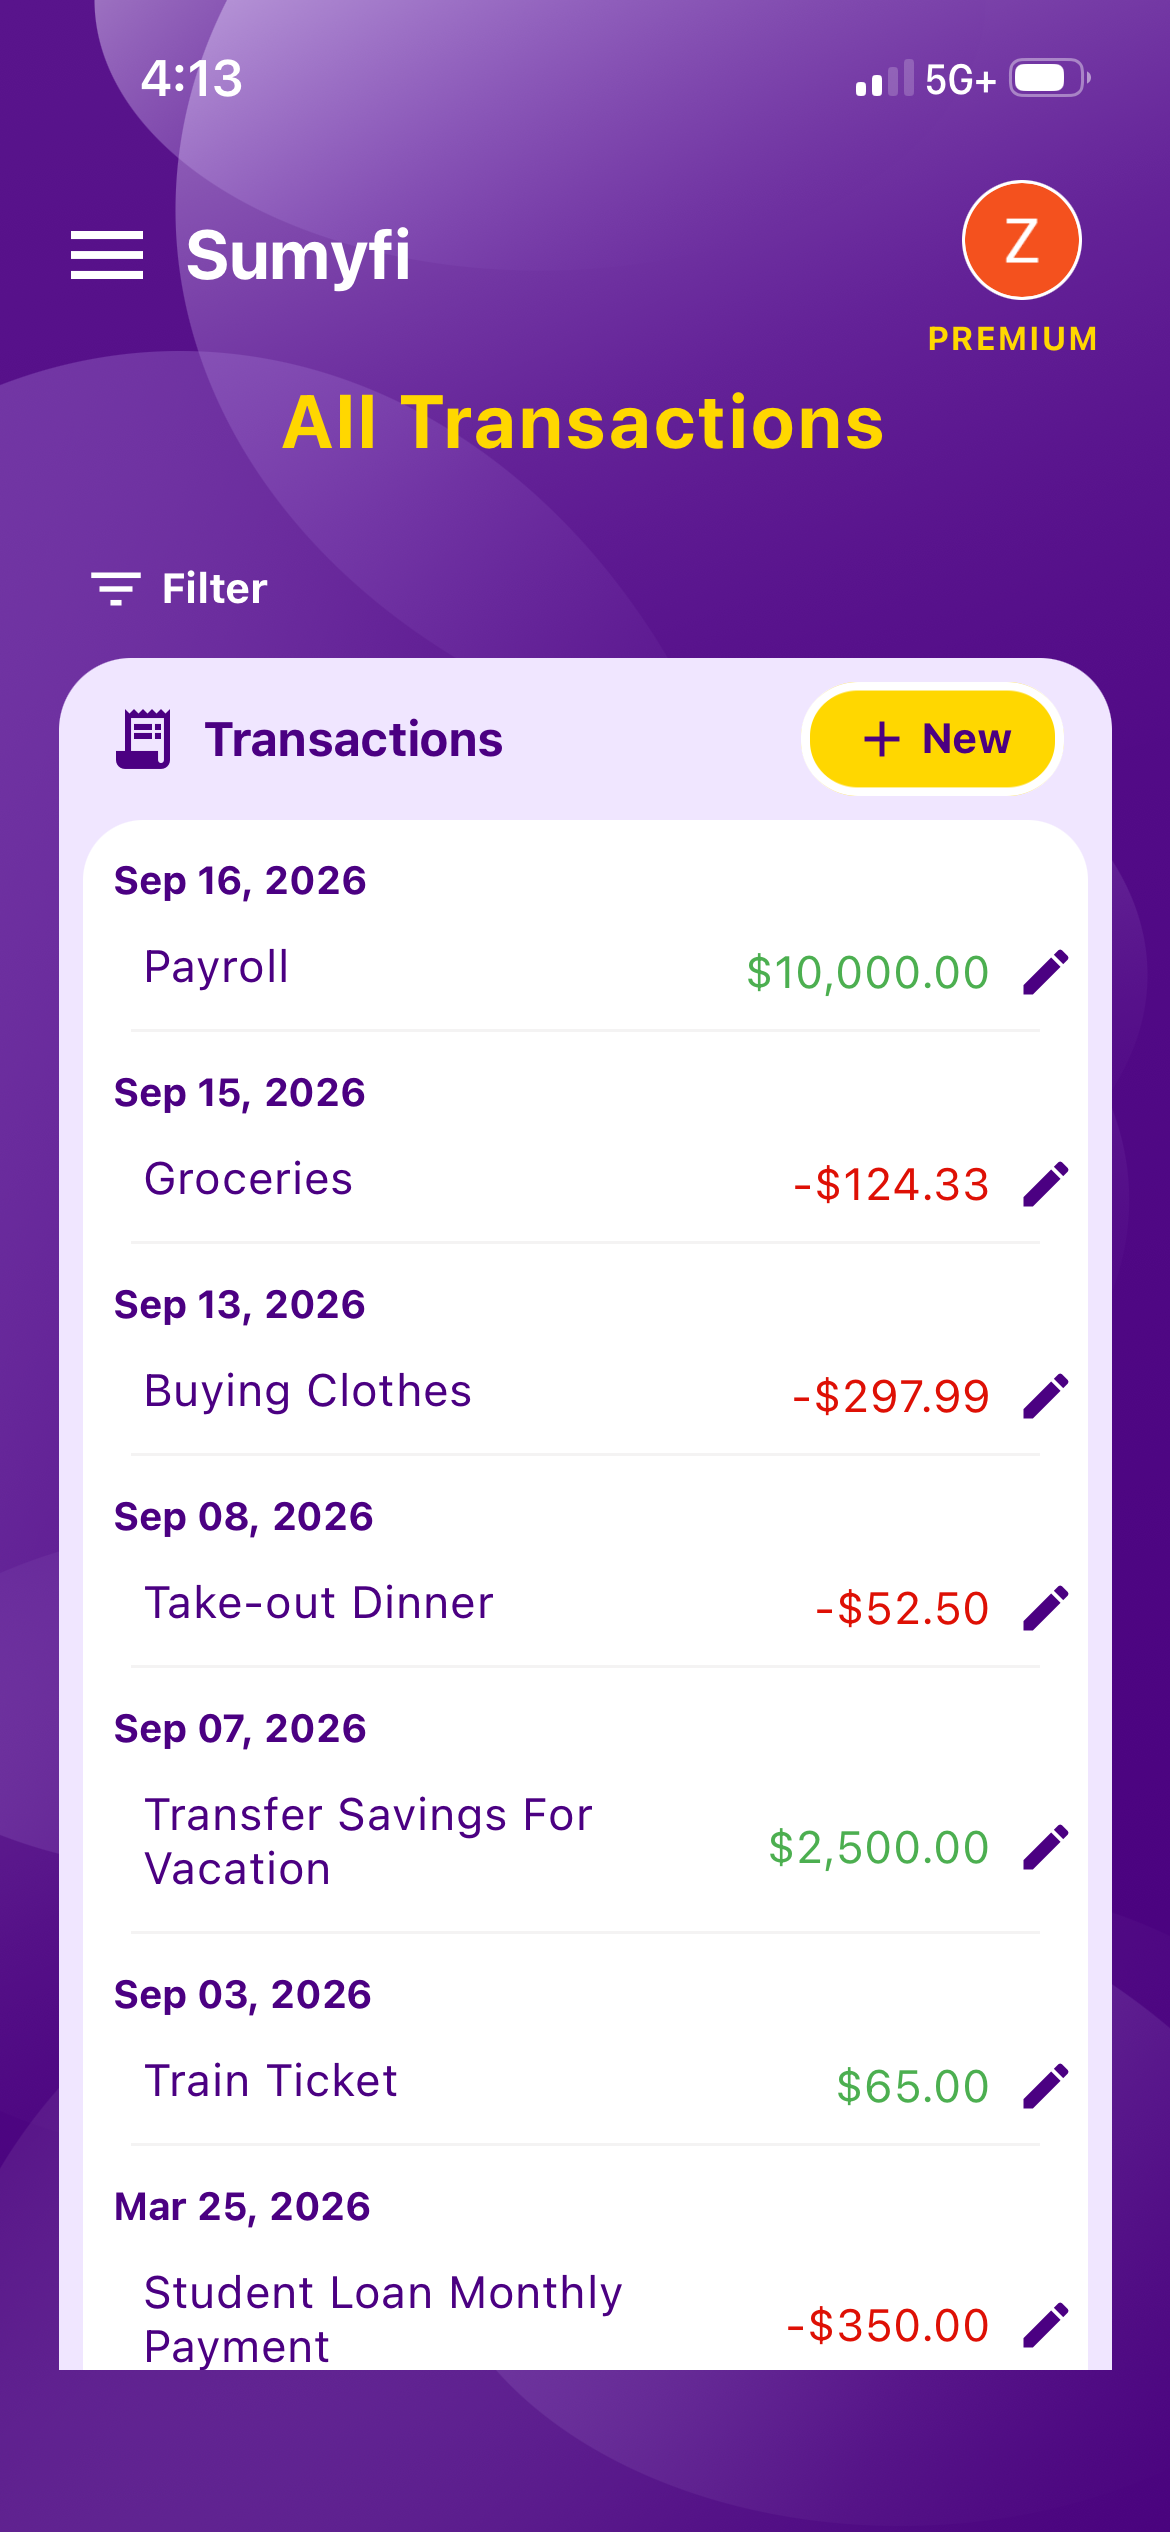
Sumyfi categorizes transactions on both the free and Premium plans. On the free plan, you can import transactions from a CSV or Excel file you download from your bank, which is a decent middle ground if you don't want to link accounts. Premium adds automatic bank sync through Plaid, read-only, with US and Canadian institutions and coverage depending on the bank.
Categorized spending feeds your budgets, so you see groceries at 74% of budget without adding anything up. The subscriptions view picks out recurring charges from the same transactions and shows what's due in the next 10 days. Premium also includes custom spending alerts and an AI assistant you can ask plain questions, such as how much you spent at Costco last month or which category grew the most since spring.
Automatic sync and the AI assistant come with a 7-day free trial. That's enough for one full weekly review on your own data, which is the best way to tell whether automatic tracking suits you.