Tracking tells you what happened. A plan tells you what to do next: how big an emergency fund to build, which debt to pay first and when retirement saving starts. Here's a beginner's order of operations and what a planning app should help with.
A lot of people already know roughly where their money goes. What they don't have is an answer to the next question: given what's left each month, what should it be doing? Should the extra $400 go to the credit card, an emergency fund or a TFSA? How much is enough in savings? When do you start thinking about retirement? The best financial planning app for beginners helps you answer those questions in order and keeps the answers visible, instead of leaving you with a nice chart of last month's spending.
This guide covers what a financial plan actually is, a sensible order of priorities for a first plan, how to size an emergency fund, how to choose which debt to pay first, the retirement accounts worth knowing about, and what a planning app should do for you. Sumyfi comes up near the end as one option.
What a financial plan is, and how it differs from a budget
A budget decides where this month's money goes. A plan decides where the next few years of money goes. In practice, a beginner's plan is just a short, ranked list of goals, each with a target amount, a date, and a monthly amount assigned to it.
Here's what one might look like for someone taking home $4,000 a month with about $600 left after bills and everyday spending: $300 a month to a $3,200 credit card balance until it's gone, $200 a month to an emergency fund, and $100 a month to a TFSA. When the card is paid off, its $300 moves down the list. That's the whole plan. It fits on a sticky note, and it's far more useful than a vague intention to save more.
The hard part isn't writing it down. It's deciding the order, which is what the next section is about.
A sensible order for a beginner's financial plan
There's no single correct order, and reasonable people disagree on the details. But this sequence works for most beginners because each step protects the one after it:
- Build a small starter cushion, around $1,000 or one month of essential expenses. This keeps a surprise car repair from landing on a credit card.
- Contribute enough to get any employer match on a workplace retirement plan or group RRSP. Matched money is the best return you'll find anywhere.
- Pay off high-interest debt, mostly credit cards and anything charging well into double digits.
- Grow the emergency fund to three to six months of essential expenses.
- Save for retirement steadily through a TFSA, RRSP or FHSA in Canada, or a 401(k) or Roth IRA in the US.
- Fund medium-term goals like a car, a wedding, travel or a down payment.
Some people pay down debt before capturing the match, or build the full emergency fund before touching debt. Both are defensible. What matters most is having an order at all, so every extra dollar has somewhere obvious to go.
How big your emergency fund should actually be
The usual guidance is three to six months of essential expenses. Essentials means what you'd still have to pay if you lost your income tomorrow: rent, groceries, utilities, phone, insurance, transit and minimum debt payments. Not dinners out or streaming.
Say that comes to rent $1,600, groceries $450, utilities and phone $200, insurance $150, transit $150, and $200 in minimum debt payments. That's $2,750 a month, so three months is $8,250 and six months is $16,500. If you have a stable salaried job and a partner with income, the lower end is reasonable. If you're freelance, paid on commission or the only earner in the house, aim higher.
Keep it in a high-interest savings account that's separate from chequing, so it's easy to reach in a real emergency and slightly annoying to reach otherwise. The emergency fund calculator on the Sumyfi site does this arithmetic for you if you'd rather not.
Which debt to pay off first
Pay the minimum on everything, then put every extra dollar on one debt at a time. The question is which one. There are two common approaches:
Take an example: a $3,200 credit card at 20.99%, a $1,500 personal loan at 11% and a $9,000 car loan at 7.5%. The avalanche method pays the credit card first because it has the highest rate. The snowball method starts with the $1,500 personal loan because it's the smallest, which gets one debt fully gone sooner. Avalanche costs less in total interest. Snowball is easier to stick with for some people, and a plan you stick with beats a slightly cheaper plan you abandon. Either way, the car loan comes last. Debt at a low rate, like a car loan or a student loan with little or no interest, usually doesn't need to be rushed ahead of retirement saving.
The debt payoff calculator on the Sumyfi site lets you try both methods with your own balances and see the payoff dates side by side.
- Avalanche: highest interest rate first, which saves the most money overall
- Snowball: smallest balance first, which clears whole debts faster and keeps motivation up
Retirement basics without the jargon
Retirement feels far away, which is exactly why starting early helps. Money invested in your twenties or early thirties has decades to grow, so small amounts now can matter more than larger amounts later. You don't need to have it all figured out. You need an account and a monthly contribution, even a modest one.
In Canada, a TFSA lets investments grow tax-free and you can withdraw any time. An RRSP gives you a tax deduction now, based on 18% of last year's earned income up to an annual maximum, and you pay tax when you withdraw in retirement, which tends to suit people in higher tax brackets. An FHSA is for first-time home buyers and combines a deduction going in with tax-free withdrawals for a qualifying home purchase. The TFSA vs RRSP vs FHSA calculator on the Sumyfi site compares them with your numbers.
In the US, a 401(k) is the workplace plan, often with an employer match, and a Roth IRA takes after-tax money that can come out tax-free in retirement if the rules are met.
Which investments go inside those accounts is a separate decision, and it depends on your timeline and comfort with risk. A planning app can tell you how much you're putting in and if you're on pace. It shouldn't be choosing investments for you, and if you want that kind of help, a fee-only financial planner is worth considering.
What a financial planning app for beginners should actually do
Most budgeting apps are built for tracking. A planning app needs a few more things: goals with target amounts and dates, a clear view of how each goal is tracking against its date, debts and savings on the same screen so you can see net worth move, and an easy way to change the plan when life changes. A raise, a move or a new car payment should take five minutes to reflect, not a full rebuild.
Other tools cover pieces of this. Robo-advisors like Wealthsimple handle the investing side well but don't see your everyday spending. Spreadsheets can model anything if you're willing to maintain them. Paid apps like Monarch Money and YNAB have goal features of their own, with different styles.
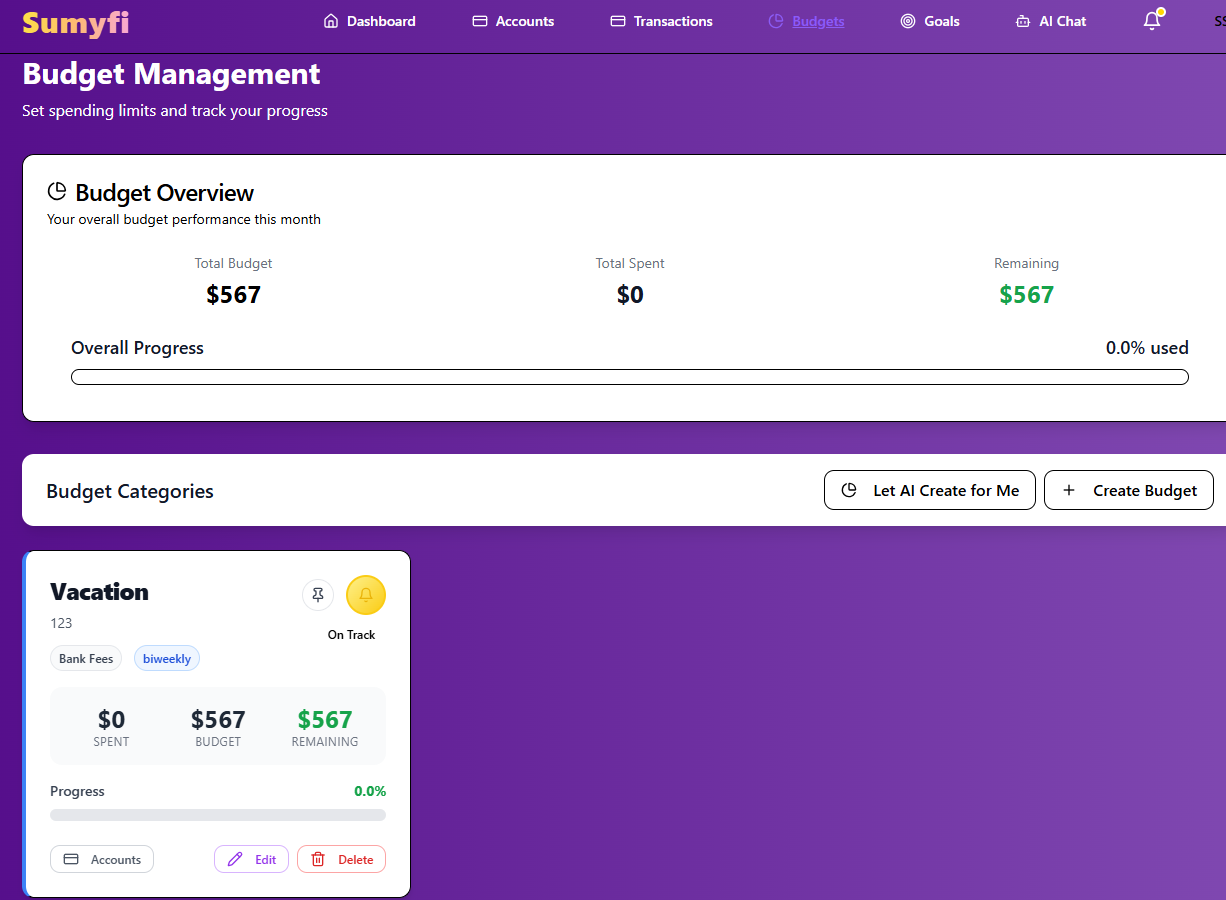
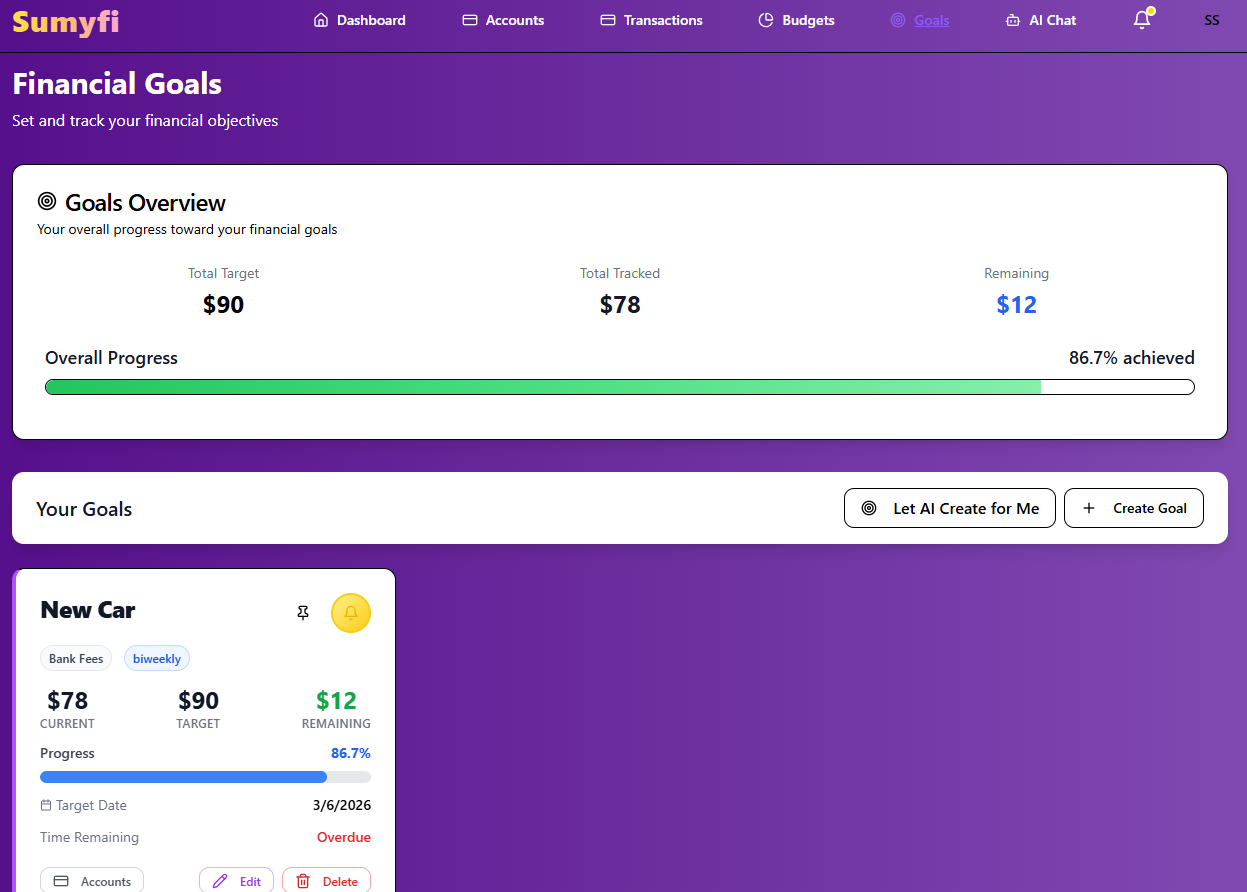
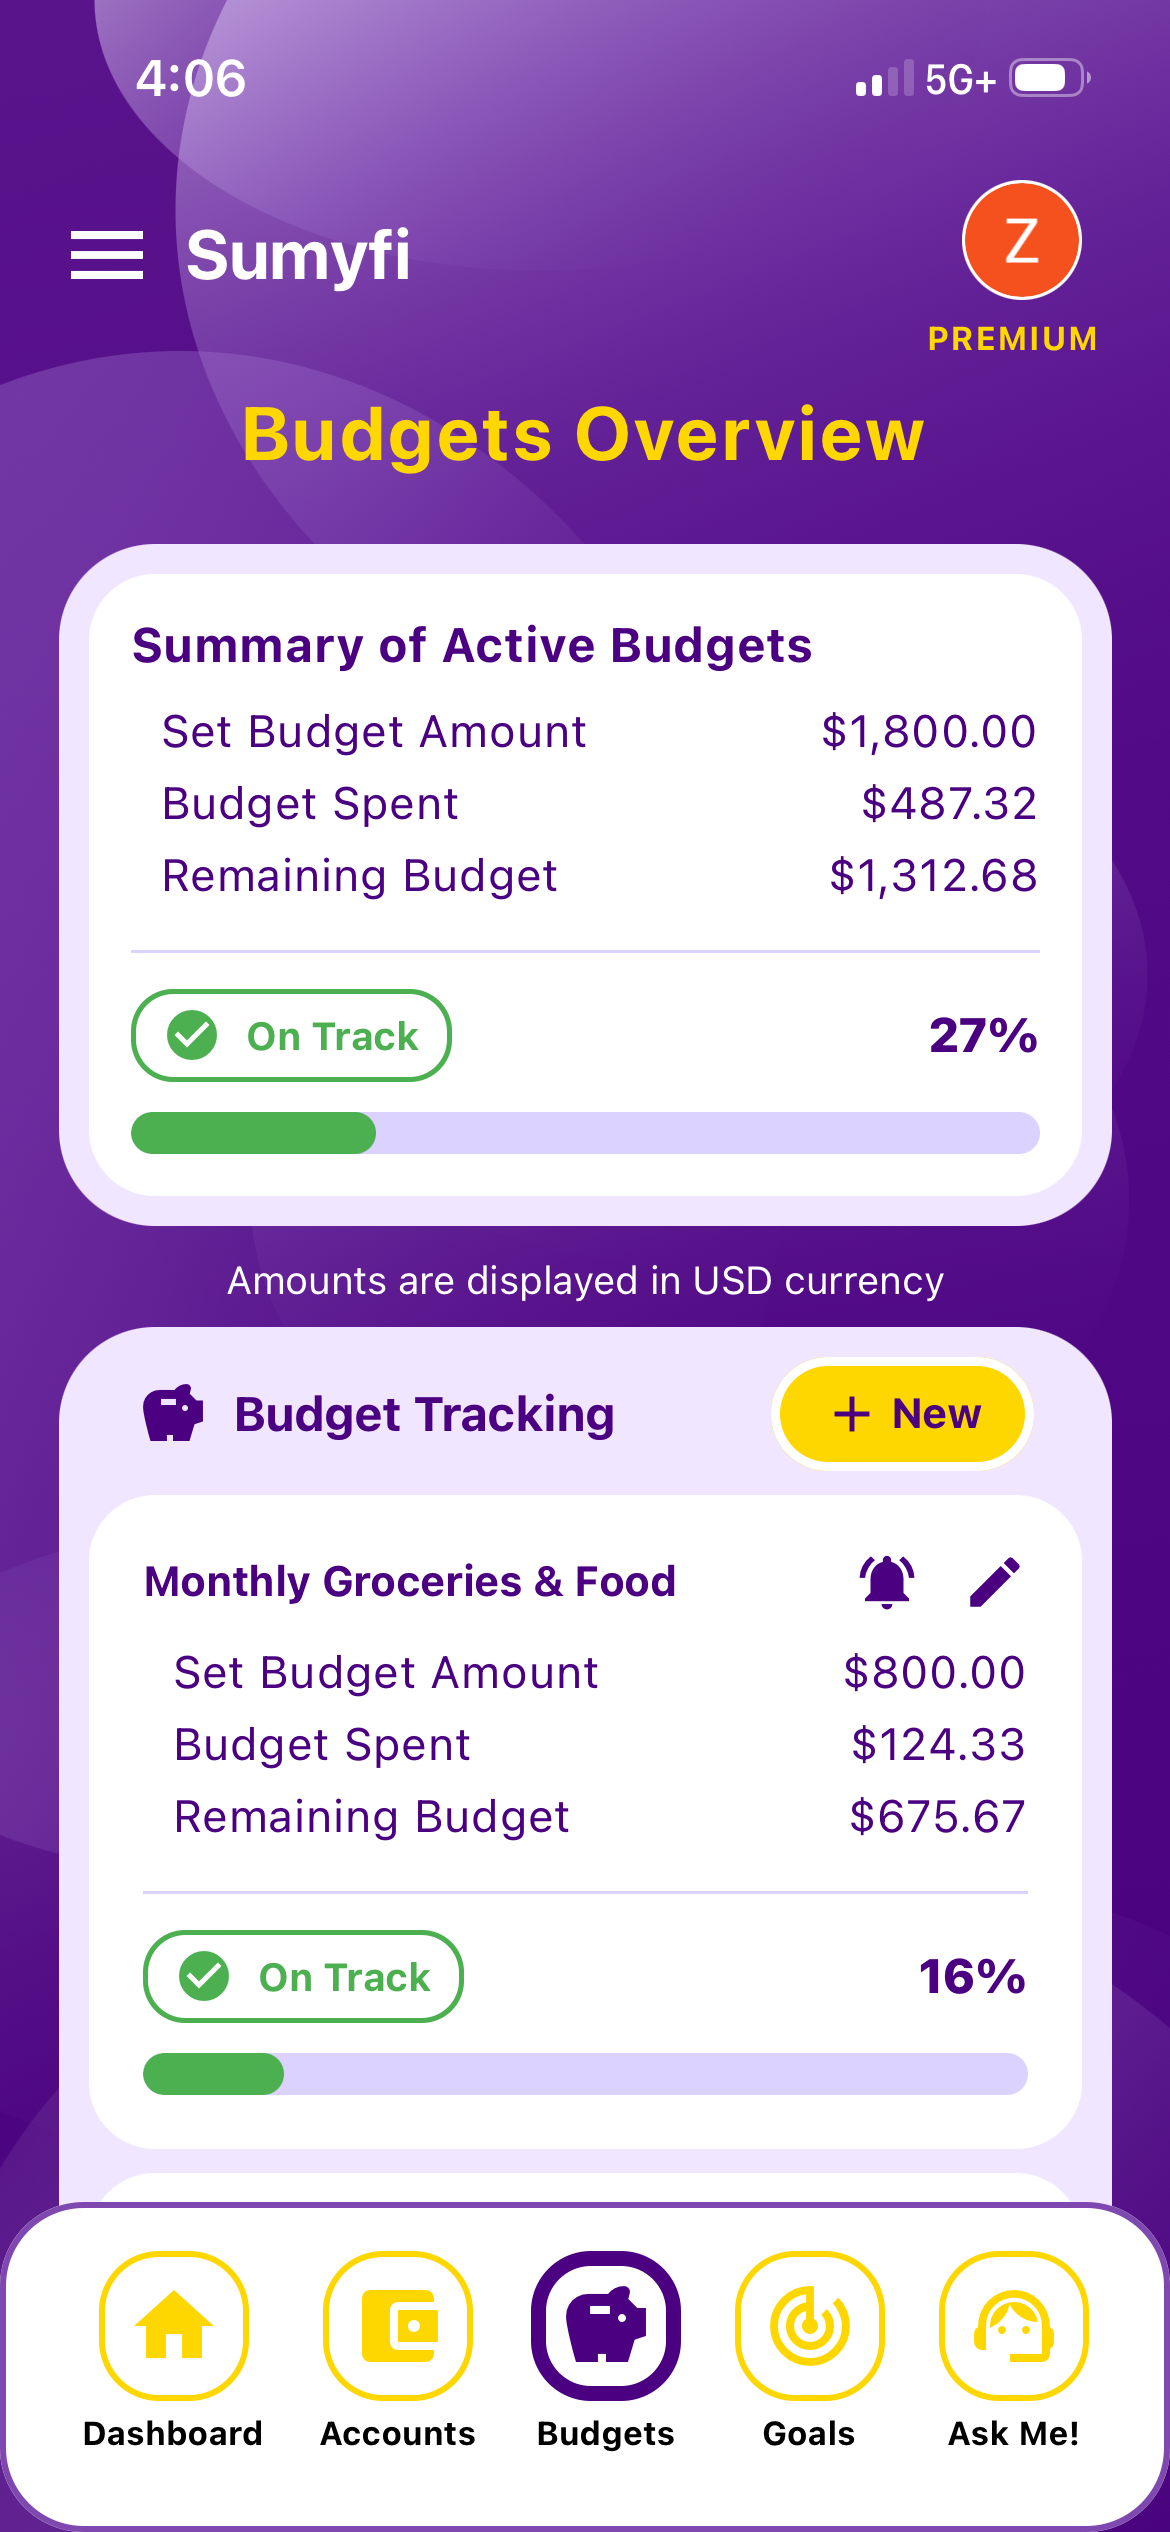
Sumyfi puts goals, budgets, accounts, debts and net worth on one dashboard, which is the main thing a beginner's plan needs. Goal setting and progress tracking are on the free plan, along with budgets, manual accounts and basic reports. Premium adds automatic bank sync through Plaid, predictive modeling, and an AI assistant that can set up the plan in plain language, for example 'create a goal called Emergency Fund for $8,250 by December 31.' Premium has a 7-day free trial. Sumyfi doesn't give investment advice, move money between accounts or check your credit score, and it's not a substitute for a certified planner if your situation is complicated.
Pros
- Goals, debts and net worth together on one dashboard
- Goal tracking included on the free plan
- Free calculators for debt payoff and emergency funds
Cons
- No investment advice or account management
- Bank sync and predictive modeling require Premium
Revisit the plan twice a year
A plan isn't something you set once. Look at it properly every six months, and any time something big changes: a new job, a raise, a move, a baby, a debt paid off. Check whether each goal is on pace, whether the order still makes sense, and whether the monthly amounts should go up.
In between, the only thing to watch is whether the monthly contributions are actually happening. If they are, the plan is working, even if it feels slow. Most beginner plans succeed through boring consistency, not clever moves.