The best budgeting app in Canada should not just categorize spending. It should help Canadians review accounts, recurring bills, goals, and monthly drift in one workflow that still feels easy to use after the first month.
The Canadian personal finance landscape has entered a critical period of transition. For years, Canadian consumers watched as a wide variety of automated financial tools emerged in the United States, while domestic options remained relatively limited. Many Canadians relied on legacy applications like Mint to track their spending and manage their budgets. However, with Mint's closure, Canadian users were left searching for a modern, reliable alternative that could handle the unique requirements of the Canadian banking system.
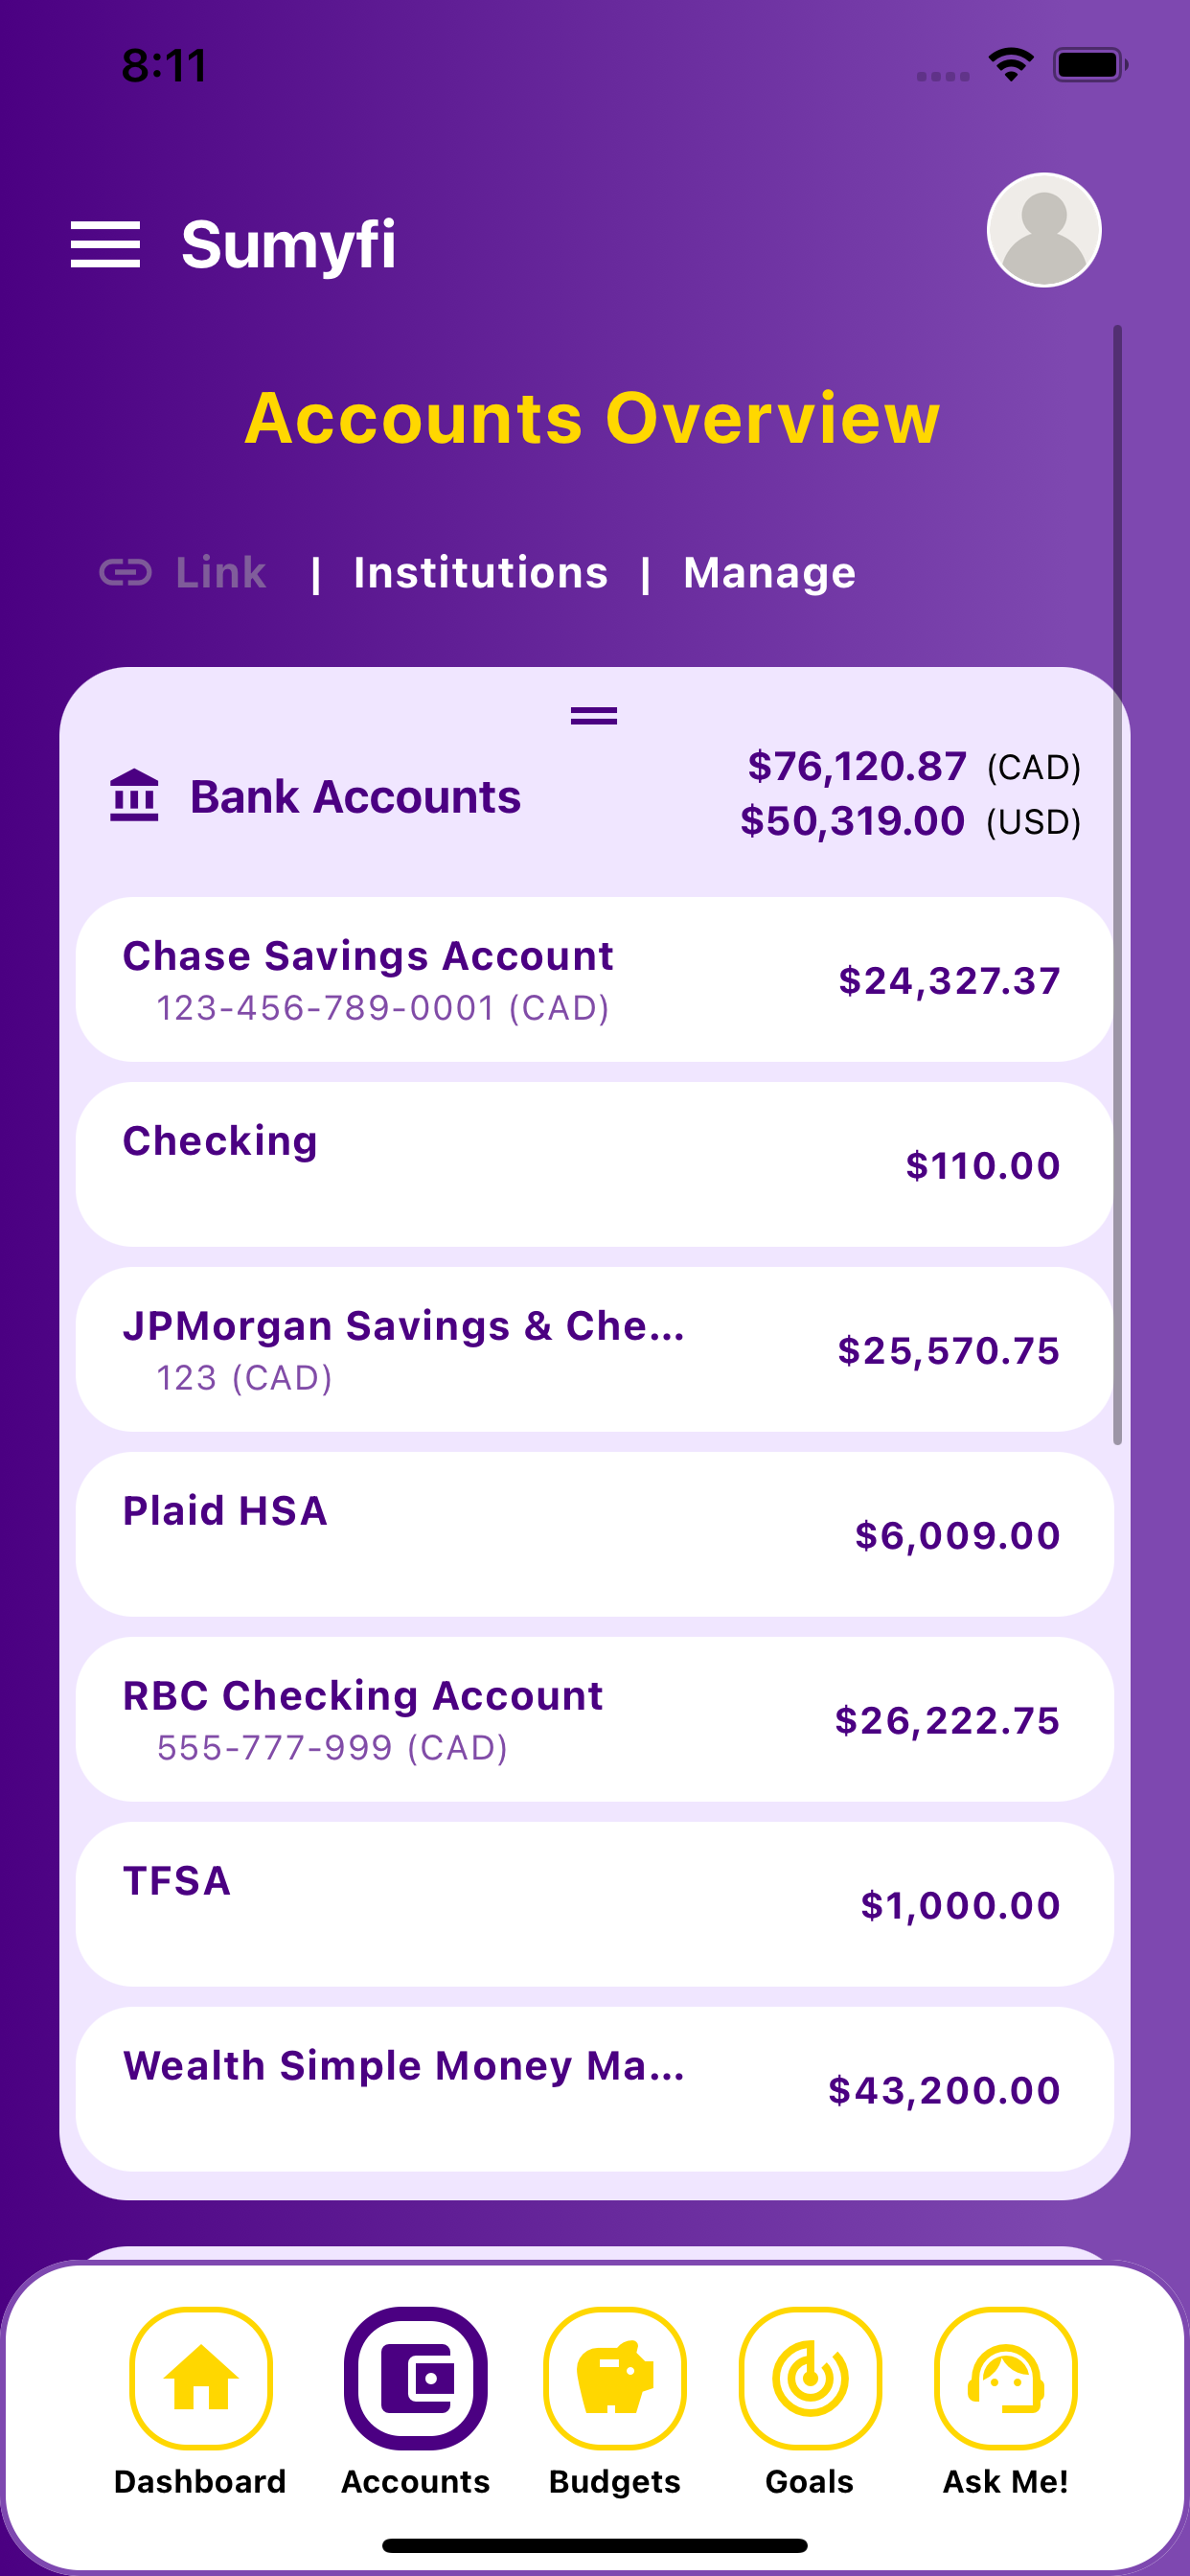
Finding the best budgeting app Canada has to offer requires looking beyond basic, manual entry tools. Canadian consumers need a sophisticated, secure platform that connects seamlessly with major domestic financial institutions, supports dual-currency tracking, automates expense categorization, and tracks long-term net worth.
Most budgeting apps in Canada fail when the budget gets separated from the real account picture
A lot of budgeting apps sound good in theory because they promise more discipline, better categories, or a clearer monthly plan. In practice, many Canadians abandon them because the app starts feeling like one more system to maintain on top of actual bank accounts, recurring bills, and everyday financial surprises. The more the budget lives apart from the live account picture, the more mental reconciliation the user has to do every week.
That problem is often underexplained in Canadian search results. Many roundup pages treat every budgeting app as if the only difference is the feature checklist. But the real question is whether the product helps a Canadian household make faster, better decisions during a normal month with rent, groceries, subscriptions, debt payments, and savings goals all competing for attention.
The best budgeting app in Canada therefore is usually the one that keeps the budget connected to accounts, recurring expenses, and progress tracking instead of turning budgeting into a separate chore. When the app reduces interpretation work, people keep using it longer.
- The budget has to stay close to the account picture
- Canadian users need an app that feels locally believable, not just globally available
- Repeat use matters more than feature count
What actually matters when Canadians compare budgeting apps
Start with Canadian fit and automatic syncing. If the app feels disconnected from Canadian financial life or depends on too much manual upkeep, retention usually collapses fast. Buyers should also look at whether subscriptions and recurring bills stay visible, because recurring pressure is often what makes or breaks a monthly budget in real life.
Next, evaluate how the product handles planning depth. Some apps are strong at methodology, some are strong at recurring-expense visibility, and some are stronger at giving the user one broader dashboard for accounts, budgets, goals, and net worth. The winner depends on whether the household wants a narrow budgeting system or a full financial operating view.
The strongest apps also feel modern and forgiving. A useful budgeting product should make it faster to spot drift, connect spending to goals, and understand where pressure is building, without making the user feel like every month requires a financial reset project.
Canadian support and credible cross-account syncing
Budgeting connected to recurring bills and subscriptions
Goal tracking and net worth visibility in the same product
A modern interface that encourages repeat use
Enough simplicity for everyday households, not only power users
Why Sumyfi is a compelling budgeting choice for Canadians in 2026
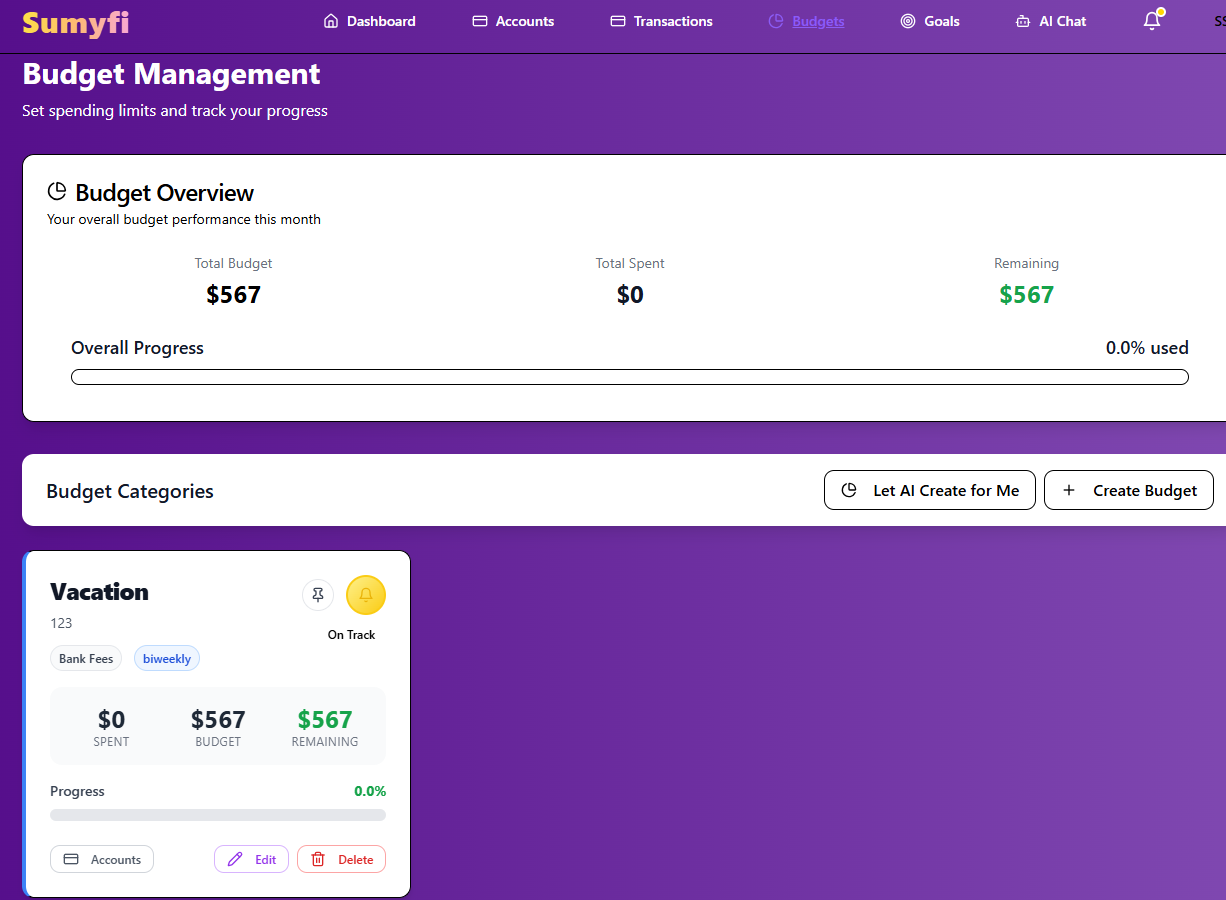
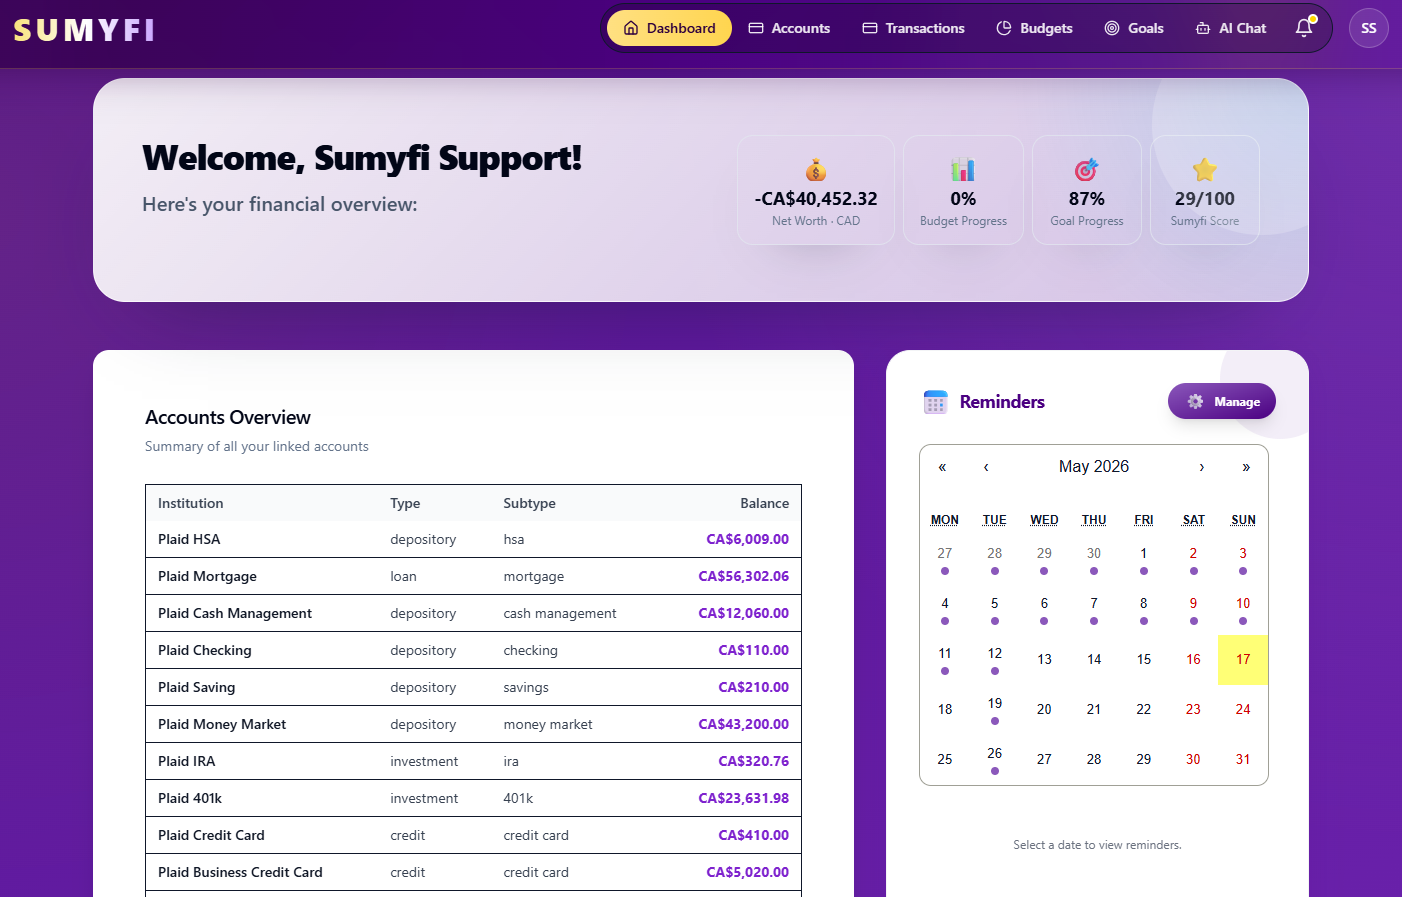
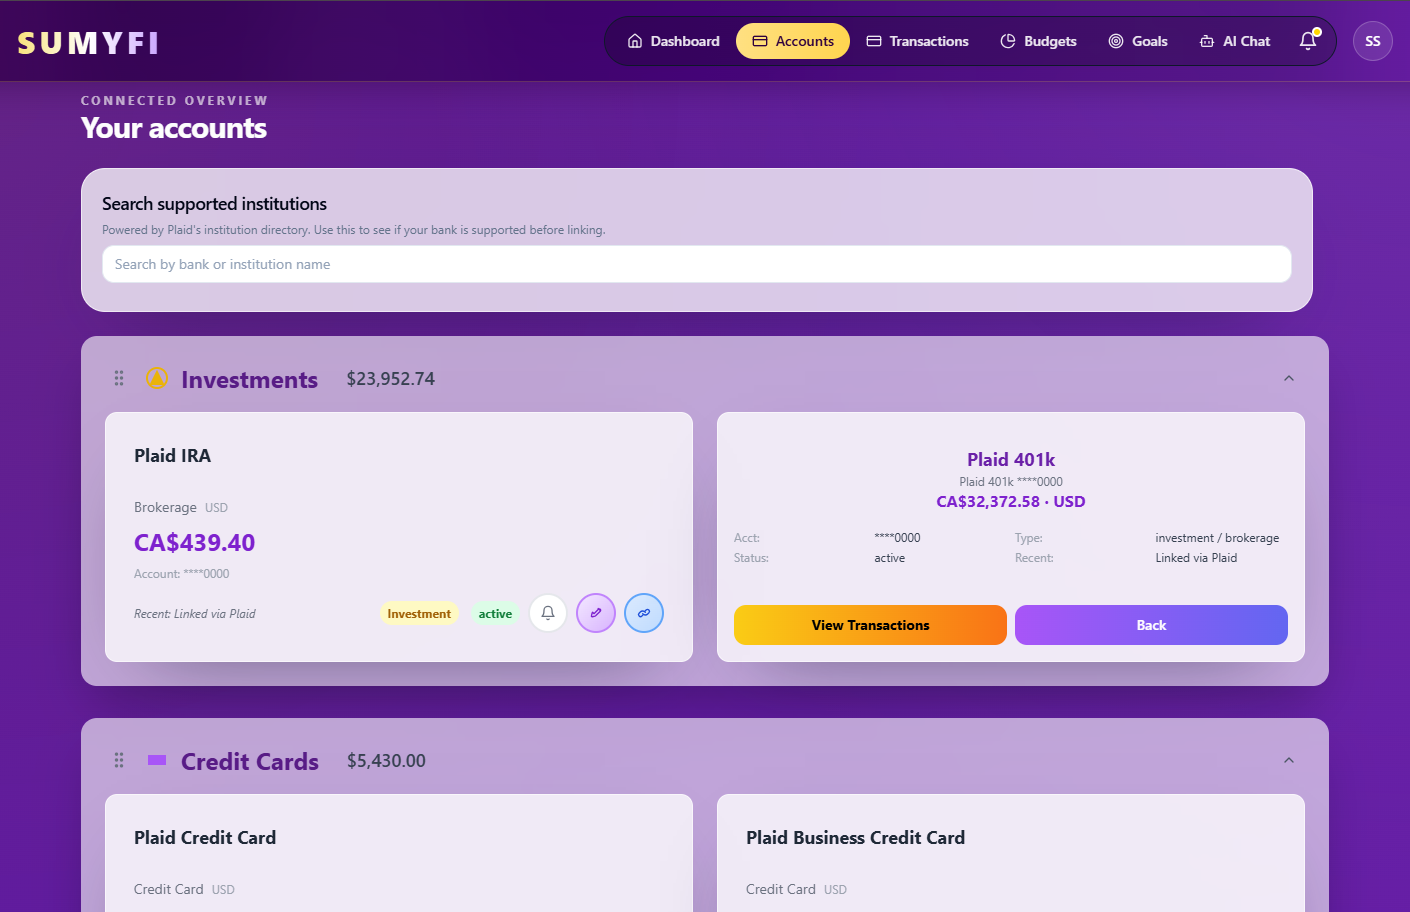
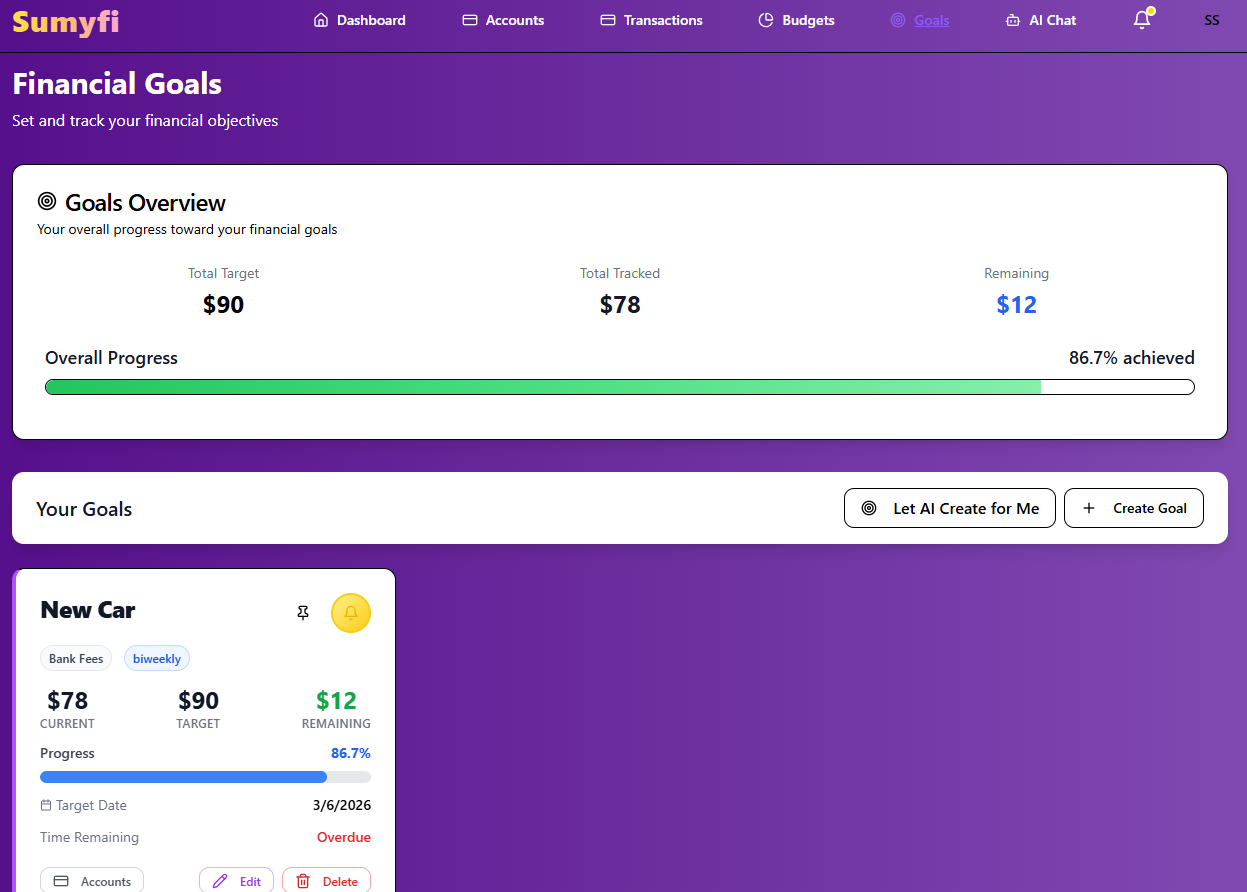
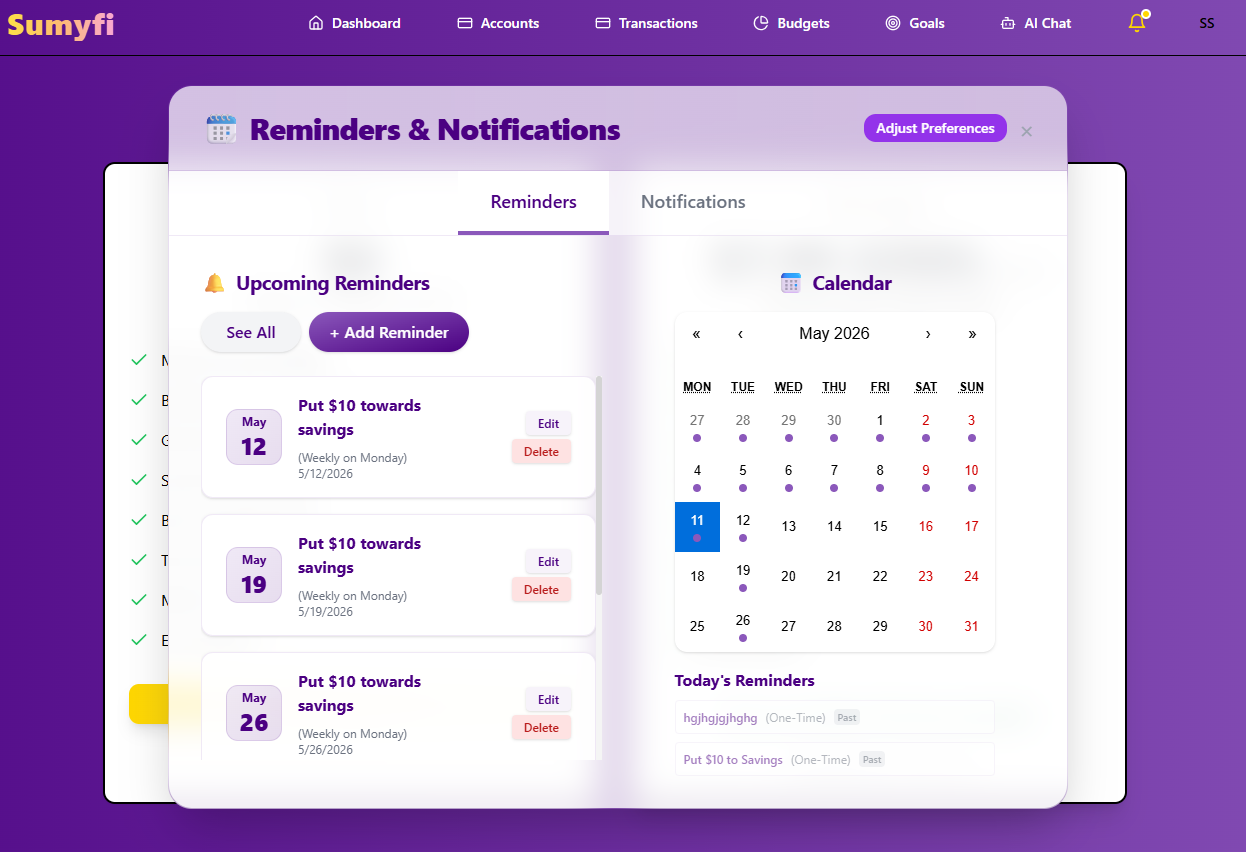
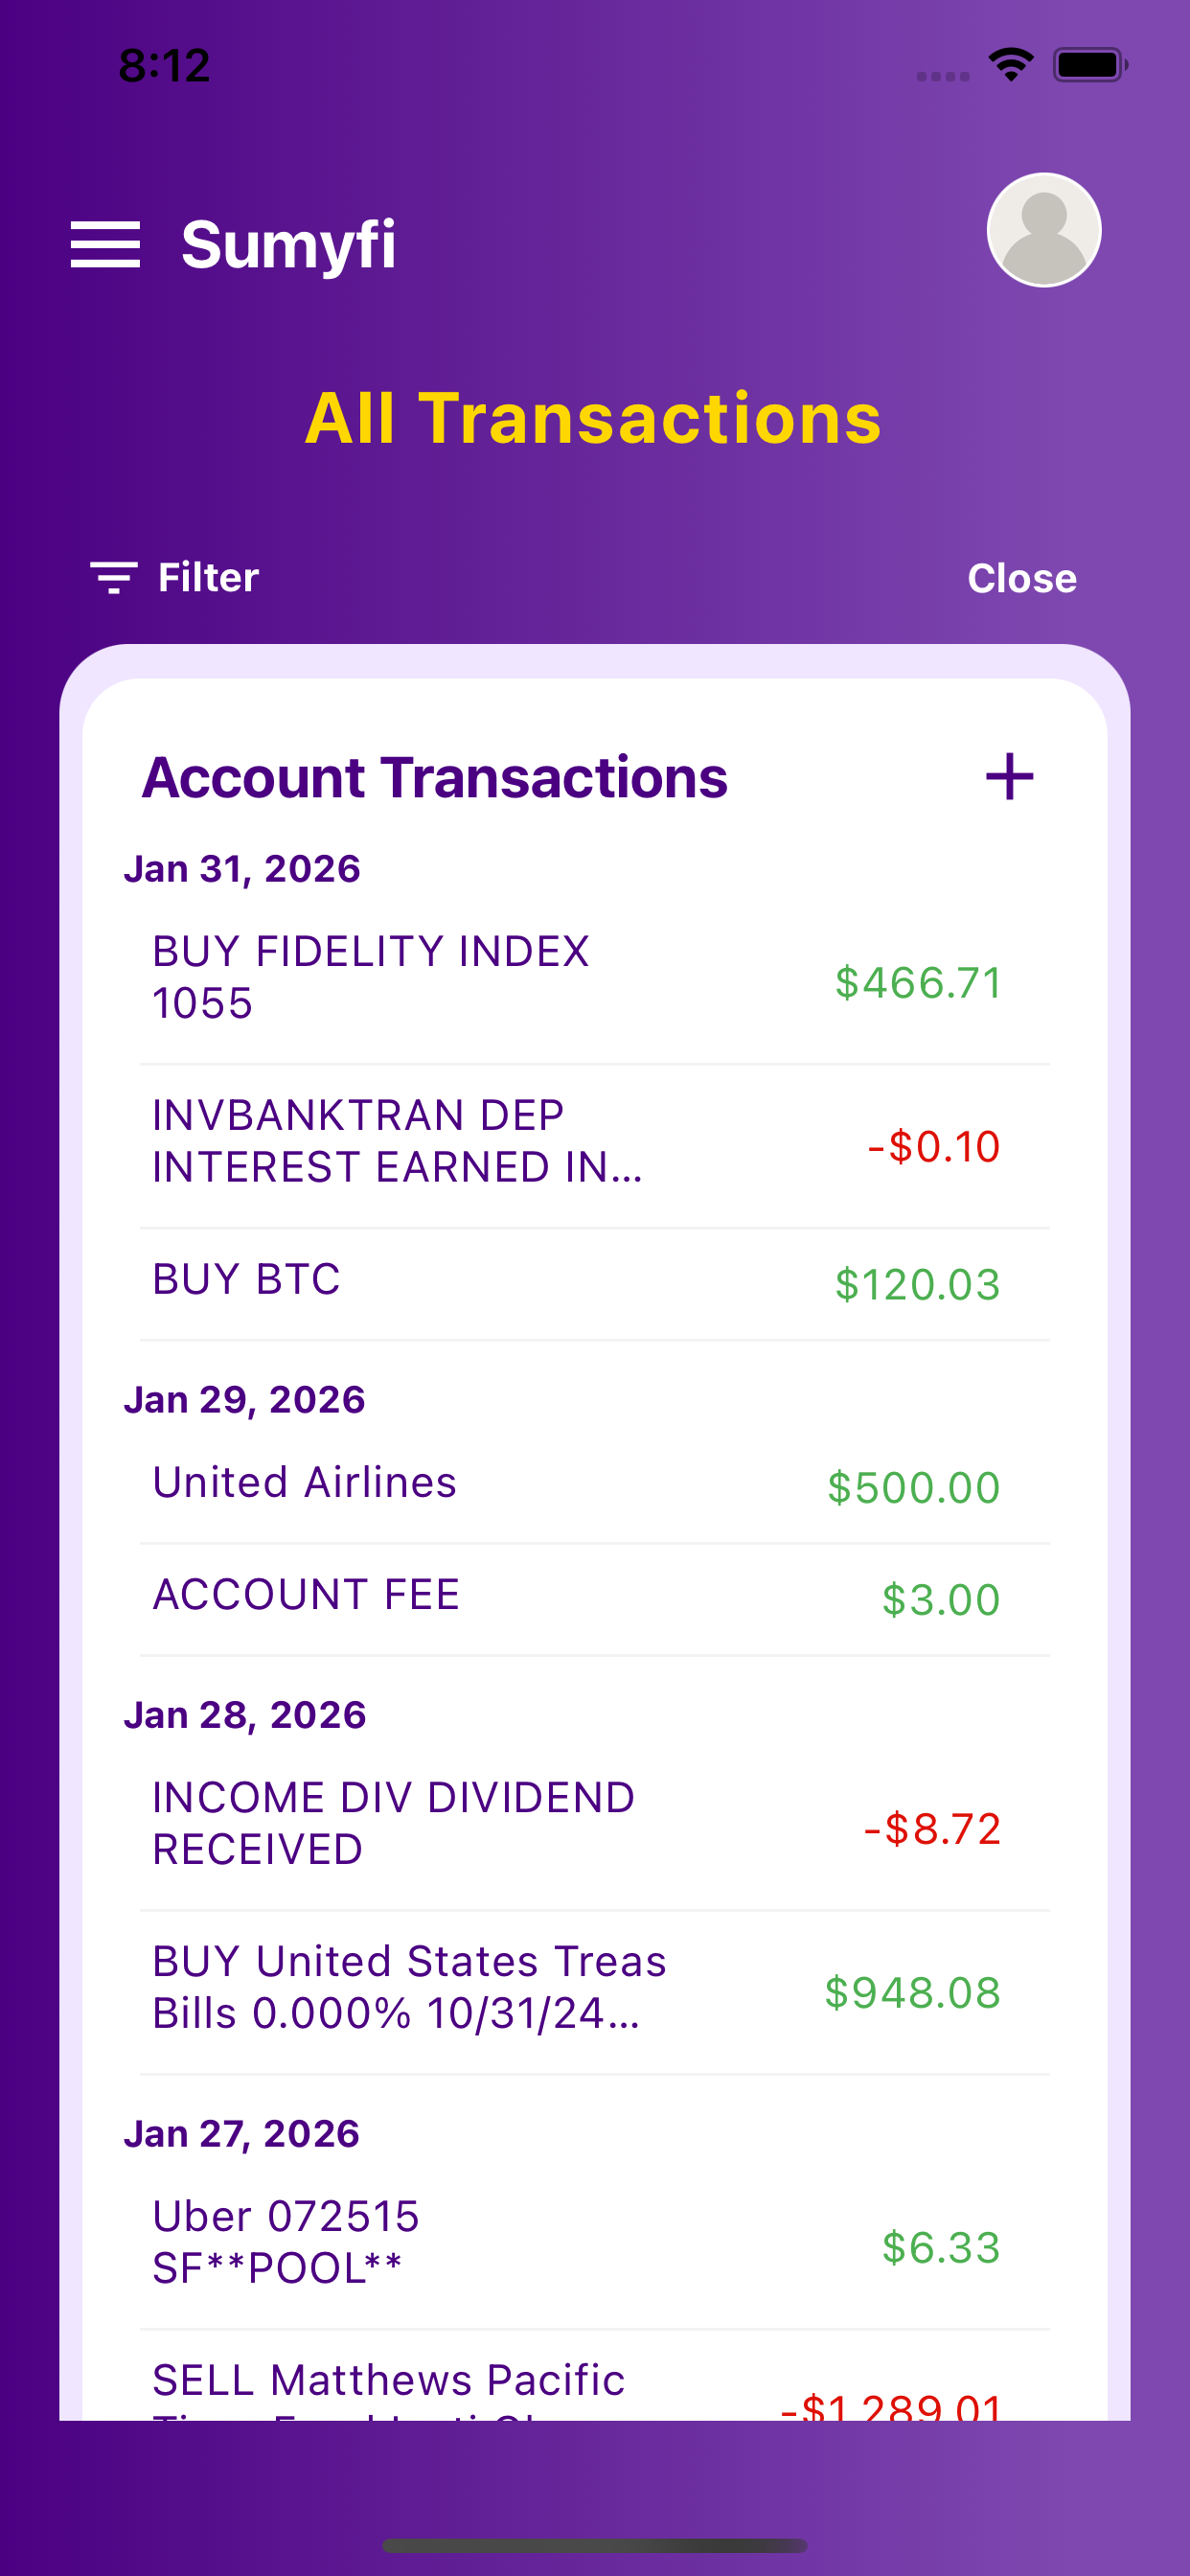
Sumyfi is strongest when the buyer wants budgeting to live inside a broader money system instead of a rigid budgeting silo. The app is designed to keep connected accounts, subscriptions, goals, budgets, and net worth close enough together that the budget actually helps with the next decision instead of just documenting the last one.
That makes the product a strong fit for Canadian households who do not want to choose between budgeting and visibility. Rather than forcing the user into a budgeting-only frame, Sumyfi aims to make the budget one part of a larger dashboard they can rely on every week. That usually creates better sticking power than tools that feel methodologically strong but practically disconnected.
The interface also matters. Many finance apps feel visually dated or too dense, which raises the friction of checking them. Sumyfi benefits from a more premium and current product surface, which supports the kind of regular use budgeting tools need if they are going to be effective beyond the first month.
Budgets, accounts, subscriptions, goals, and net worth kept together
Built for Canadian users who want clarity without spreadsheet upkeep
A cleaner weekly-review workflow than narrow budgeting-only tools
Modern dashboard feel that supports better long-term retention
Where competing budgeting apps often create friction for Canadians
Some apps are excellent if you want a deeply structured budgeting method and do not mind maintaining it closely. Others are better for subscription visibility or broad premium-style overviews. But many Canadians are not looking for a budgeting hobby. They want one product that helps them understand the month quickly and stay oriented without juggling extra tools.
That is where the category gets tricky. The more the product splits budgeting, recurring bills, and account visibility into separate surfaces or mental models, the less likely the user is to keep coming back. Poor Canadian support makes that even worse because the whole workflow starts to feel imported instead of grounded in the user's real financial life.
The better budgeting page should be honest about that tradeoff. Methodology depth, premium polish, and subscription tools all matter, but the strongest everyday budgeting app is the one that reduces friction across the whole household money loop.
- Rigid systems can create more maintenance than normal households can sustain
- Subscription-first apps often underserve broader budgeting needs
- Premium dashboards can still feel incomplete if planning and recurring pressure stay too disconnected