Mint is gone, but Canadians still need one reliable place to see accounts, track subscriptions, monitor savings goals, manage budgets, and understand net worth without stitching together multiple apps. This guide compares the strongest options and explains why Sumyfi is built to feel more useful for Canadian households in 2026.
For years, Mint stood as a familiar, if sometimes flawed, cornerstone for millions managing their money. Its recent sunsetting has left a significant void, sparking an urgent search for a robust, reliable, and truly Canadian-centric replacement.
This isn't just about finding *an* alternative; it's about discovering the *best Mint alternative Canada* can offer - a platform engineered for the modern Canadian financial ecosystem. We're talking about a solution that doesn't just replicate Mint's features but vastly surpasses them in connectivity, intelligence, and user experience. Enter Sumyfi: the all-in-one personal finance hub poised to redefine how Canadians interact with their money, replacing manual spreadsheets, cleanly tracking net worth, automating transactions, and seamlessly connecting with thousands of financial institutions across both Canada and the US.
Mint disappeared, but the real pain is losing one clear place to review money
When Mint shut down, a lot of Canadians lost more than a budgeting app. They lost a simple weekly ritual. Mint gave people one place to scan balances, spot subscription drift, glance at categories, and decide whether the month still felt on track. Once that disappeared, many users ended up in a fragmented stack of bank apps, spreadsheets, and narrow-purpose finance tools that do not recreate the same sense of orientation.
That fragmentation is worse in Canada because many rankings and reviews are still written as if Canadian and American finance workflows are interchangeable. They are not. Canadian users care about local bank support, a believable account-syncing story, and a dashboard that feels useful for recurring bills, savings goals, and net worth review without importing assumptions from a U.S.-first product experience.
The best Mint alternative in Canada therefore is not the app that most resembles Mint visually. It is the app that rebuilds the habit Mint used to support while improving the parts people were already outgrowing: disconnected tools, outdated design, and too much hidden maintenance.
- A Canadian-first lens matters more than generic 'best app' lists admit
- The replacement has to restore a weekly habit, not just recreate an old dashboard layout
- Fragmented finance stacks usually break because they create too much manual interpretation
What Canadians should demand from a Mint alternative in 2026
Start with Canadian support. The app should feel credible for Canadian households, not merely available in Canada. That means account connectivity that feels believable, language that matches the way people actually think about their money, and a budgeting workflow that supports real recurring expenses instead of requiring a niche methodology to stay functional.
Then look at workflow depth. The strongest Mint alternative should handle automatic account syncing, subscription tracking, budgeting, net worth tracking, and financial goals inside one experience. If each of those jobs lives in a separate app or a separate mental model, the product may look modern but still leave the user doing the same stitching work Mint users are trying to escape.
Security and ease of use matter just as much. A finance app has to be trustworthy enough to connect important data and simple enough to revisit during a busy month. The better products shorten the time between opening the app and understanding what changed, which bills are recurring, and what deserves attention next.
Canadian bank support and broad institution coverage
Automatic syncing that stays useful after initial setup
Subscription tracking tied to the full transaction picture
Budgeting, net worth, and goals visible in one system
Strong security posture and a mobile-friendly experience
A clean interface that reduces maintenance rather than adding another chore
Why Sumyfi stands out for Canadians replacing Mint
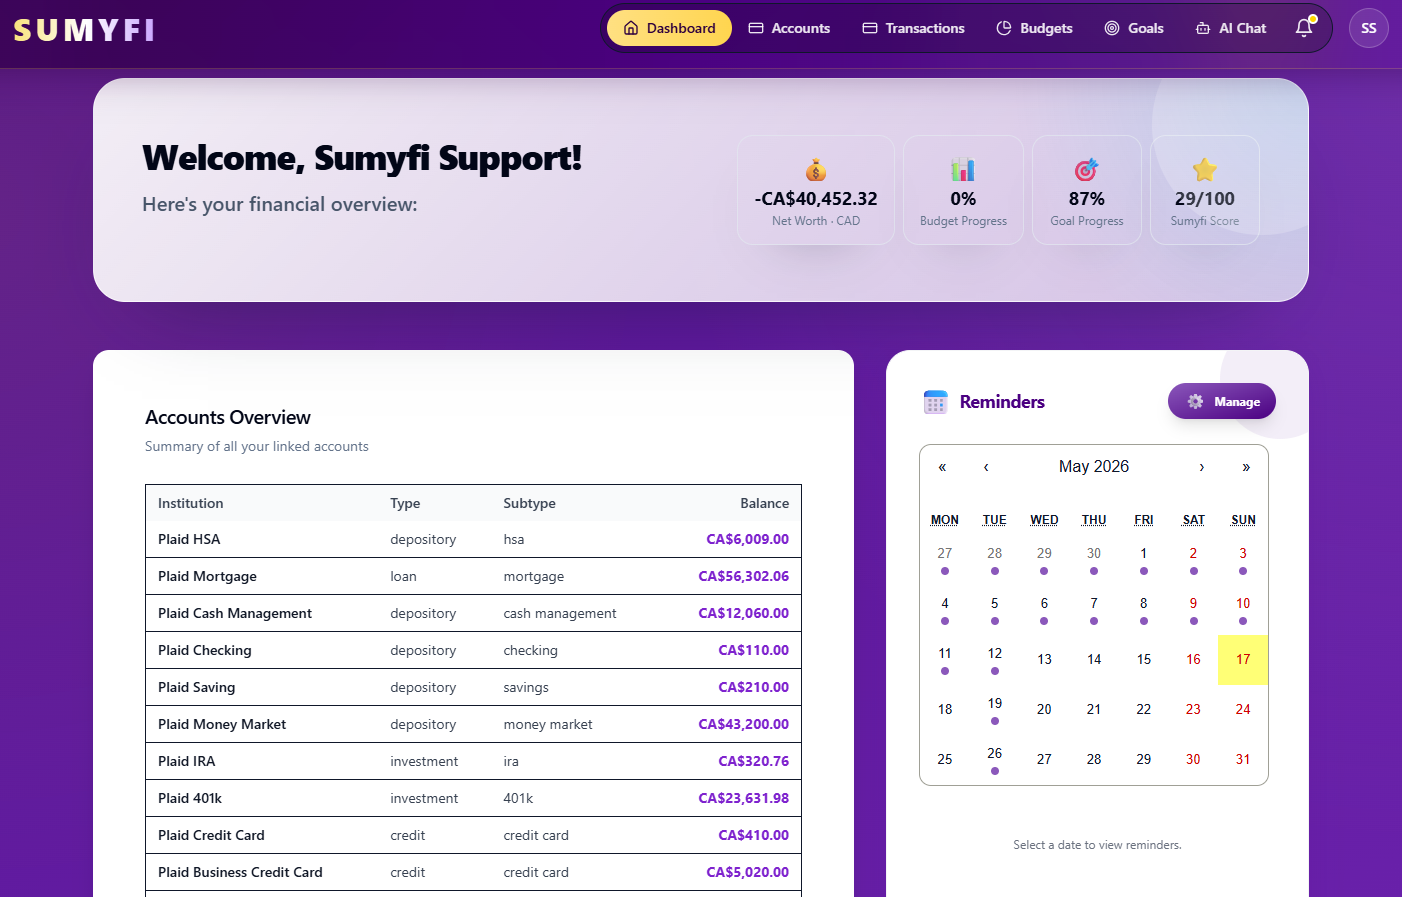
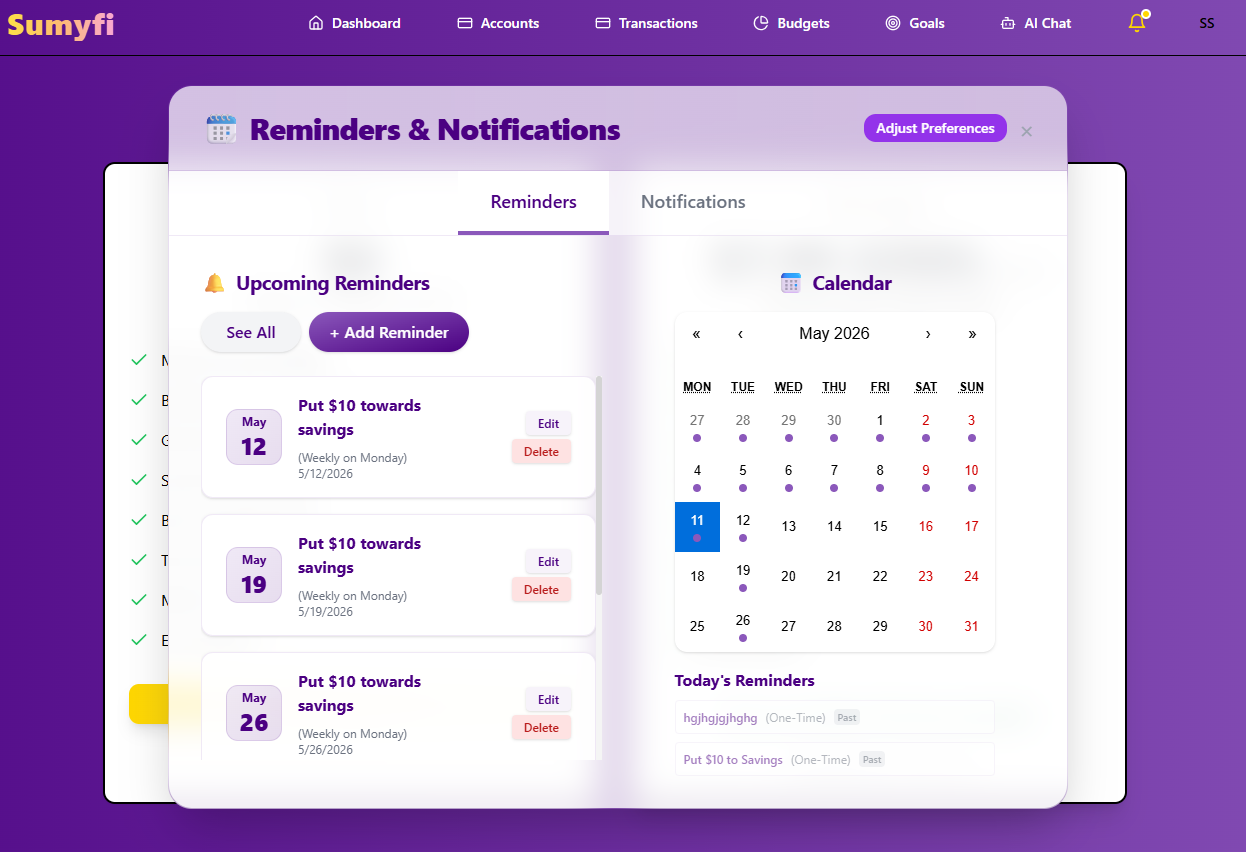
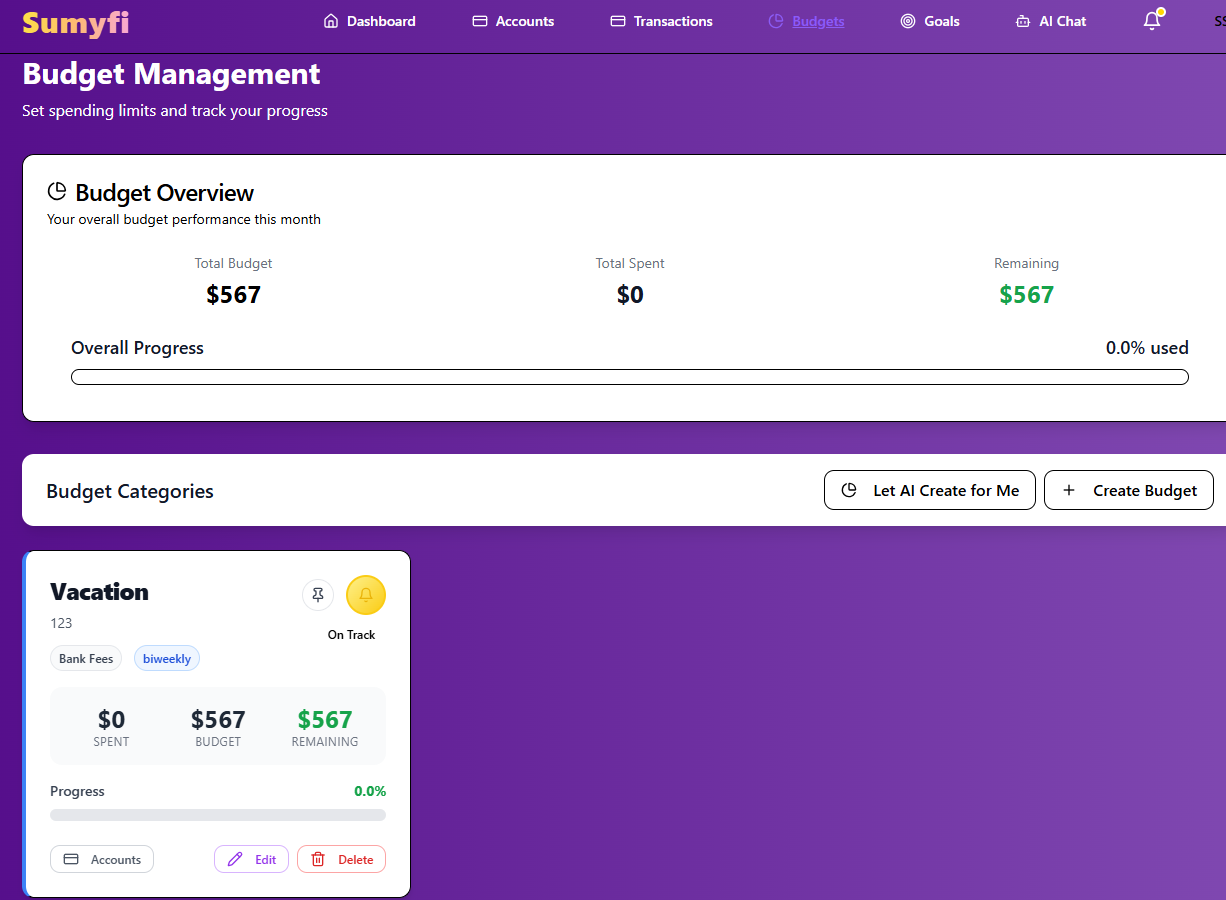
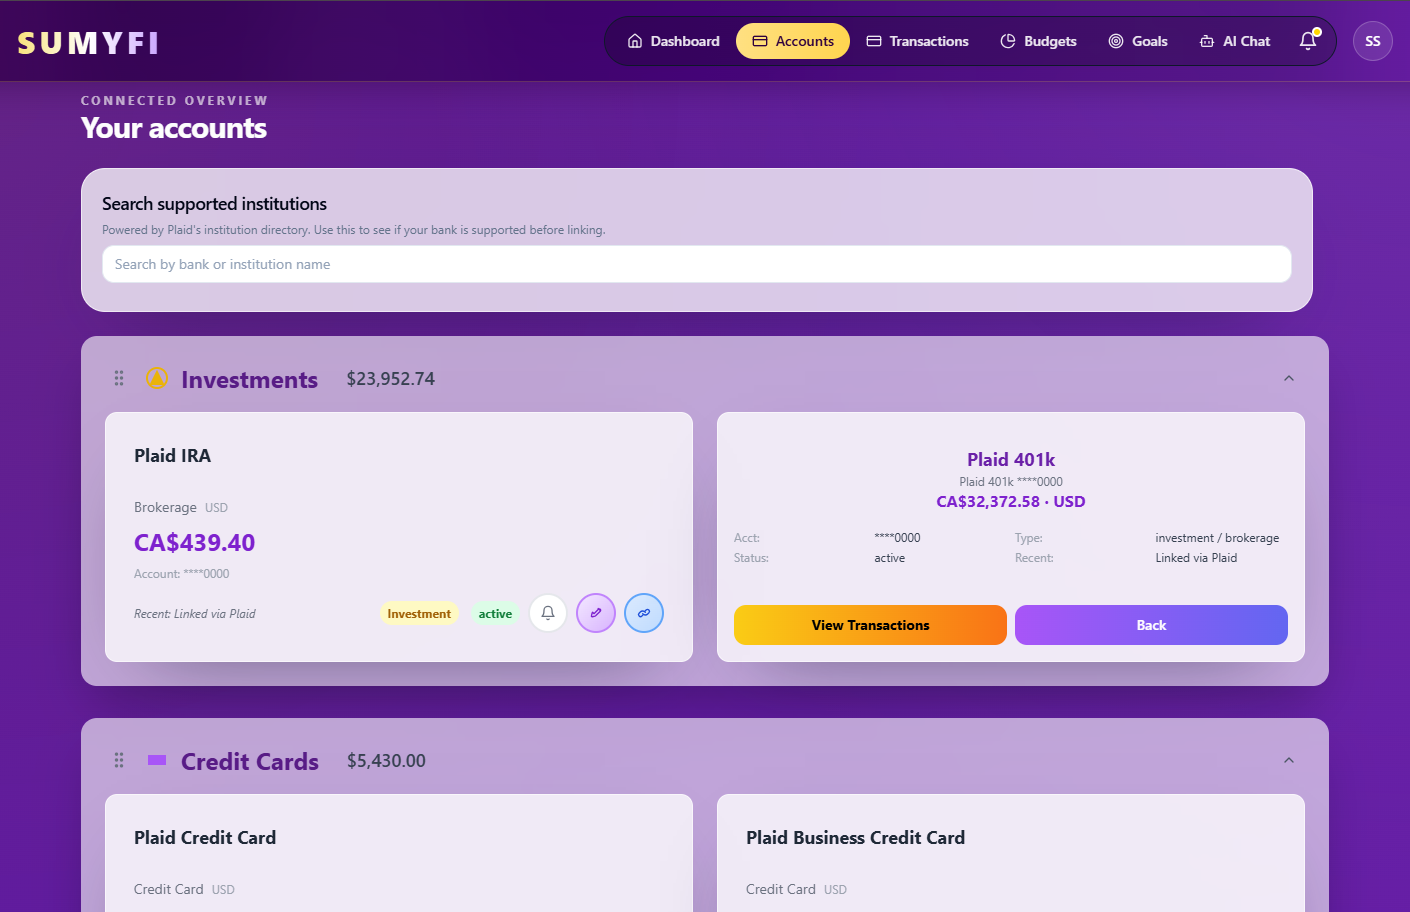
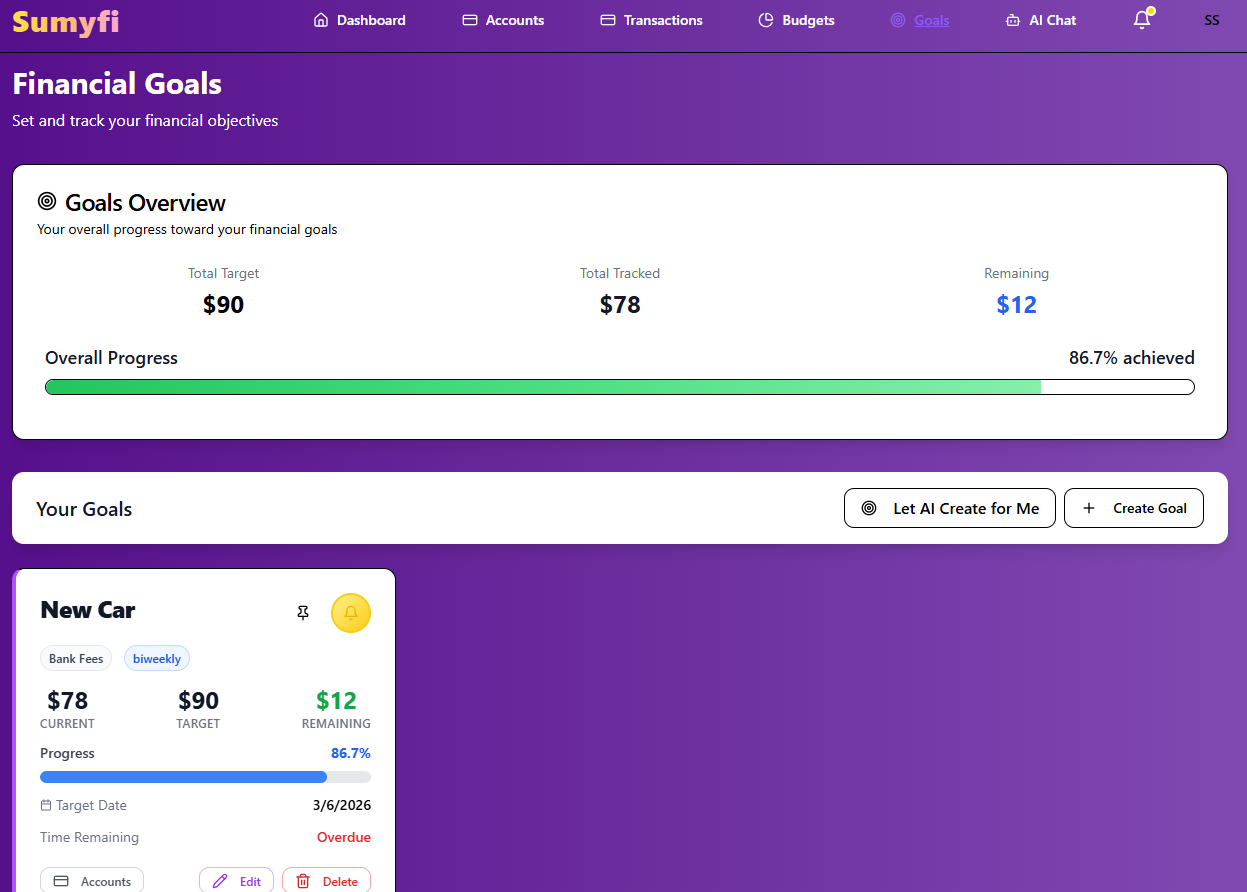
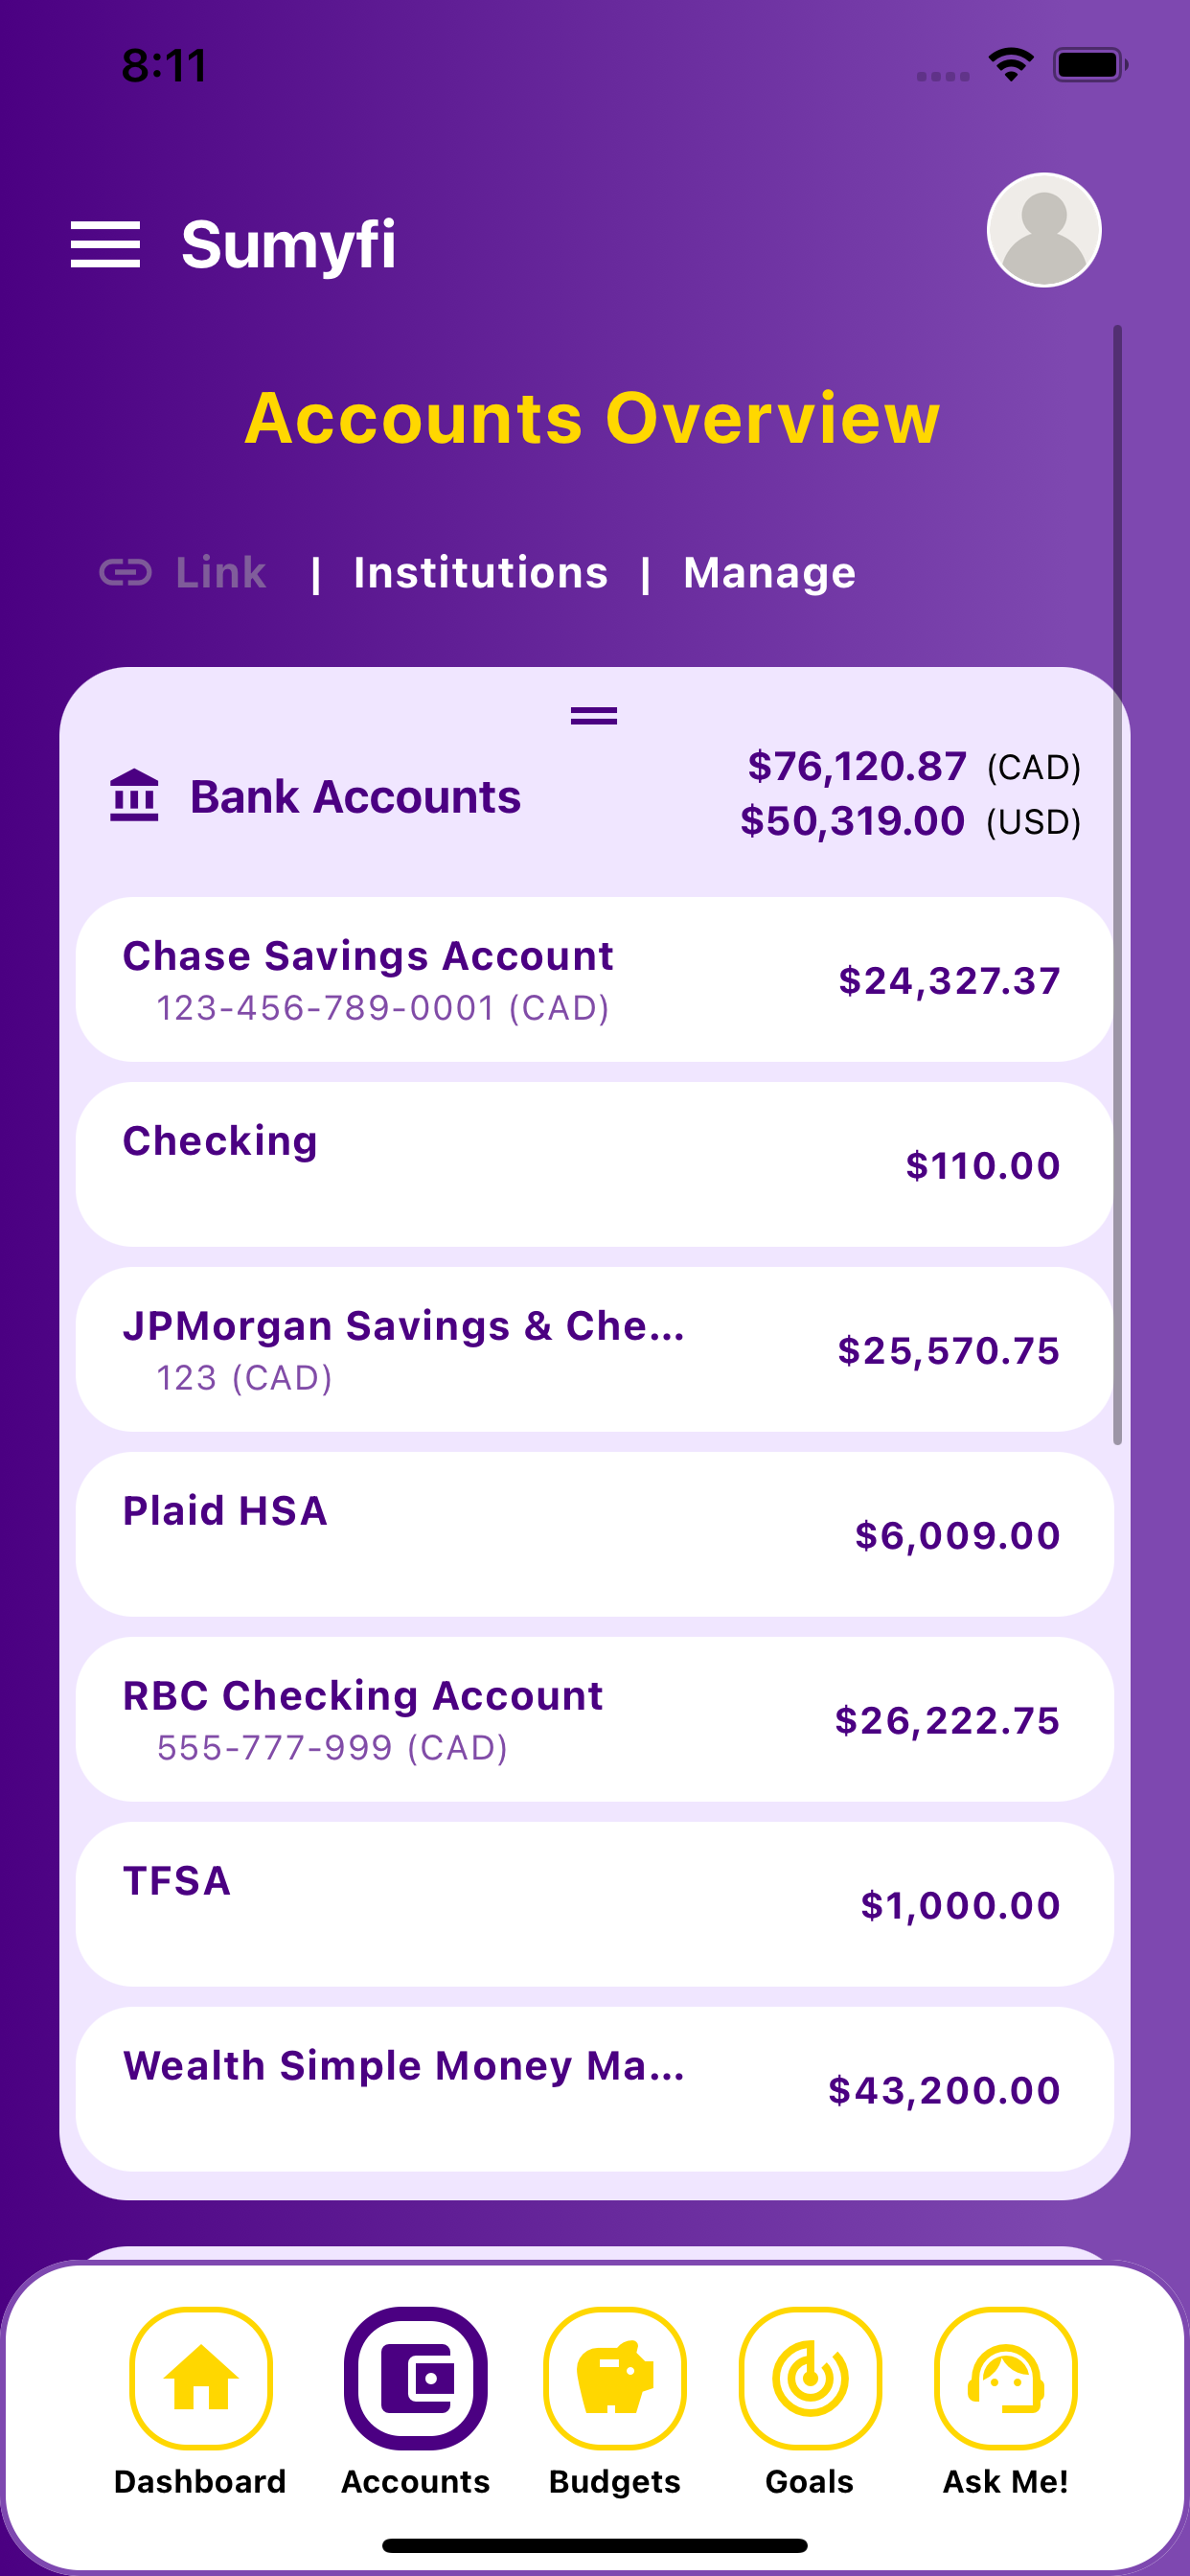
Sumyfi is strongest when the buyer wants an all-in-one financial operating system rather than a narrow feature substitute. The product keeps accounts, budgets, subscriptions, net worth, and goals connected in one modern interface, which makes the dashboard feel more like a control center than a set of disconnected widgets.
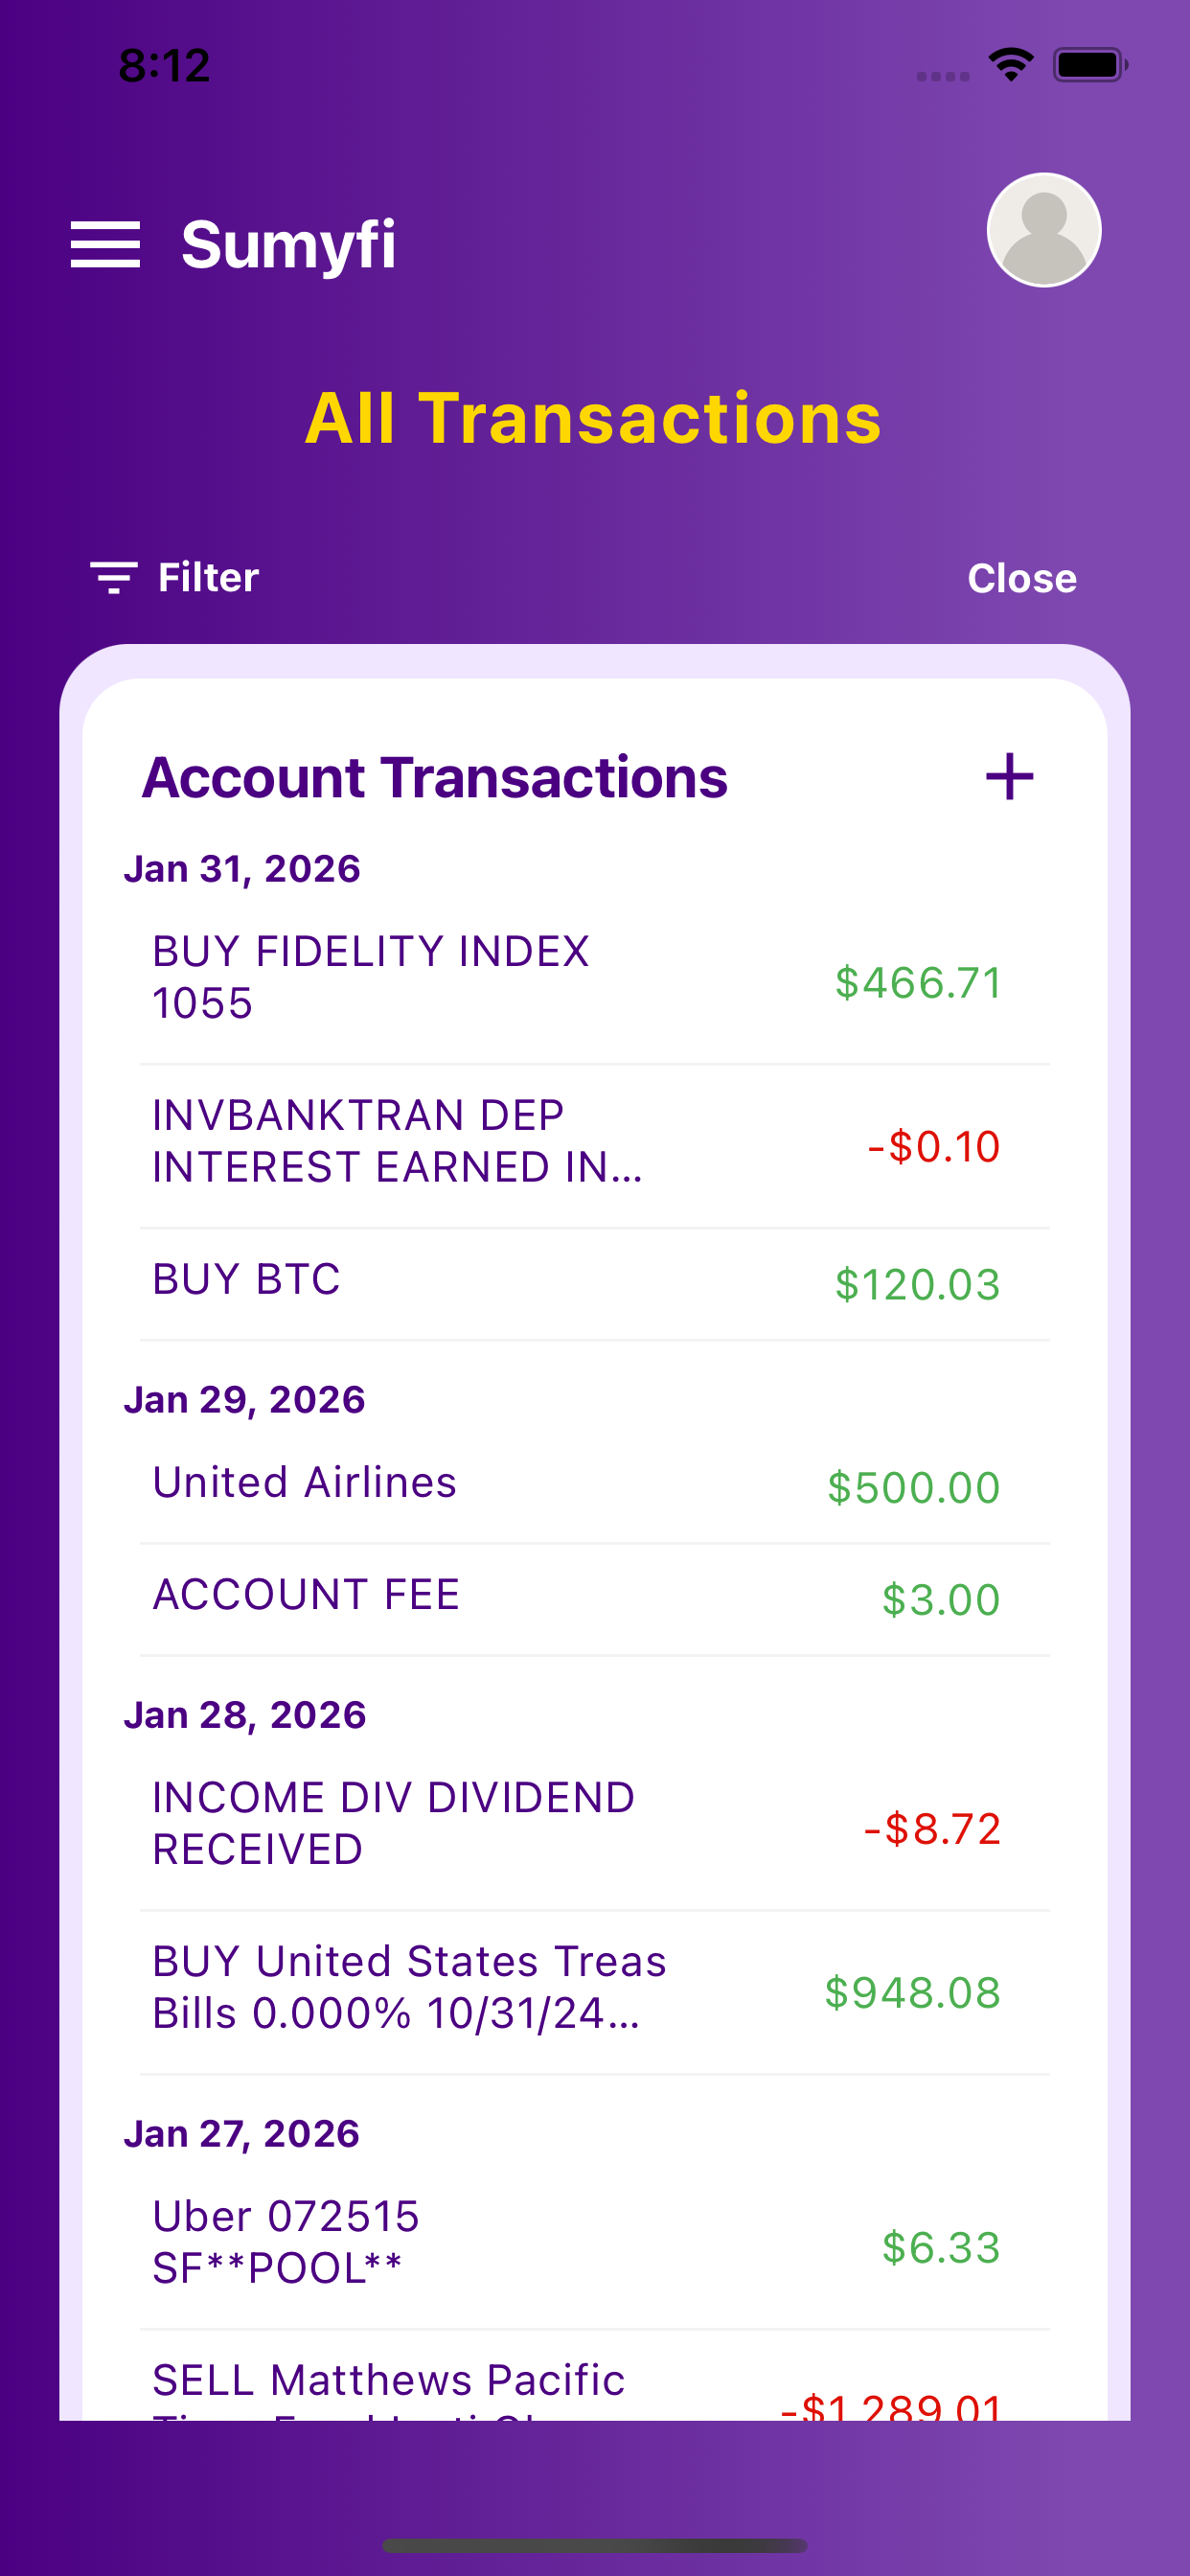
That matters for Canadians because the real decision is about simplicity. The best app is usually the one that becomes the default place you check every week. Sumyfi aims at that behavior by giving users one cleaner workflow for account aggregation, spending visibility, recurring-charge review, goal tracking, and AI-supported context instead of forcing them to keep a spreadsheet or a second app open beside it.
The product also feels more current than many legacy replacements. A premium SaaS-like interface matters here because financial software gets abandoned quickly when it feels outdated or heavy. Sumyfi is trying to win not only on feature coverage, but on the likelihood that a Canadian household will still want to use the dashboard after the first few weeks of migration are over.
Canadian-focused alternative with cross-border support
All-in-one dashboard for accounts, subscriptions, budgets, net worth, and goals
Modern UI that feels more like a premium fintech product than legacy finance software
Designed to replace fragmented workflows, not just one missing app logo
Where other Mint replacements still fall short for many Canadians
A lot of alternatives still create spreadsheet fatigue. They may technically support budgets or net worth, but the user ends up manually reconciling categories, checking recurring charges elsewhere, or rebuilding the broader picture with exports and notes. That is not a real upgrade from the post-Mint mess people are already frustrated by.
Other products are too narrow. Some focus heavily on budgeting methodology, others lean into subscription cleanup, and others are mostly attractive dashboards without enough connective tissue underneath. For Canadians, poor local support can make that worse. Even a polished app loses trust quickly when the product feels like it was designed for another market and only extended into Canada later.
Outdated UI is another hidden problem. Finance products that feel cluttered or dated tend to make monthly review slower, which directly harms retention. The strongest replacement is the one that keeps multiple jobs together without feeling crowded, old, or difficult to interpret when life gets busy.
Spreadsheet fatigue from too much manual review
Poor Canadian support or Canada treated as an afterthought
Disconnected tools for budgeting, subscriptions, and net worth
Outdated interfaces that make financial review feel like work