For US households, the right Monarch alternative comes down to three things: whether your banks and retirement accounts connect, whether it handles a biweekly paycheck sensibly, and whether you'd pay for it at all. Here's how to check each one.
Most Americans shopping for a Monarch Money alternative in the USA arrived at Monarch the same way: Mint shut down, Credit Karma wasn't a budgeting app, and Monarch was the name everyone recommended. Some of those people are happy. Others have now paid for a year or two and are asking a fair question: is this the right tool for how my household actually handles money, or just the one I grabbed in a hurry?
This guide is written for US households specifically. It covers how to test connections with American banks, card issuers and retirement accounts, why a biweekly paycheck changes what you need from a budgeting app, which US costs tend to wreck a monthly budget, and how Sumyfi compares. If you're in Canada, the questions are different enough that we cover them on a separate page.
Testing connections with US banks, cards and retirement accounts
Every budgeting app depends on a data aggregator to read your accounts, and US coverage is generally better than anywhere else. The big banks (Chase, Bank of America, Wells Fargo, Citi, Capital One) usually connect fine. Most of them now send you to the bank's own login page to approve access, which is more secure than typing your password into an app, but it also means connections can expire and ask you to re-approve every so often. That's normal, not a sign the app is broken.
Where results vary more is the long tail: smaller credit unions, online banks and fintech accounts like Chime or SoFi, store cards, and some card issuers. If you carry an American Express or Discover card, connect that early in any trial, because card accounts are where people most often see missing or duplicated transactions.
Retirement and investment accounts are the other test. If you want your 401(k) at Fidelity or Vanguard, a Roth IRA at Schwab, an HSA, or a 529 plan to show up in your net worth, check each one. Some employer 401(k) providers are harder to connect than the brokerages themselves. A balance you update by hand once a month is a perfectly good fallback for accounts you don't touch often.
Connect first
the account most likely to fail, usually a credit union or card
Check
that pending and posted transactions aren't double-counted
Check
that joint accounts only appear once if both partners link them
Fallback
manual balances for 401(k), HSA or 529 accounts that won't connect
The biweekly paycheck problem, and what a budgeting app should do about it
A lot of American employers pay every two weeks, not twice a month. That gives you 26 paychecks a year instead of 24, which sounds like a minor detail until you try to build a monthly budget around it. Ten months of the year you get two paychecks. Two months you get three.
Say your take-home pay is $2,100 every other Friday. In a normal month that's $4,200. In a three-paycheck month it's $6,300. If your budget assumes $4,550 (the yearly total divided by 12), you'll feel short most months and flush twice a year, and that extra $2,100 tends to disappear into general spending unless it has a job before it arrives.
A good setup budgets around the two-paycheck month and treats the third check as planned money: a savings goal, a chunk of credit card debt, the annual car insurance premium. Whatever app you use, see whether it lets you set a monthly budget from your real two-check income and then point the extra check at a goal. If you're working through Monarch alternatives in the USA and an app makes this awkward, that's a fair reason to rule it out.
The US costs that look like overspending but aren't
The most common reason people quit a budgeting app is a month that blows up for reasons that weren't really overspending. In US households the usual suspects are predictable, and a decent app should help you see them coming.
The fix is the same for all of them: add each one up for the year, divide by 12, and set that aside monthly in a savings goal. A $1,440 car insurance premium is $120 a month. Seen that way, the month it renews is just a transfer, not a crisis.
Insurance renewals
auto and renters policies billed every six or twelve months
Escrow changes
a property tax or insurance increase that raises your mortgage payment
Annual memberships
Amazon Prime, Costco or Sam's Club, and software that renews yearly
Car registration
due once a year and easy to forget
Medical bills
deductibles and copays that arrive weeks after the visit
Holiday spending
November and December, every year, without fail
How Sumyfi compares as a Monarch Money alternative in the USA
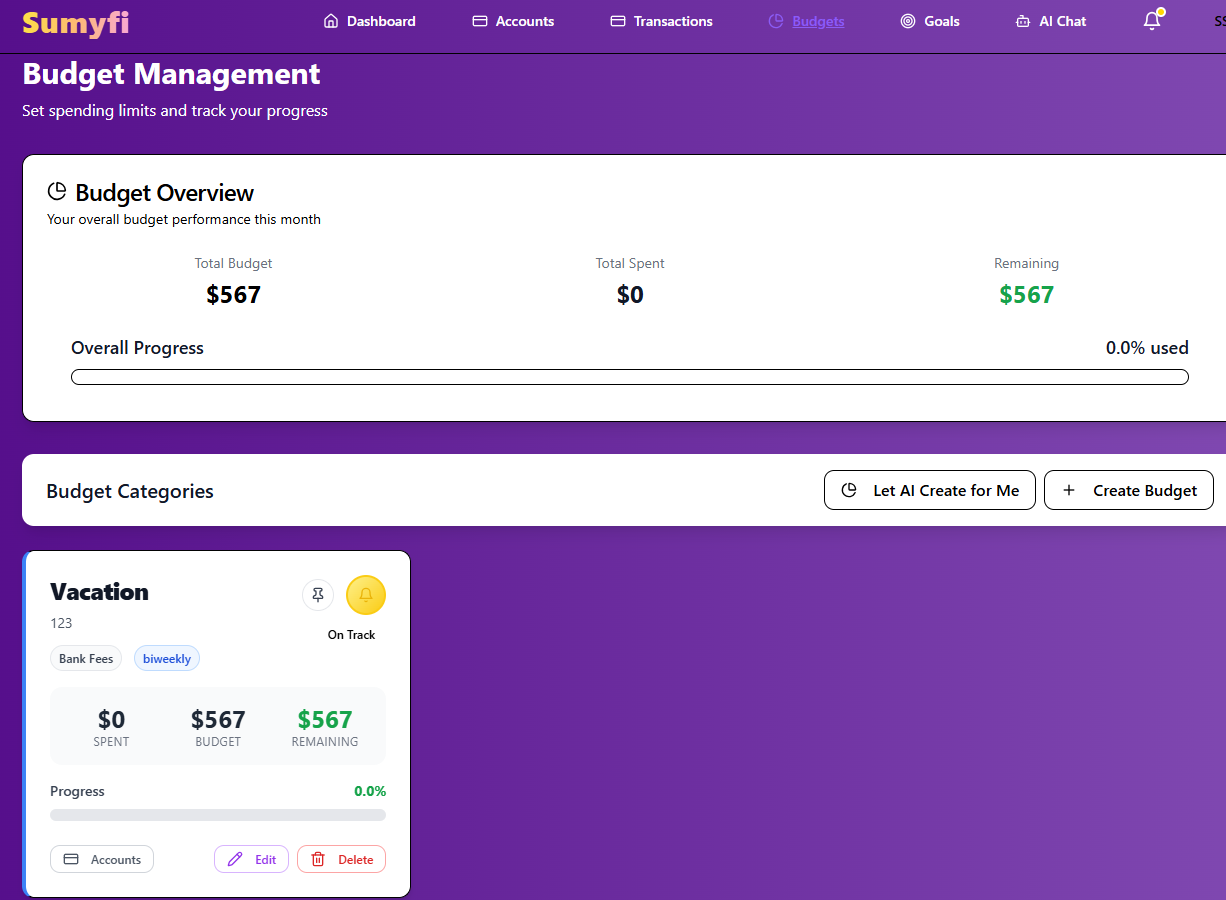
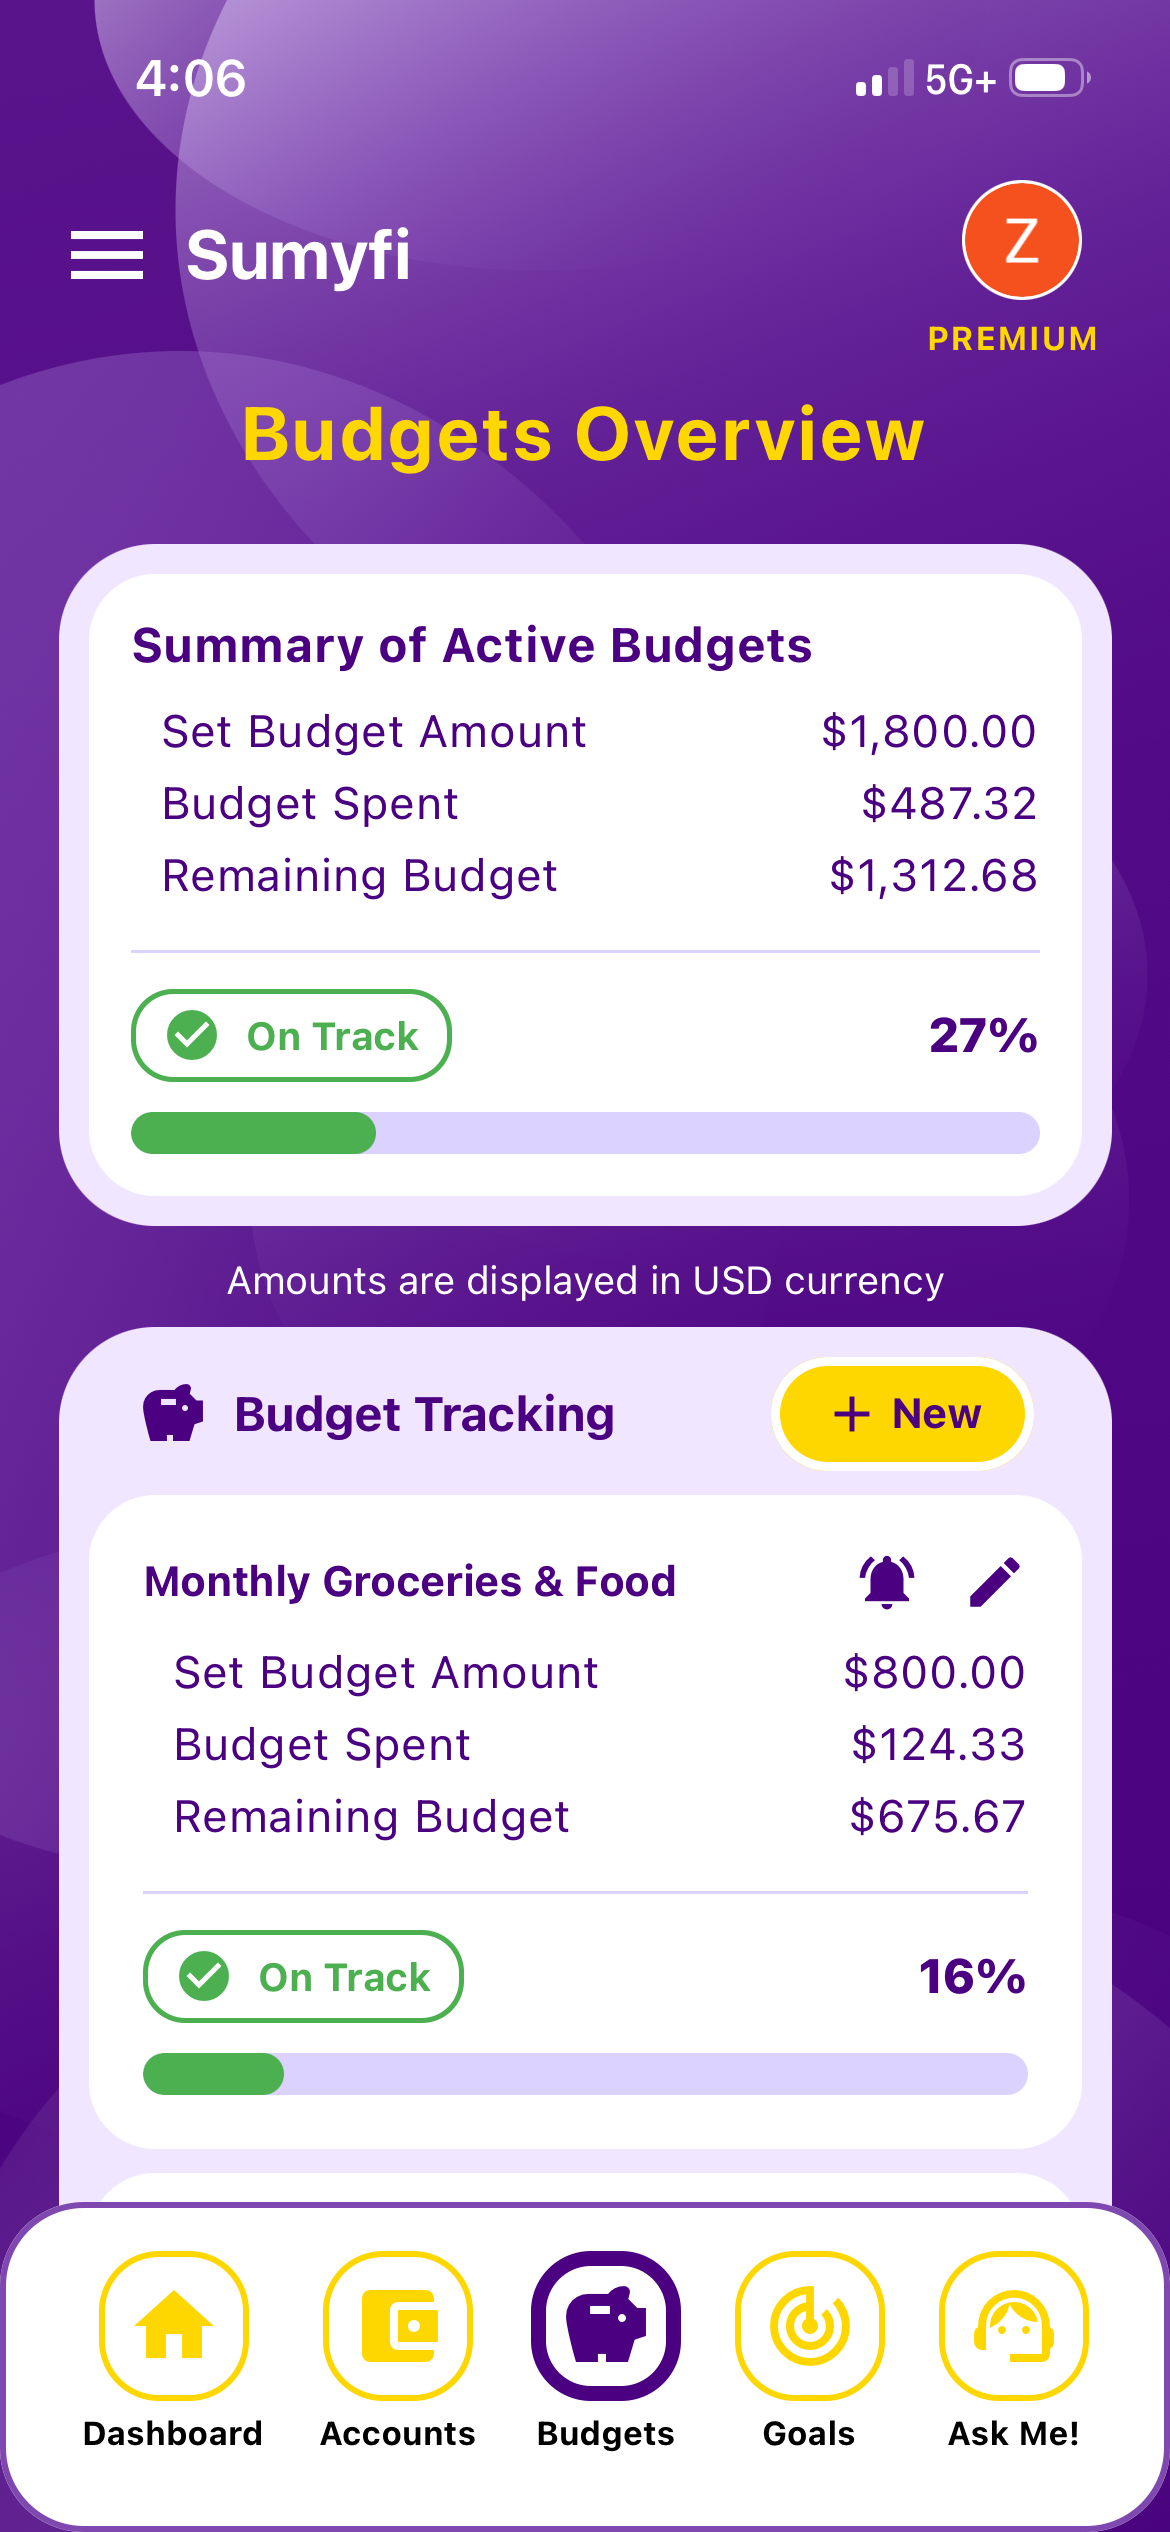
The first difference is the pricing model. Monarch is paid after its free trial. Sumyfi has a free plan with no card required that includes budgets, savings goals, transaction categorization, manual accounts, basic reports and CSV or Excel import. You can set up your budgets around a two-paycheck month, create a goal for the third paycheck, and add sinking funds for insurance and registration without paying.
Premium adds automatic sync through Plaid (read-only, with US and Canadian institutions supported and coverage depending on your bank), real-time account updates, custom spending alerts and advanced analytics. It also includes an AI assistant that can make changes when you ask in plain English, like 'create a goal called Car Insurance for $1,440 by March 1.' Premium has a 7-day free trial, so connect your trickiest US accounts during that week.
The dashboard keeps budgets, accounts, goals, net worth and recurring charges together, in USD. The subscriptions view detects repeating charges, ranks them by monthly cost, totals them for the year and shows what's due in the next 10 days, which helps with those annual memberships that renew without warning.
Where Monarch is stronger: shared household access for couples, deeper investment views, and a longer track record. If you and a partner both use Monarch's shared view, or you mainly use it to watch a portfolio, it's likely still the better fit.
Pros
- Free plan you can stay on, with Premium only if you want sync
- Works in USD with US banks through Plaid
- Recurring charges and goals on the same screen as budgets
Cons
- No shared household logins like Monarch's
- Lighter on investment and retirement account analysis
Which app fits which US household
Your situation matters more than any feature list. A single person on a biweekly salary with one credit card has very different needs from a dual-income couple with two 401(k)s, an HSA and a mortgage.
Couples who both log in
stay on Monarch if your accounts connect
Investment-focused households
Monarch, or Empower's free dashboard
Biweekly earners who want structure
any app that lets you plan the third paycheck
Paying but rarely opening it
a free plan like Sumyfi's, or a spreadsheet
Want help deciding what to change
Sumyfi Premium's AI assistant
Switching without a gap in your records
If you decide to try something else, overlap the two apps for one full month. Export your transaction history from Monarch as a CSV first, write down your budget amounts and goals, and set a reminder a week before your renewal date.
In Sumyfi you can import that CSV directly. It recognizes common column headers, so the file doesn't need to match a template exactly. Rebuild your budgets around your two-paycheck income, set up goals for your irregular costs, and compare balances against your bank statements at month-end. If everything lines up, cancel before the renewal. If it doesn't, you've spent a month learning that Monarch was the right call.