Sumyfi Editorial Team • Updated 2026-09-01
Retirement Dashboard App for Long-Term Progress With Everyday Context
A retirement dashboard app should do more than show investment balances. It should connect retirement progress to cash flow, debt, and the rest of the financial picture so long-term planning stays grounded in everyday reality.
Many retirement pages over-focus on one portfolio number and under-explain the broader system supporting it. Real retirement progress depends on contribution pace, debt pressure, spending behavior, and whether the household can keep following the plan without constant manual maintenance.
That is why the better retirement dashboard app is not just an investment screen. It is a long-term review surface that keeps retirement progress connected to the rest of the money routine.
If you want retirement tracking tied to the broader financial system instead of isolated account snapshots, this is the right page to evaluate.
At a glance
- Investments, debt, and cash flow together
- Built for long-term review
Helpful when you want track retirement progress alongside cash flow, debt, and long-term financial direction to stay tied to the balances, debts, and money behavior you review every week.
retirement dashboard app is more useful when it helps explain what is moving the number.
Long-term progress stays attached to current balances, debt, and behavior when retirement dashboard app stays connected to the broader dashboard.
Why this page matters
Retirement planning gets more believable when the dashboard shows how today supports tomorrow
A retirement dashboard app becomes useful when it closes the gap between long-term goals and current financial behavior. Users want to know whether saving pace, debt reduction, and spending habits are actually reinforcing retirement readiness or quietly undermining it.
That is why a strong dashboard should not isolate retirement from the rest of the money system. Long-term progress feels more trustworthy when it sits beside cash flow, liabilities, and the bigger household picture.
What to compare
The best retirement dashboard helps people interpret progress, not just watch balances move
Many tools can display investment totals. Fewer help the user understand whether the broader financial system is supporting the retirement plan. A better dashboard shows contribution direction, debt drag, and the context around long-term progress instead of leaving the user with one disconnected number.
That is also where product pages become more convincing. Buyers need a believable ongoing review workflow, not just a promise of sophisticated charts.
- Progress should connect to contributions and debt pressure
- The dashboard should still help in ordinary months
- Long-term readiness should be visible without leaving the broader money workflow
Best fit
This guide is strongest for people who want retirement tracked inside one wider household dashboard
Some buyers only want an investment portal. Others want a retirement dashboard that fits inside a fuller money review habit.
That separation matters for SEO and conversions. It gives This guide a clear job distinct from general investment tools or pure net-worth pages.
Buyer checklist
What a retirement dashboard should help you answer
- Can you see retirement progress beside debt and cash flow?
- Can you tell whether contributions are actually keeping pace?
- Does the dashboard stay useful outside of market highs and lows?
- Can the household review long-term readiness without opening multiple tools?
Product screenshots
See the product behind the copy
Screenshots shown: Dashboard, Accounts, Goals.
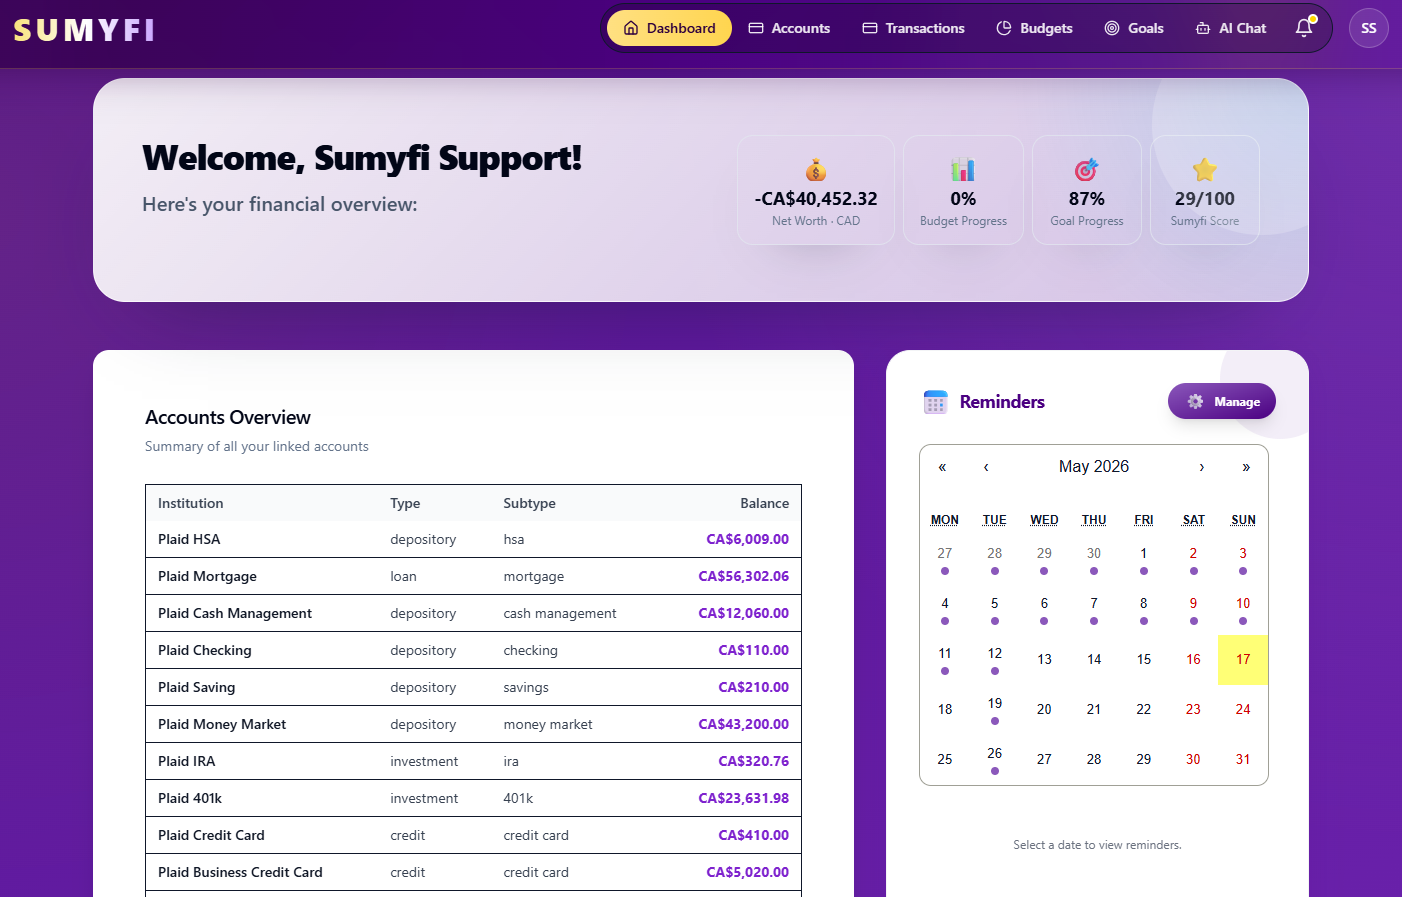
Dashboard shows balances, assets, and debts in one overview.
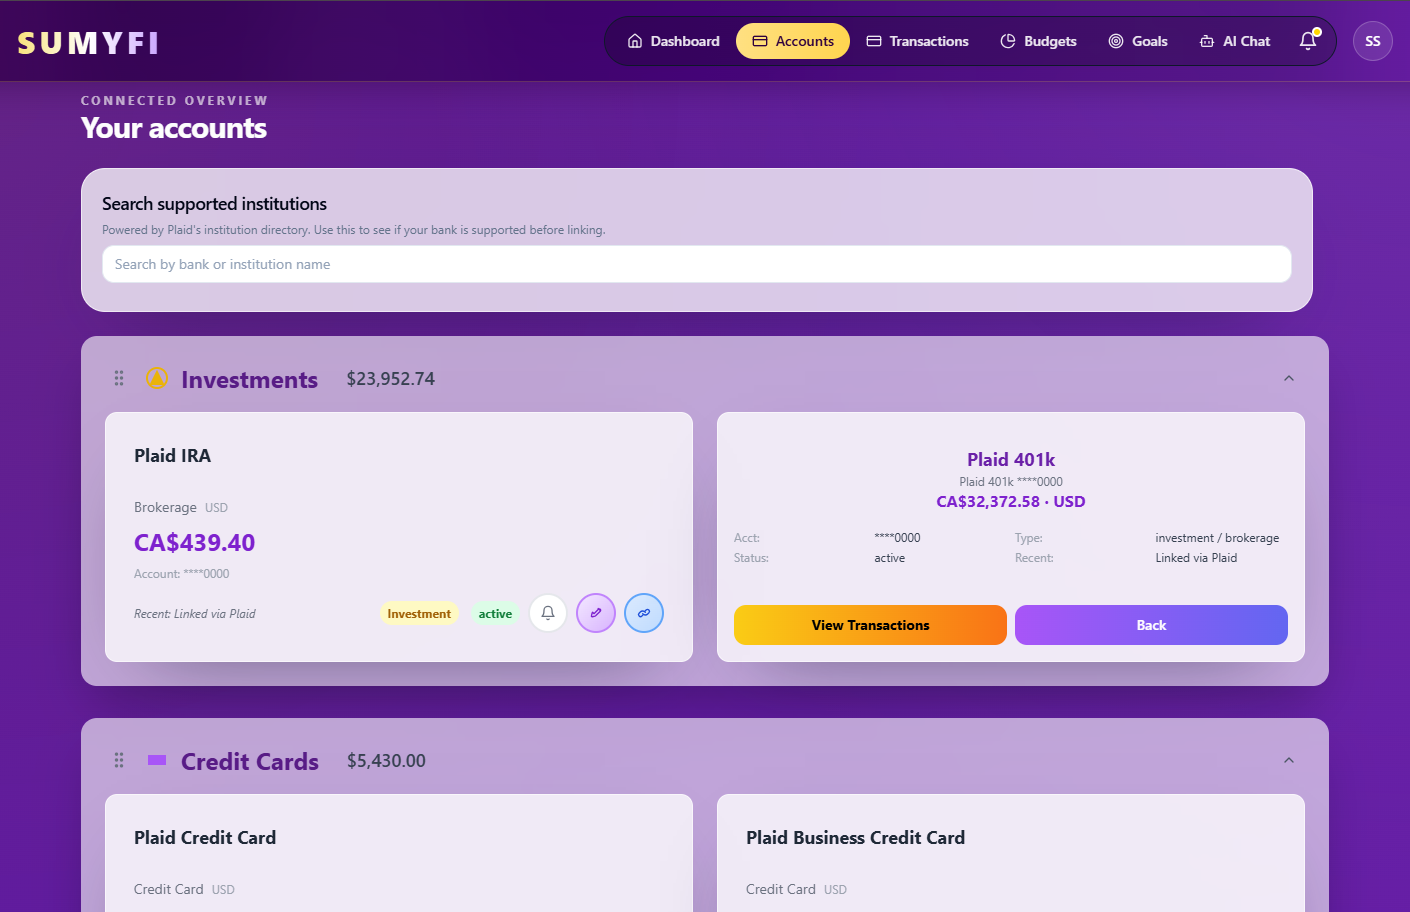
Accounts shows assets, debts, and balances in one account view.
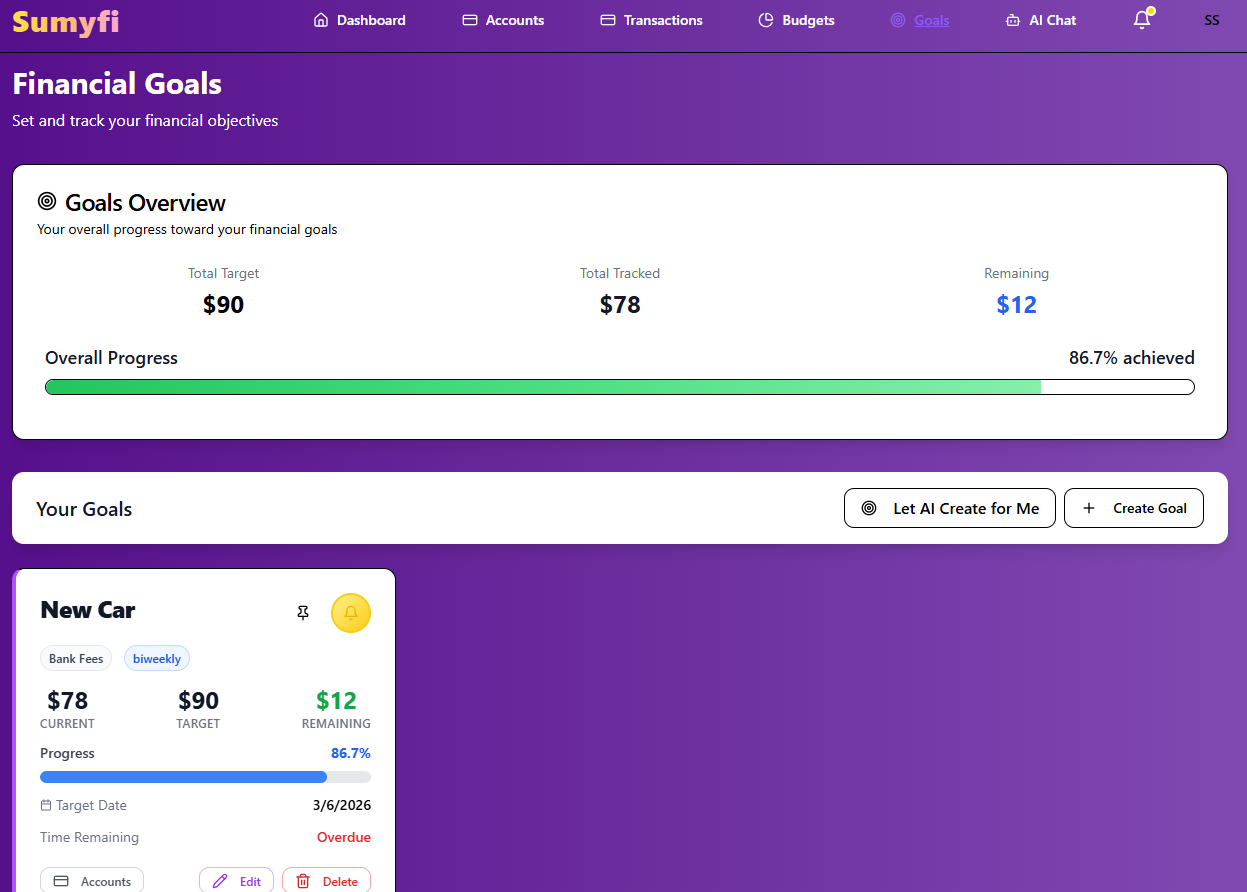
Goals shows progress targets alongside the broader balance picture.
Comparison table
How the options compare for retirement dashboard app
Compare how each option handles assets, liabilities, and the wider balance-sheet context behind tracking retirement progress alongside cash flow, debt, and long-term financial direction.
| Decision area | Sumyfi | Typical net worth tool |
|---|---|---|
| Net worth context | Long-term net worth tracking progress lives inside the wider money system rather than floating above it as an isolated score. That lines up better when the page is really about retirement progress alongside cash flow, debt, and long-term financial direction. | Typical net worth tool can make the headline net worth tracking number obvious, but the drivers behind it often feel less connected. That shortfall shows up faster when retirement progress alongside cash flow, debt, and long-term financial direction has to stay usable during ordinary weeks. |
| Assets and liabilities | One net worth tracking review can show assets, debts, and available cash without splitting them across tools. That is a better fit for searches centered on retirement progress alongside cash flow, debt, and long-term financial direction. | Assets and debts may be tracked, but the surrounding financial context in the net-worth review for retirement progress alongside cash flow, debt, and long-term financial direction tools is often thinner. That mismatch becomes clearer on searches centered on retirement progress alongside cash flow, debt, and long-term financial direction. |
| Progress interpretation | The net-worth view for retirement progress alongside cash flow, debt, and long-term financial direction keeps daily money behavior close enough to long-term progress that the number is easier to explain. That lines up better when the page is really about retirement progress alongside cash flow, debt, and long-term financial direction. | The dashboard may show movement clearly in the net-worth review for retirement progress alongside cash flow, debt, and long-term financial direction, though turning that movement into a practical next step still takes more work. That mismatch becomes clearer on searches centered on retirement progress alongside cash flow, debt, and long-term financial direction. |
| Recurring pressure | Recurring bills and spending habits in the net-worth review for retirement progress alongside cash flow, debt, and long-term financial direction remain visible so long-term progress is easier to judge honestly. That lines up better when the page is really about retirement progress alongside cash flow, debt, and long-term financial direction. | Progress in the net-worth review for retirement progress alongside cash flow, debt, and long-term financial direction is often visible, but the everyday recurring costs shaping that progress can feel more peripheral. That mismatch becomes clearer on searches centered on retirement progress alongside cash flow, debt, and long-term financial direction. |
| Desktop and mobile continuity | The net worth tracking story stays readable during a quick phone check or a deeper desktop review. That lines up better when the page is really about retirement progress alongside cash flow, debt, and long-term financial direction. | The the net-worth view may work across devices, though the richer explanation often feels thinner on either desktop or mobile. That gap is harder to ignore when the page is really about retirement progress alongside cash flow, debt, and long-term financial direction. |
| Best for | Best when net-worth tracking needs to stay grounded in the full money system. That lines up better when the page is really about retirement progress alongside cash flow, debt, and long-term financial direction. | More workable when a simpler scorecard is enough even if the reasons behind movement live outside the main tracker. That shortfall shows up faster when retirement progress alongside cash flow, debt, and long-term financial direction has to stay usable during ordinary weeks. |
Recommended next reads
Read 5 related articles next
Related reading for the next question.
FAQs
Frequently asked questions
What makes retirement dashboard app easier to evaluate?
The useful comparison is whether the dashboard shortens the path from visibility to a clear next step for retirement progress alongside cash flow, debt, and long-term financial direction.
How does Sumyfi handle account security?
The security model is built around displaying account data securely while retirement progress alongside cash flow, debt, and long-term financial direction stays separate from institution settings and fund transfers.
Can this workflow start with manual tracking?
Yes. A manual starting point is helpful when you want to test retirement progress alongside cash flow, debt, and long-term financial direction before connecting accounts.
What should I compare before switching?
Compare what happens after setup: which product keeps retirement progress alongside cash flow, debt, and long-term financial direction easier to understand and act from during an ordinary month.
Keep exploring
Next reads for retirement-dashboard buyers
These supporting pages help visitors compare adjacent long-term planning workflows.