Pros
one place for balances, cards, recurring bills, and spending context
Sumyfi Editorial Team • Updated 2026-09-01
The best account aggregation app in the USA should not only connect accounts. It should make it easier to keep seeing all their accounts in context and turn scattered balances, cards, and transactions into a decision-ready weekly dashboard.
People search for account aggregation when the money picture has become too fragmented to manage comfortably. A bank app shows one balance, a card portal shows another, investment accounts live elsewhere, and recurring bills still have to be tracked mentally or in a separate tool. The better product should reduce that stitching work immediately.
That means the page should compare more than sync capability. Buyers want to know whether the dashboard helps them interpret the combined view, spot pressure earlier, and keep account visibility tied to the rest of the monthly workflow instead of stopping at raw totals.
If you want a U.S. all-accounts dashboard that connects balances, recurring bills, budgets, and goals in one workflow, Sumyfi is worth comparing closely.
At a glance
The point of aggregation is not only to connect accounts, but to remove blind spots from weekly review.
Many apps centralize balances without helping users understand what deserves attention first.
Balances become more useful when recurring bills, spending drift, and goals remain visible beside them.
What to compare
Start with whether the app creates usable visibility or just piles data together. The better product should make it faster to answer practical questions: what changed, where pressure is building, which accounts matter most right now, and whether recurring bills or category drift are distorting the picture. That is the difference between simple sync and useful aggregation.
Next, look at what happens after the accounts are connected. Many users discover that they also need budgets, subscription awareness, and goal visibility in the same environment. The better app keeps that context in the same place after account sync is complete.
Pros and cons
Broader aggregation dashboards usually win on context. They make balances more meaningful by keeping them close to recurring bills, goals, and spending review. The tradeoff is that someone who only wants a minimal balance roll-up may prefer a narrower sync utility.
Pros
one place for balances, cards, recurring bills, and spending context
Pros
easier weekly review than checking institutions one by one
Pros
better long-term value than sync-only tools
Cons
may be broader than necessary if you only want a simple balance feed
Cons
most valuable when you want decisions, not only connected totals
Best-fit guidance
This guide is best for U.S. users who want one place to review checking, cards, savings, and broader monthly pressure together. That often includes households replacing multi-app routines that are too slow or too easy to ignore.
Someone should choose something else if they only want a narrow balance viewer and do not care about spending context, recurring charges, or connected planning. A simpler sync-first product may be enough in that case.
Best for
users juggling several financial accounts and wanting one weekly dashboard
Best for
households that want balances tied to recurring-bill and spending context
Choose something else if
you only want a lightweight balance roll-up
Choose something else if
you do not need budgeting, subscriptions, or goals beside connected accounts
How to test
Connect your most-used bank and card accounts first, then run one normal weekly review. Check whether the app helps you spot the most important shifts faster: rising card balances, recurring bills, unusual spending, and pressure points before the next paycheck.
After that, add savings or investment accounts and one or two recurring bills that often create blind spots. If the combined picture feels easier to interpret than your old routine, the app is improving your workflow. If it only looks fuller, it probably is not.
Connect primary checking and credit cards first
Review recurring bills in the same session
Add savings or investment accounts next
Judge the app by clarity after sync, not sync alone
Buyer checklist
What U.S. account-aggregation buyers should verify first
Why Sumyfi
Why Sumyfi is a strong aggregation choice in the U.S.
Sumyfi works especially well when account aggregation is only the beginning of what the user needs. Connected accounts stay close to recurring charges, budgeting, and goal progress so the whole picture is easier to act on.
Product screenshots
See the product behind the copy
Screenshots shown: Accounts, Dashboard.
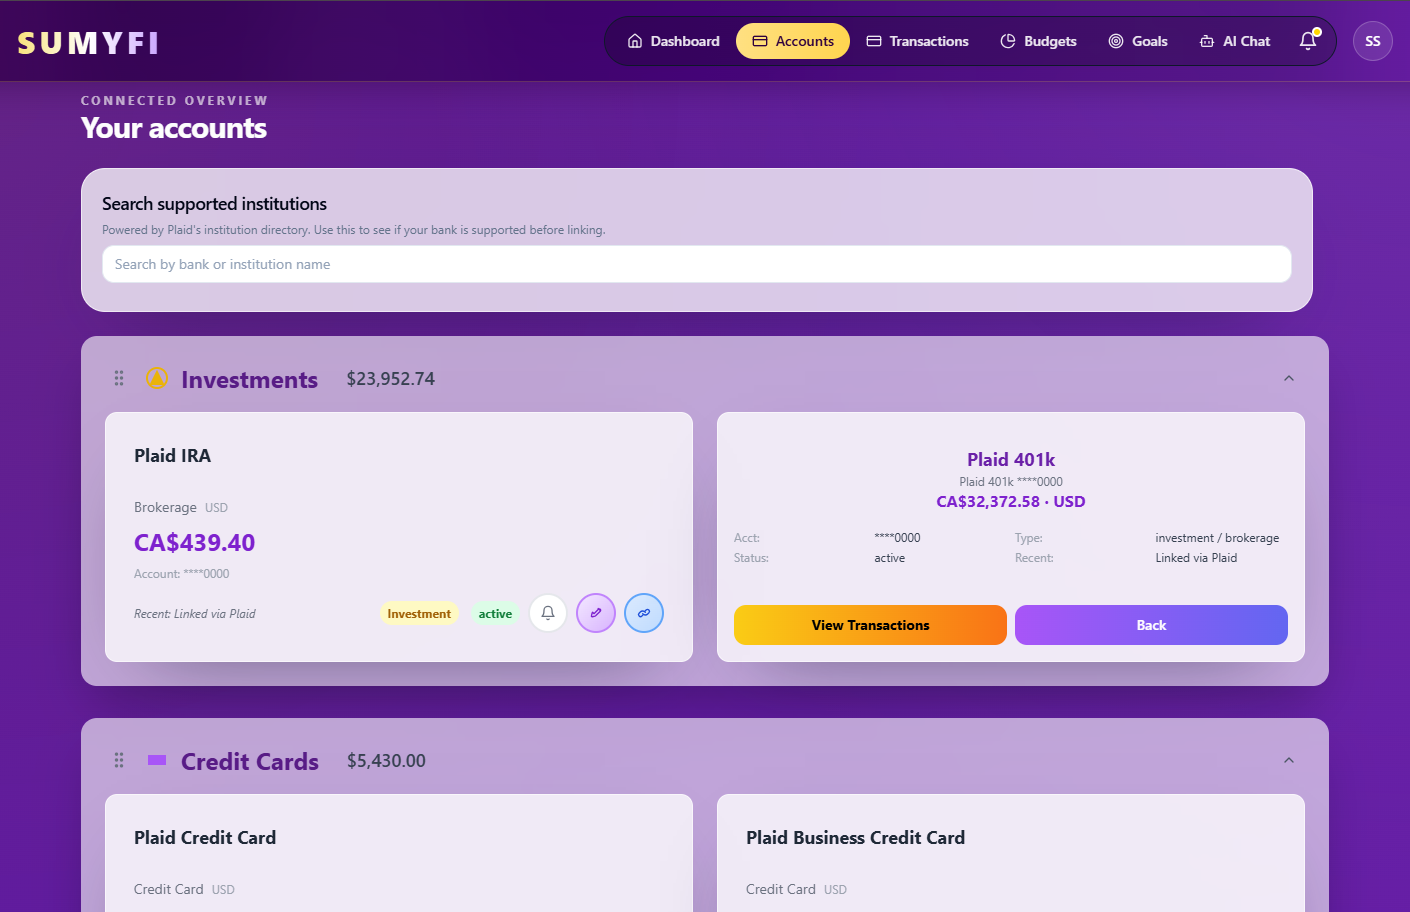
Accounts gives you a single view of connected and manually added accounts.
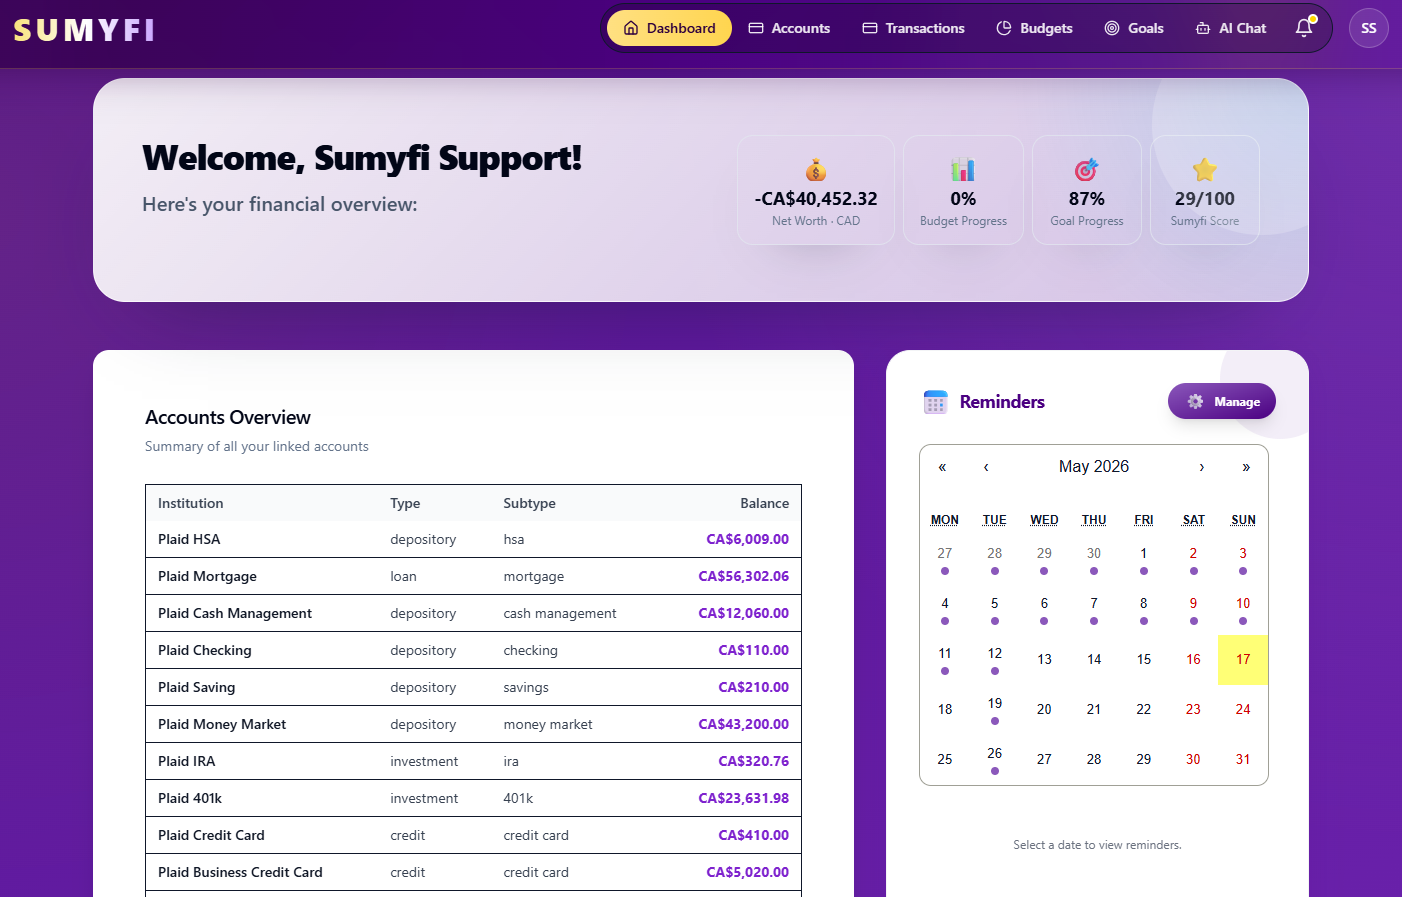
Dashboard brings balances, transactions, and linked accounts into one overview.
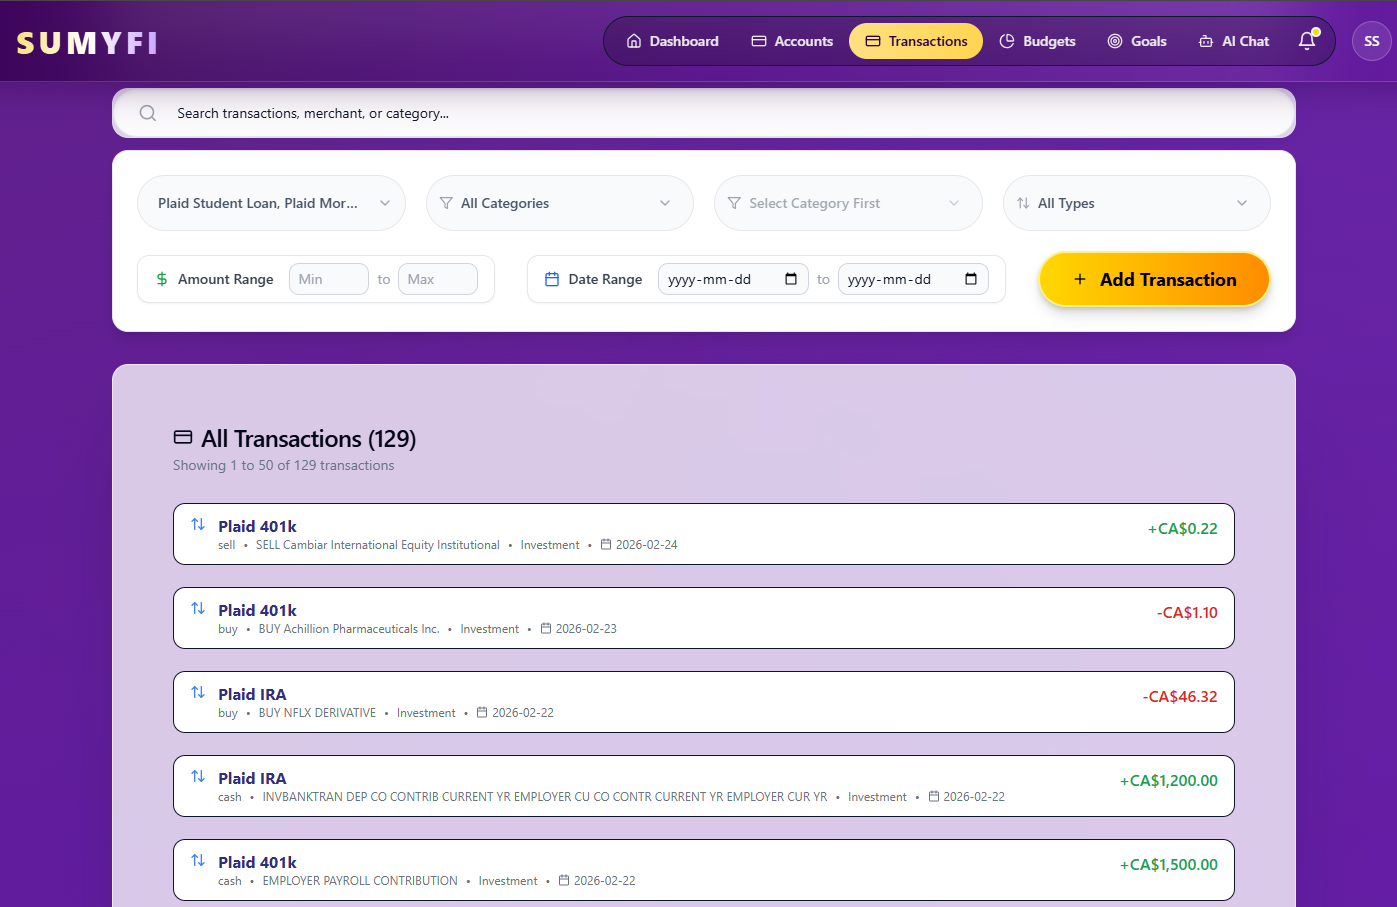
Accounts gives you a single view of connected and manually added accounts.
Comparison table
Best account aggregation apps in the USA compared
This table focuses on what aggregation buyers actually evaluate at decision time: connected-account visibility, recurring-bill context, broader dashboard usefulness, and fit after setup week.
| Decision area | Sumyfi | Monarch Money | Empower | Copilot Money | Rocket Money |
|---|---|---|---|---|---|
| All-account visibility | Built into the broader dashboard | Strong premium dashboard view | Strong wealth-style visibility | Strong polished overview | Strong, but more recurring-bill oriented |
| Recurring-bill context | Built into the same dashboard | Available | More secondary | Secondary | Core strength |
| Budgeting connection | Integrated | Flexible | Limited | Moderate | Lighter emphasis |
| Goal and progress context | Strong | Strong | Moderate | Moderate | More limited |
| Best for | Users wanting one dashboard for accounts plus the rest of the money workflow | Users wanting a premium flexible all-in-one view | Users prioritizing wealth visibility | Users prioritizing polished overview design | Users leading with subscription cleanup |
Recommended next reads
Read 5 related articles next
Related reading for the next question.
FAQs
Frequently asked questions
What is the best account aggregation app in the USA?
The best account aggregation app in the USA is the one that connects balances, cards, recurring bills, and broader money context in a dashboard you will actually use every week. Sumyfi is built around that fuller workflow rather than sync alone.
What does an account aggregation app do?
An account aggregation app brings balances and activity from multiple accounts into one place so you can review the whole picture faster. The strongest products also support budgeting, recurring-charge review, and goals beside those connected accounts.
Who should choose a broader aggregation dashboard?
A broader aggregation dashboard is best for users who want connected accounts to support real weekly decisions, not just a list of balances. That usually includes households juggling several institutions, cards, and recurring bills.
How can I tell if an aggregation app is too shallow?
If it connects accounts but still leaves you checking other tools for recurring bills, budgeting, or clearer interpretation, it is probably solving only part of the real problem.
How should I test an account aggregation app before switching fully?
Connect your primary accounts first, run one real weekly review, then see whether the app helps you understand balances, recurring pressure, and what changed faster than your old routine.
Keep exploring
Next guides for U.S. aggregation buyers
These pages help account-aggregation visitors move into adjacent buying decisions around dashboards, subscriptions, budgeting, and trust.